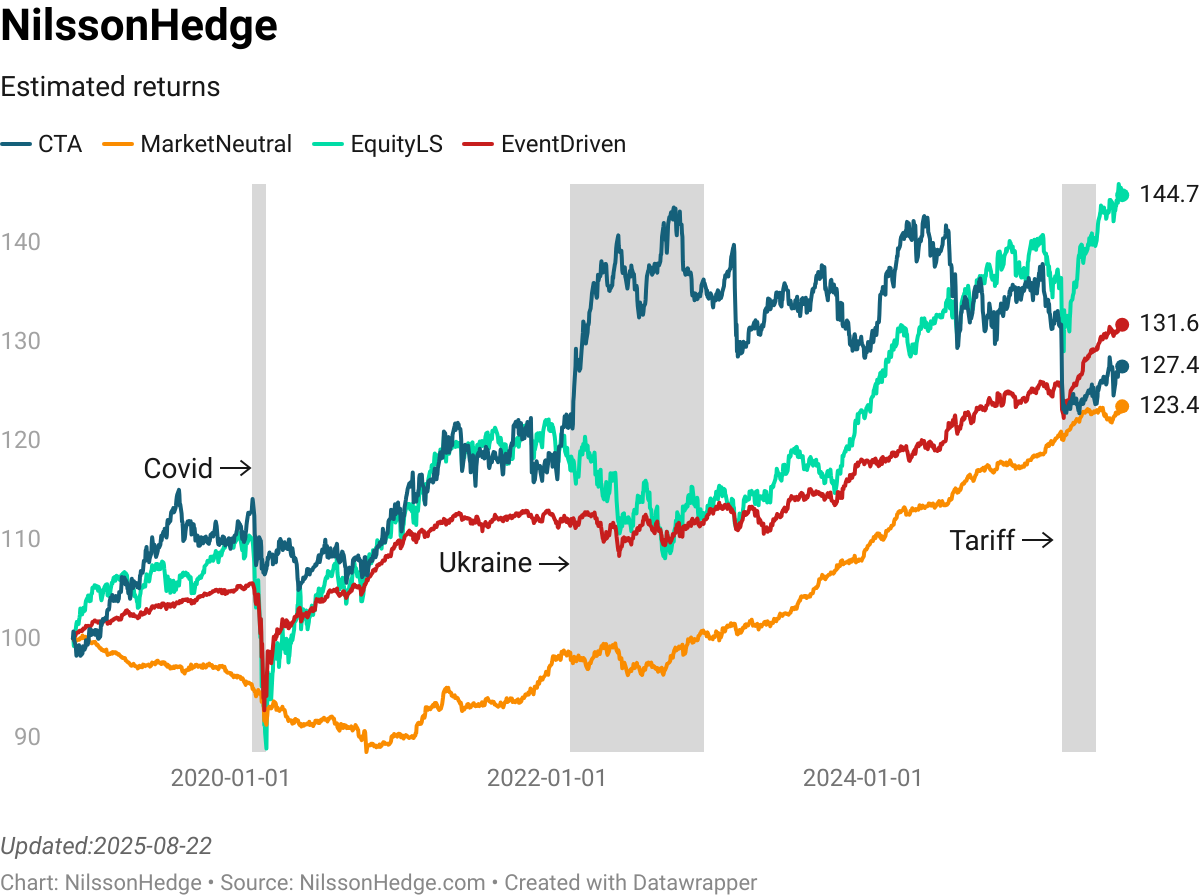
❌

Reading view

2023 Survey of the top 50 Hedge Funds

Global Investment Report’s survey of the Top 50 hedge funds is unique industry research. This year is the 20th edition of the survey, which previously has been featured in The Wall Street Journal, Barron’s, FinancialTimes, and Institutional Investor.

We had the opportunity to sit down with the survey’s manager Eric Uhlfelder and quiz him about his findings and how he devises his ranking of the industry’s most consistently performing hedge funds. If you want to skip the fireside chat I had with Eric, please feel free to jump directly to a copy of his report at Global Investment Report.

Eric follows a broader range of strategies than what we do, and the perspective of the larger funds is inspiring and adds context to an industry that struggles with performance and perception. The 20th edition of the report spans a large number of topics, ranging from the expected (the survey of the 50 most consistently performing funds) to the unexpected (an interview with the former US Ambassador to Russia).

Can you describe your scoring methodology and the requirements to qualify for your list? How persistent are the persistent funds and how much do they change from year to year?

  • There are several minimum thresholds that funds must meet to be considered. Now that I’ve applied these standards for five consecutive years, this approach is revealing the most consistently performing managers.Β  That’s further borne out with more than two-thirds of the Top 50 funds regularly qualifying for the subsequent year’s survey. Here are the basic minimum requirements.Β 

Minimum history:

5 years.Β  That’s actually longer than the average life expectancy of the average hedge fund. Funds that reach that age likely have been buffeted by various edges of the market cycle, which can tell us something about their investment and management skills.

Minimum performance hurdles:

Funds need to have delivered minimum absolute returns over each of the past five years.Β  That hurdle started at +5% in 2018 (when I prepared the survey for The Wall Street Journal), then it fell to +4.5% along with the risk-free rate.Β 

Because 2022 was an awful year for most strategies as interest rates soared, that number turned negative to -5%.Β  Still, 44 of this year’s Top 50 funds made money last year and 3 additional funds lost less than 2%.Β Β Β 

Minimum Assets under management (fund or strategy):

Fund or strategy aum of at least $300 million. This helps ensure management can afford top-tier service providers, which helps ensure sound management practices and reporting accuracy.

Only broad-strategy funds:

Avoiding narrowly focused funds means performance more accurately reflects management decision making, not a good industry tailwind or a nasty headwind which managers can’t do too much about.

There are many multi-strategy funds on your lists. These are managers that have enjoyed tremendous success lately. How do you view such funds compared to single PM/focused hedge funds? Will they persist or perish? And will investors stomach the pass-throughs?

Photo credit: Carin Drechsler-Marx
  • The idea of flexible multistrategy funds seems to be an interesting all-weather investment solution.Β  But on average, they aren’t doing particularly well.Β  According to BarclayHedge, the average multistrategy fund lost 3% last year and over the trailing 5 years through 2022, returned only 2.2%. So all the rage about the strategy really involves a select group of outliers, like Citadel Wellington (ranked No. 3) and D. E. Shaw Composite (No. 14).Β 
  • Both did very well last year and delivered 5-year trailing annualized returns of 23% and 15.4%, respectively.Β  Their underlying success is based on their manager and strategy selection and weighting. These folks are certainly proving more successful than the fund-of-funds model. That said, a single strategy manager is much easier to break down and discern what’s driving exposure, risk, and returns.Β  That transparency is always helpful, especially if you’re doing your own homework.Β 
  • Your question about sustainability, especially with the most successful funds, is on everyone’s mind.Β  The concerns I hear from large allocators: they’re increasingly worried about growing use of leverage, rising fees and pass-through expenses, and internal opacity.Β  I’m worried about managements’ belief in limitless capacity.Β  That’s counter-intuitive to what my research has found over the years. The larger a fund gets, the more limited are its investment opportunities, and then this can lead to more risky decision making to find a new edge.Β 
  • Searching for great returns certainly might explain growing use of leverage.Β  But that’s conjecture. It’s also hard to identify performance drivers of such complex portfolios. Then, with internal manager compensation often linked to how much of the pie a manager is running, then there’s the issue of keeping all of the team happy, something maybe akin to herding cats.Β  But my largest concern about the very biggest funds that are delivering extraordinary returns year after year, it feels like musical chairs.Β  Regardless of whatever assurance management provides, the music always stops.Β  And no one can predict when that will happen. Β 

You do a remarkable job of providing transparent and accessible coverage of complex strategies, and activities related to these funds. How do you tease out relevant details for each fund?

  • Thanks.Β  I guess perseverance is key.Β  The longer you research an industry, the more you learn, and the more key industry figures begin to trust and open up to you.Β  Like fund management itself, it’s all about sticking to a process.Β  But then something else happens . . . you start to see links between manager, strategy, and performance . . . and when you see deviations that don’t make sense, you know the questions that really need to be answered to help understand what’s going on.
  • But I’ll be the first to say, I still feel like I’m often just scratching the surface.Β  I can combine facts and reverse engineer an ostensible explanation of what I’m seeing.Β  But it’s not the same as being in the engine room and seeing firsthand what’s driving behavior and performance.Β  And there’s the rub.Β  There will always be uncertainty when investing in hedge funds along with most other alternative vehicles. Β 

What are some common challenges that you and other journalists face when attempting to interview publicity-shy funds or obtain performance information from them? Some of them are hellbent to stay out of the public domain and they are very reluctant to provide return transparency.

  • The biggest challenge: most journalists write negatively about the industry.Β  There’s an abundance of schadenfreude going on. A key reason for it: the majority of hedge funds are not particularly good investments and the industry is hard to truly understand.Β  Even when journalists approach hedge funds on a benign subject, that kind of story can still come with a dig.Β 
  • I can’t blame good managers from being reticent.Β  It takes time to get stories and details precisely right, and most journalists are working under strict deadlines. One off-handed statement or poor reference in an article can prove very costly to a manager.Β  So why take the chance? It helps when an analyst or journalist understands this, because it’s expensive and hard to start a hedge fund and most press exposure is likely not worth the risk.
  • That said, last year’s survey included six fund profiles, most of whom had never been interviewed before.Β  They ranged from a small US hedged equity shop, a merger arbitrage manager who was part of a multi-billion-dollar firm, to a Middle East/North African equity fund and a manager investing in frontier African sovereign debt.Β 
  • Managers see that for two decades my goal has been to focus on the handful of shops that are actually delivering on the promise of independent asset management.Β  Since I’m interviewing managers who have a solid long-term track record, they know I’m looking to explain their success.Β 
  • But at the same time, I make it clear that there’s also a lot to learn from missteps.Β  I want to write about when a manager stumbles.Β  They all do at one time or another.Β  There’s no embarrassment there.Β  Recovering from problems reveal character and commitment to their investors.Β  Moreover, there’s often a really good lesson in explaining why an ostensibly sound investment turns bad.Β 
  • Sometimes it’s timing, sometimes it’s not having seen all the risks, sometimes, it can be triggered by an event that comes out of left field (US baseball parlance, i.e., coming out of nowhere).Β  To me, a manager that is candid in explaining failure is more likely to be a straight-forward type of person, and that quality, along with proven competence, is what allocators should be looking for.Β Β  Β 

You have maintained this remarkable survey for 20 years. How long do you intend to continue and what is in store for the next 20 years?

pexels-photo-164527.jpeg
  • I’m motivated to sustain this survey because none of the publications that used to support such efforts (which I managed) are producing this time-consuming research.Β  You’ll more readily find articles on the wealthiest funds and managers than any kind of in-depth look at performance. I like having cornered this small piece of the market.Β 
  • Something quite different from any other survey I’ve seen or managed: I produce quarterly reports that track the subsequent performance of the Top 50 funds for the entire year following their selection. This review tests the merits of my survey.Β  Last year’s Top 50 funds, selected based on 5-year trailing returns through 2021, proceeded to outperform the S&P 500 by nearly 24 percentage points in 2022.
  • I like seeing what each year brings, new allocators and managers that come my way. It’s a remarkable learning experience. And the survey is a compelling forum in which I can dive into contemporary issues and finance.Β  I’m always wondering around what theme I should build the survey. And my work always leads to new unexpected opportunities, like meeting up with the head of NilssonHedge. Who’d have thought?

More of Eric’s work can be found here The Global Investment Report.

  •  

Best’n’Worst – June 2023

We have collected returns for 85% of the funds that are expected to report for June 2023 and we are proud to present our β€œhit list”. We present the top five, but also the bottom five to balance the impression. Where there are gains, there are also losses.

To sign up, simply visit our website and provide us with your email address. We promise not to spam you or share your information with third parties, and you can unsubscribe at any time. Don’t miss out on this valuable opportunity to stay ahead of the curve in the ever-changing world of finance.

CTA

Polar Star Management : Polar Star Spectrum Fund Limited  :  18.00% [77.00]<br> Rosetta Analytics : RL Carbon  :  16.04% [9.89]<br> Astute Capital Group : Pulse Program  :  13.88% [1.50]<br> Glenhaven Capital : Glenhaven Global II  :  12.97% [5.69]<br> CTAFX.com : Managed FX Accounts II  :  11.75% [0.22]<br> Pan Capital Management LP : Energy Fund  :  -7.72% [1067.00]<br> Gresham Investment Management : GreshamQuant Acar  :  -8.00% [1191.00]<br> QDRA Pty : Dynamic Macro  :  -9.72% [2.06]<br> EMC Capital Advisors : Tactical Commodity  :  -11.96% [8.61]<br> Vigo Capital : Fund  :  -20.78% [0.51]<br> >


Soaring Pelican : Overnight Advantage  :  9.27% [0.90]<br> Mulvaney Capital Management : Global Diversified Program  :  8.61% [296.00]<br> ABR : Enhanced Short Volatility  :  7.56% [2.24]<br> Glenhaven Capital : Glenhaven Global II  :  12.97% [5.69]<br> Numberline Capital Partners : Numberline  :  -0.96% [0.73]<br> Superfund Capital Management : Green SPC 1.5x  :  1.25% [62.63]<br> GT Capital CTA : Dynamic Trading (Client)  :  -6.19% [0.12]<br> Superfund Capital Management : Green Silver SICAV  :  -1.72% [62.63]<br> Superfund Capital Management : Green SPC 2x  :  1.86% [2.72]<br> Vigo Capital : Fund  :  -20.78% [0.51]<br> >

To explore the full list of CTAs and their rankings, including dynamic updates as new data becomes available, we invite you to visit our website at the Link provided.Β 

Market Neutral

Leibniz Group : Dislocation  :  5.00% [0.00]<br> Maverick : QM Neutral (GS)  :  4.55% [302.60]<br> JPMorgan : Europe Equity Absolute  :  3.91% [283.45]<br> QS : QS Global Market Neutral  :  3.57% [0.00]<br> Seven : Fortress Fund  :  3.51% [1.93]<br> Fulcrum Asset Management : Thematic Equity Market  :  -1.85% [394.12]<br> Dalton Strategic Partnership : Velox  :  -2.06% [277.99]<br> Pula Capital Managament : Pula Capital Fund  :  -2.22% [14.20]<br> Desjardins Global Asset Management : Alt Long Short Global Equity Market ETF  :  -2.40% [1.45]<br> Osmosis : More World Sustainable  :  -3.17% [31.97]<br> >

Leibniz Group : Dislocation  :  5.00% [0.00]<br> Zest : North America Pairs Trading  :  1.80% [38.42]<br> Blackrock : Asia-Pacific Diversified  :  2.74% [39.16]<br> Exane : Ceres  :  1.55% [171.61]<br> Gondor Capital : Gondor Partners Ltd  :  1.76% [10.00]<br> JanusHenderson : Global Equity Market Neutral  :  0.41% [32.52]<br> Desjardins Global Asset Management : Alt Long Short Global Equity Market ETF  :  -2.40% [1.45]<br> Fulcrum Asset Management : Thematic Equity Market  :  -1.85% [394.12]<br> RAM : Long Short European  :  0.77% [129.74]<br> PIMCO : PIMCO RAE Fundamental Advantage PLUS  :  0.22% [0.00]<br> >

To explore our extensive list of Market Neutral funds and their dynamic rankings, we invite you to visit our website at the link provided here.Β 

Equity Long/Short

Redwood Partners : Redwood  :  12.80% [8.80]<br> Accendo Capital : Accendo Capital  :  8.74% [216.00]<br> Coeli Asset Management : Coeli Global Opportunities  :  8.35% [0.00]<br> Toews : Toews Tactical Opportunity  :  7.90% [0.00]<br> Snow Capital : Snow Capital Long/Short Opportunity  :  7.25% [0.00]<br> Odey : Swan  :  -4.00% [63.13]<br> Pensum Asset Management : Global Opportunities  :  -4.78% [15.60]<br> Argonaut : Absolute Return  :  -5.04% [99.14]<br> Atlant Fonder : Atlant Protect  :  -5.56% [5.40]<br> LF Brook : Absolute Return  :  -7.14% [464.66]<br> >

HELSINKI CAPITAL PARTNERS : HCP Focus Fund  :  6.04% [10.80]<br> RiverPark : RiverPark Long/Short Opportunity  :  4.21% [0.00]<br> Pareto Asset Management AS : Pareto Total  :  2.42% [844.30]<br> Incline : Global Long Short  :  3.66% [9.51]<br> Alkeon : Equity Long/Short  :  4.21% [46.69]<br> Veritas : China  :  1.68% [27.57]<br> Odey : Swan  :  -4.00% [63.13]<br> Disciplined Alpha : U.S. Long Short  :  1.12% [4.47]<br> Pensum Asset Management : Global Opportunities  :  -4.78% [15.60]<br> Accendo Capital : Accendo Capital  :  8.74% [216.00]<br> >

To explore our extensive Equity Long/Short-list, with dynamic rankings, please see Link

Event Driven

Hadron : Alpha Select  :  16.32% [7.18]<br> Gabelli : Mergers & Acquisitions  :  4.78% [0.00]<br> Neuberger Berman : Distressed Debt Extended Life Shares  :  3.70% [0.00]<br> Third Point : Third Point  :  3.67% [0.00]<br> Cheyne : Cheyne Arbitrage (U Access)  :  2.82% [36.63]<br> Abrax : Merger Arbitrage  :  -0.17% [17.54]<br> Camelot : Camelot Event Driven  :  -0.17% [0.00]<br> Mygale : Event Driven (ML)  :  -0.27% [246.98]<br> Odey : Special Situations  :  -1.31% [41.38]<br> Neuberger Berman : Distressed Debt Global Shares  :  -4.05% [0.00]<br> >

Neuberger Berman : Distressed Debt Extended Life Shares  :  3.70% [0.00]<br> Hadron : Alpha Select  :  16.32% [7.18]<br> Portland : Hill Catalyst Driven  :  2.36% [16.81]<br> Formue Nord : Formue Nord Markedsneutral AS  :  2.10% [39.40]<br> CIAM : Satellite Event Driven  :  1.76% [12.08]<br> KiteLake : Event Driven  :  0.59% [494.86]<br> Alpine : Merger Arbitrage  :  1.79% [195.07]<br> Abrax : Merger Arbitrage  :  -0.17% [17.54]<br> Odey : Special Situations  :  -1.31% [41.38]<br> Neuberger Berman : Distressed Debt Global Shares  :  -4.05% [0.00]<br> >

To explore our extensive Event-Driven list, with dynamic rankings, please see Link

Fixed Income

Danske Bank Asset Management : Danske Invest Fixed Income Global Value  :  3.89% [825.60]<br> Capital Four Management : Capital Four Structured Credit Opportunities Fund  :  1.07% [97.20]<br> Selwood : Market Neutral Credit (Alma)  :  1.88% [127.88]<br> Danske Bank Asset Management : Danske Invest Fixed Income Relative Value  :  1.71% [412.00]<br> RBC Bluebay : Emerging Market Unconstrained Bond  :  4.90% [386.11]<br> CQS : New City High Yield Fund  :  -4.41% [0.00]<br> Secured : Secured Income Fund Plc  :  -5.30% [0.00]<br> VPC : Specialty Lending Investments  :  -9.18% [0.00]<br> GCP : Asset Backed Income  :  -7.35% [0.00]<br> Highbridge : Credit Fund  :  9.25% [0.00]<br> >

To explore our extensive Fixed Income list, with dynamic rankings, please see Link

Risk Premia

Nomura : Fixed Income Risk Premia  :  9.21% [1.50]<br> AQR Capital Management : Style Premia Alternative  :  8.54% [0.00]<br> AQR Capital Management : Style Premia  :  7.54% [342.88]<br> AQR Capital Management : Alternative Risk Premia  :  6.57% [0.00]<br> Catalyst Funds : Systematic Alpha  :  5.77% [0.00]<br> Fortem Capital : Alternative Growth  :  -1.66% [42.60]<br> Nordea Asset Management : Nordea 1  Alpha 10 MA Fund  :  -1.97% [5442.00]<br> Nordea Asset Management : Nordea 1  Alpha 15 MA Fund  :  -3.06% [5325.60]<br> Lumyna : Merrill Lynch MCLX  :  -3.75% [251.35]<br> Metzler : Alternative Multi Strategy  :  -4.55% [24.28]<br> >

Catalyst Funds : Systematic Alpha  :  5.77% [0.00]<br> Nomura : Fixed Income Risk Premia  :  9.21% [1.50]<br> Blackrock : Style Advantage  :  2.83% [96.98]<br> Neuberger Berman : US Equity Put Write  :  2.23% [535.08]<br> AQR Capital Management : Style Premia Alternative  :  8.54% [0.00]<br> BNP Theam : Absolute Alpha  :  1.37% [13.87]<br> Nordea Asset Management : Nordea 1  Alpha 15 MA Fund  :  -3.06% [5325.60]<br> Credit Suisse Multialternative : Credit Suisse Multialternative  :  1.27% [0.00]<br> Metzler : Alternative Multi Strategy  :  -4.55% [24.28]<br> BNP Theam : Quant Equity  :  0.86% [17.47]<br> >

To explore our extensive Risk Premia list, with dynamic rankings, please see Link

Crypto

P-Hat Fund : P-Hat Fund  :  16.88% [0.00]<br> Blackstone Crypto Fund : BLACKSTONE  :  14.60% [0.00]<br> Future Index : FUTUREINDEX  :  13.77% [0.00]<br> 3iQ Corp : The Bitcoin Fund  :  12.07% [237.87]<br> Disguise Edg : MMALUNA  :  11.86% [0.00]<br> Arctur DeFi : MULHACEN  :  -16.35% [0.00]<br> Stable WCI : STABLEWCI  :  -18.26% [0.00]<br> Bitcoin Crypto Assets : BITCOINCRYPTOASSETSFUND  :  -20.05% [0.00]<br> NFT MetelkovaCryptoUnderground : NFTMETELKOVACRYPTOUNDERGROUND  :  -25.53% [0.00]<br> Hole in One Josch : 554BC485571344C890D16DC3BE4460  :  -40.86% [0.00]<br> >

TheCryptoOwl Strategy : THECRYPTOOWL  :  -1.34% [0.00]<br> Hole in One Josch : 554BC485571344C890D16DC3BE4460  :  -40.86% [0.00]<br> Crush : CCC Crush Crypto Core  :  -1.02% [0.00]<br> Princess : BOSTI22  :  8.72% [0.00]<br> Amigo Feliz II : AMIGOFELIZII  :  -1.52% [0.00]<br> Sustainable Crypto Selection : SCS Sustainable Crypto Selection  :  0.32% [0.00]<br> GAMECHANGER FUND : GMFUND GAMECHANGER FUND  :  -11.07% [0.00]<br> LibertyRoad Capital : ETH Negative Gamma Strategy  :  -9.77% [0.00]<br> Low Fees Top Fundamentals : Low Fees Top Fundamentals  :  -8.18% [0.00]<br> INVESTMOX : INVESTMOXROLLERCOASTER INVESTMOX Rollercoaster  :  -10.51% [0.00]<br> >

To explore our extensive Crypto Strategy list, with dynamic rankings, please see Link

Past performance is not indicative of future results.

  •  

Half Year Index Review

Summer is setting in across most markets and we see relatively small moves across our strategy indices. Most of them are showing positive numbers for the year, with the minor exception of Event Driven strategies that are struggling to deliver positive results. Volatility has been relatively low and perhaps a hindrance to the more dynamic strategies. Together with sector and style shifts in equity markets, the first half of the year was somewhat mediocre for the average Hedge Fund.

NH Main Strategy Indices (Ex Crypto)

Risk Parity, which is nowadays a traditional asset allocation strategy, has enjoyed an upward drift in equity markets and less catastrophic bond performance. The volatility overhang from last year is still reducing position sizes for most risk-managed strategies.

Long/Short Equity has continued to benefit from the explicit (yes, not implicit) beta component but has, on average, struggled to deliver the expected 0.5 x Major Equity indices. With the US Equity Market up ~15%, seeing 3% for ELS is underwhelming. They may have partially preserved capital better last year, but the upcapture on a year-to-date basis has been on the low side.

In 2023, Technology stocks have been a tear. Here the performance of $ARKK with a performance of 44% YTD is a good illustration of the recovery. Like Crypto strategies, it has a large drawdown to recover from 2022. The rapid shifts in styles and sectors have not made it easy to be a long/short equity strategy.

Event Driven has failed to produce any spectacular performance as of late, as deal flows have been rather unremarkable, seeing a decline last year and a weak start to 2023.

Crypto strategies experienced some remarkable fireworks in January but have thereafter been a tad boring. We noted earlier that the dispersion of the managers is now at all-time lows.

And finally, what you have been waiting for, CTAs have done a remarkable job of recovering the March Fixed Income related drawdown. Our main CTA index is now back to positive (+0.7% for 2023). That does, however, hide a lot of dispersion between managers, but most styles have delivered about the same numbers. Momentum-based (aka Trend Followers) strategies are still down for the year whereas option strategies have done nicely for the year.

CTAs have done a number of position changes, but are still β€œshort-ish” in Fixed Income despite the bear-market rally in March. Otherwise, we note a switch to long positions in Copper, Equities, and in the Euro, short in Crude Oil, and whipsaws in Gold.

The J8 CTA index gives an indication of positions and changes for a concentrated strategy

With that, we hope that the second half of the year will present better trading opportunities.

  •  

Flash Report – June 2023

A few days into July, we can present our first estimate of hedge fund performance for June 2023. June looks like a strong month for most strategies. The start of the summer offered glowing hot equity markets, interesting developments in Cryptos (ETFs galore), and a continued guessing game if the inflationary pressures are transitory for longer or not.

In June β€œrisk-on” strategies did generally well, and based on a small sample of approximately 500 funds, we can see that Risk Premia, followed by Equity Long Short and Risk Parity funds are occupying the top three slots. Follow the links below to see how the indices have done year-to-date.

Risk Premia4.3%
Equity LS3.4%
Risk Parity3.3%
Event Driven1.4%
Market Neutral1.0%
CTA0.9%
Crypto-1.0%
Fixed Income-1.3%
June-2023 Estimated Index Performance – NilssonHedge indices

June had strong returns for equities (Major US Indices ~+6.5%) as retail investors continued to shift assets into risk strategies. This was reflected in the strong performance of the Risk Parity and Equity Long/Short strategy. Crypto strategies, usually a beneficiary of strong equity markets, did not follow the market closely. Crypto managers are still outperforming on a year-to-date basis. For the more traditional indices, Risk Parity is making a strong comeback as betas are making a comeback.

CTAs had a small gain, driven by a long-ish exposure to equities, and short duration. Views that generally worked in June. Trend-based Commodity positions likely detracted. While our observations are based on daily indices, these may deviate from the complete monthly index.

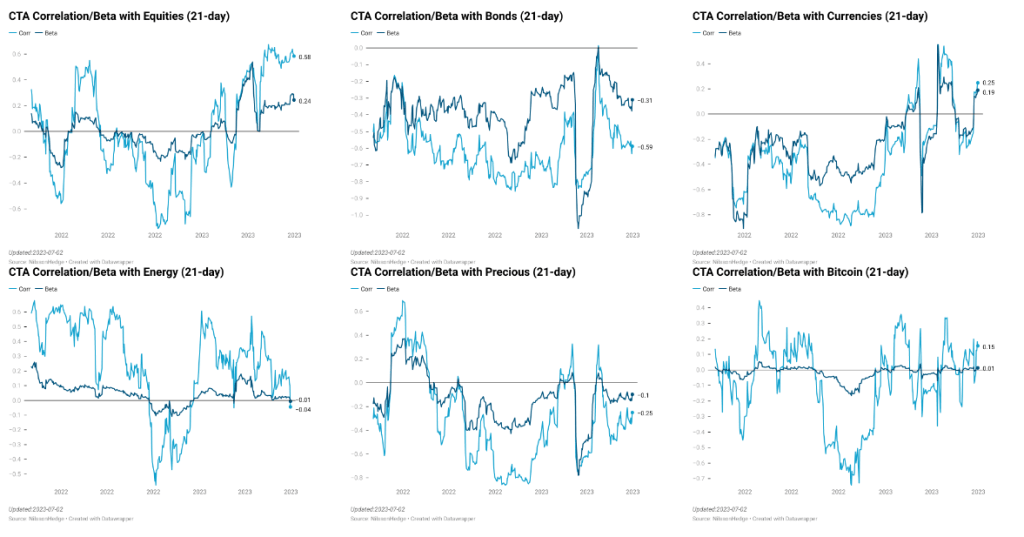
Correlation for CTA

Of note is that within the Equity Long/Short community, we see beta exposure to the equity markets. From the low reading a year ago, these values have now gradually increased towards the more steady-state value of about 0.5. This is an observation that we do not observe for Market Neutral or Event Driven strategies.

As usual, our databases are updated with the latest estimates. If you are a Canadian or US-based investor, looking for an intuitive portfolio management construction tool, we would like to highlight the launch of one of our data partners’ applications. SigmaSandbox is offering a 60-day free trial.

We also fixed a minor WordPress issue that occasionally gave the impression that this update was a paid update. Fixing Twitter is beyond our competence though.

  •  

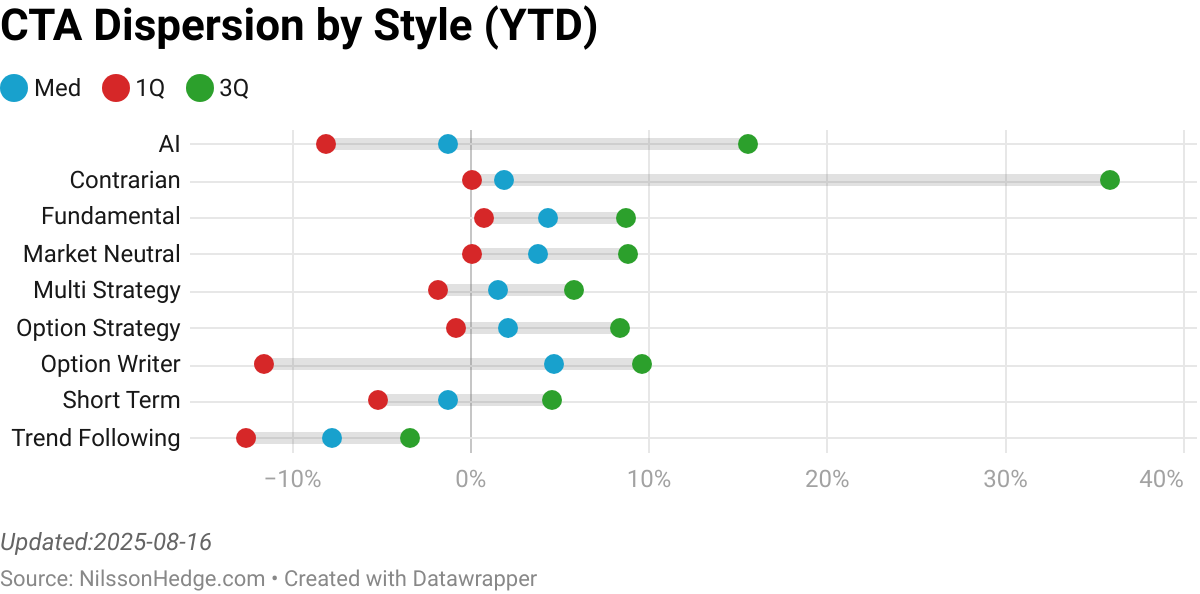
Dispersion – Style Matters

We like Dispersion, it tells us if an environment is a suitable environment for the strategy, or if you need to be skilled to pick funds or allocate to specific systems and portfolio managers.

In the current environment we are seeing lower manager dispersion, and picking the right style is more important than selecting the best manager within a group. This can of course change rapidly, if positions and markets start to diverge.

There are a few interesting observations, which is largely reflective of the May-23 trading environment.

  • Crypto Managers are trading within a tight range, one of the tightest dispersion on record. While this is generally the most volatile strategy class, we are two standard deviations below the mean, in terms of Dispersion. This is an environment where a variety of strategies largely behave the same.
  • Crypto Manager dispersion is almost on par with traditional Liquid Alternatives. We have also observed lower and lower volatility across Crypto Strategies.
  • Event Driven and Risk Premia, are two strategies that are exhibiting slightly elevated levels of Dispersion. These two strategies had negative results during May-23.
  • CTAs are still slightly below average dispersion, but have recently started to build positions and we see dispersion increasing slightly.

CTAs are back to positive numbers, on average. But as usual, the average hides a lot of dispersion. Trend following is still negative, on average, and is the strategy group that has struggled to generate positive results year-to-date. Most other strategies are slightly positive for the year.

Looking on a year-to-date basis, you probably made money as a Hedge Fund allocator. Event Driven, is one of the few hedge fund strategies that are struggling.

You can follow continously updated Dispersion statistics here.

  •  

Best’n’Worst – May 2023

May 2023 was a month with weak beta returns, as global equities and bonds declined modestly. Central banks settled into the transitory for longer narrative and while the FED ultimately paused in June, other central banks kept pushing rates higher. Trend Followers continued to recover some of their losses, while Crypto and Risk Parity strategies ended up at the bottom.

As per our usual programming, we have collected slightly more than 80% of the managers that we expect to report for May (1811 strategies, of which 534 Commodity Trading Advisors). We can have reasonable assurance that we are giving a solid representation of the managers that had the best of times and the managers that had the worst of times. From a performance perspective. Odey’s funds did definitively not have the best of times, but that has yet to impact their performance.

CTA

Soaring Pelican : Overnight Advantage  :  15.97% [0.90]<br> Gresham Investment Management : GreshamQuant Acar  :  8.78% [1191.00]<br> P/E Investments : FX Strategy - Aggressive  :  8.63% [12000.00]<br> Mulvaney Capital Management : Global Diversified Program  :  8.49% [267.00]<br> Astute Capital Group : Pulse Program  :  7.87% [1.40]<br> Rotella Capital Management : QDeck Tactical Commodity  :  -9.67% [0.00]<br> AIS Capital Management : MAAP 2-4X  :  -12.99% [15.60]<br> FX NOR AS : Global Makro  :  -13.44% [0.00]<br> AIS Capital Management : MAAP 3-6X  :  -19.11% [53.87]<br> Vigo Capital : Fund  :  -37.50% [0.51]<br> >


Skylar Capital Management : Natural Gas And Power  :  7.79% [731.83]<br> Soaring Pelican : Overnight Advantage  :  15.97% [0.90]<br> Mulvaney Capital Management : Global Diversified Program  :  8.49% [267.00]<br> ABR : Enhanced Short Volatility  :  4.57% [2.93]<br> Equanimity Advisors : Master Fund  :  2.20% [27.06]<br> FX NOR AS : Global Makro  :  -13.44% [0.00]<br> ESI : Macro LS  :  -3.30% [2.00]<br> Superfund Capital Management : Green SPC 2x  :  -0.71% [2.72]<br> Moddco Capital Associates : MCA  :  2.49% [0.10]<br> Vigo Capital : Fund  :  -37.50% [0.51]<br> >


To explore the full list of CTAs and their rankings, including dynamic updates as new data becomes available, we invite you to visit our website at the Link provided.Β 

Market Neutral

Man GLG : GLG UK Absolute Value  :  3.70% [338.24]<br> BNP Theam : Quant Dispersion US  :  3.47% [119.63]<br> Aenaon Markets : Syncro Equities - Absolute Return  :  2.76% [2.00]<br> JPMorgan : JPMorgan Research Market Neutral  :  2.17% [0.00]<br> Man GLG : GLG Innovation Equity  :  1.82% [149.93]<br> KLP Kapitalforvaltning AS : KLP Alfa Global Energi  :  -2.22% [263.60]<br> Aphilion : Aphilion SIF  :  -2.46% [40.08]<br> PIMCO : PIMCO RAE Fundamental Advantage PLUS  :  -2.89% [0.00]<br> LGT Capital Partners : LGT Sustainable Equity Market  :  -3.02% [100.11]<br> Maverick : QM Neutral (GS)  :  -5.01% [360.76]<br> >

Zest : North America Pairs Trading  :  -0.62% [38.92]<br> Exane : Ceres  :  -0.83% [193.44]<br> Blackrock : Asia-Pacific Diversified  :  1.49% [32.78]<br> Gondor Capital : Gondor Partners Ltd  :  1.57% [9.70]<br> JPMorgan : JPMorgan Research Market Neutral  :  2.17% [0.00]<br> Aphilion : Aphilion SIF  :  -2.46% [40.08]<br> QQM Fund Management : QQM Equity Hedge  :  -0.87% [63.90]<br> RAM : Long Short European  :  -1.73% [154.93]<br> Maverick : QM Neutral (GS)  :  -5.01% [360.76]<br> PIMCO : PIMCO RAE Fundamental Advantage PLUS  :  -2.89% [0.00]<br> >

To explore our extensive list of Market Neutral funds and their dynamic rankings, we invite you to visit our website at the link provided here.Β 

Equity Long/Short

Shannon River : Long/Short Technology (U Access)  :  7.84% [44.26]<br> Lucerne Capital Management : Nordic  :  7.79% [0.00]<br> Wellington : Technology (Franklin K2)  :  7.54% [19.17]<br> Sentat Asset Management : Thyra Hedge  :  6.35% [26.80]<br> RiverPark : RiverPark Long/Short Opportunity  :  6.22% [0.00]<br> Cederberg Capital : Greater China (Banor)  :  -8.91% [110.90]<br> Veritas : China  :  -9.06% [32.39]<br> JanusHenderson : Horizon China  :  -10.11% [60.75]<br> RAM Rational Asset Management : RAM ONE  :  -11.90% [54.10]<br> Accendo Capital : Accendo Capital  :  -12.76% [218.40]<br> >

HELSINKI CAPITAL PARTNERS : HCP Focus Fund  :  5.98% [10.80]<br> Pareto Asset Management AS : Pareto Total  :  1.22% [821.70]<br> RiverPark : RiverPark Long/Short Opportunity  :  6.22% [0.00]<br> Incline : Global Long Short  :  2.37% [8.99]<br> Shannon River : Long/Short Technology (U Access)  :  7.84% [44.26]<br> Pensum Asset Management : Global Opportunities  :  -7.98% [17.70]<br> Veritas : China  :  -9.06% [32.39]<br> Finlabo : Dynamic US Equity  :  -5.04% [4.01]<br> Disciplined Alpha : U.S. Long Short  :  -6.18% [5.39]<br> Accendo Capital : Accendo Capital  :  -12.76% [218.40]<br> >

To explore our extensive Equity Long/Short list, with dynamic rankings, please see Link

Event Driven

Neuberger Berman : Distressed Debt Extended Life Shares  :  2.93% [0.00]<br> Formue Nord : Formue Nord Markedsneutral AS  :  1.51% [39.20]<br> Formue Nord : Fokus  :  0.83% [68.50]<br> Advent Global : Advent Global Partners (ML)  :  0.81% [156.49]<br> Hadron : Alpha Select  :  0.75% [6.27]<br> Gabelli : Mergers & Acquisitions  :  -3.89% [0.00]<br> KiteLake : Event Driven  :  -4.28% [605.49]<br> Cheyne : Cheyne Arbitrage (U Access)  :  -5.69% [81.10]<br> Alpine : Merger Arbitrage  :  -5.83% [224.84]<br> Odey : Special Situations  :  -6.56% [76.86]<br> >

Portland : Hill Catalyst Driven  :  -3.10% [26.20]<br> Hadron : Alpha Select  :  0.75% [6.27]<br> Neuberger Berman : Distressed Debt Global Shares  :  -1.23% [0.00]<br> Formue Nord : Formue Nord Markedsneutral AS  :  1.51% [39.20]<br> CIAM : Satellite Event Driven  :  -3.63% [13.42]<br> Odey : Special Situations  :  -6.56% [76.86]<br> KiteLake : Event Driven  :  -4.28% [605.49]<br> Abrax : Merger Arbitrage  :  -3.72% [30.95]<br> Cheyne : Cheyne Arbitrage (U Access)  :  -5.69% [81.10]<br> Alpine : Merger Arbitrage  :  -5.83% [224.84]<br> >

To explore our extensive Event-Driven list, with dynamic rankings, please see Link

Fixed Income

KBC : Bonds Convertibles  :  2.34% [0.00]<br> Ironshield : Credit Fund  :  2.26% [66.69]<br> RBC Bluebay : Emerging Market Unconstrained Bond  :  1.81% [389.69]<br> Axiom : European Financial Debt Fund Limited  :  1.79% [0.00]<br> Polar : Capital Global Absolute  :  1.76% [111.35]<br> Secured : Secured Income Fund Plc  :  -4.34% [0.00]<br> VPC : Specialty Lending Investments  :  -4.51% [0.00]<br> CABA Capital : CABA Hedge  :  -4.75% [130.00]<br> CABA Capital : CABA Flex  :  -4.76% [18.50]<br> GCP : Asset Backed Income  :  -6.32% [0.00]<br> >

Danske Bank Asset Management : Danske Invest Fixed Income Global Value  :  0.53% [825.60]<br> Capital Four Management : Capital Four Structured Credit Opportunities Fund  :  1.44% [81.60]<br> Blackstone : Loan Financing  :  -0.00% [0.00]<br> Selwood : Market Neutral Credit (Alma)  :  0.92% [122.32]<br> Vontobel Asset Management : Twenty Four Income Fund  :  0.50% [0.00]<br> VPC : Specialty Lending Investments  :  -4.51% [0.00]<br> EJF Investments : Event Driven  :  -0.09% [0.00]<br> Nordea Asset Management : European Rates Opportunity  :  -1.84% [373.20]<br> GCP : Asset Backed Income  :  -6.32% [0.00]<br> Highbridge : Credit Fund  :  0.00% [0.00]<br> >

To explore our extensive Fixed Income list, with dynamic rankings, please see Link

Risk Premia

Catalyst Funds : Systematic Alpha  :  4.44% [0.00]<br> Nomura : Fixed Income Risk Premia  :  3.09% [1.35]<br> Capital Fund Management : Diversified  :  2.20% [79.10]<br> Schroders : Isf Alternative Risk  :  1.85% [408.55]<br> Future Value Capital : Equity Dispersion  :  1.70% [114.00]<br> Nordea Asset Management : Nordea 1  Alpha 10 MA Fund  :  -2.89% [5442.00]<br> Nordea Asset Management : Nordea 1  Alpha 15 MA Fund  :  -4.53% [5325.60]<br> AQR Capital Management : Style Premia  :  -4.77% [337.18]<br> AQR Capital Management : Style Premia Alternative  :  -4.98% [0.00]<br> Quadriga : Stable Return  :  -7.81% [4.95]<br> >

Catalyst Funds : Systematic Alpha  :  4.44% [0.00]<br> Neuberger Berman : US Equity Put Write  :  1.37% [517.43]<br> Blackrock : Style Advantage  :  -0.21% [95.06]<br> Quadriga : Stable Return  :  -7.81% [4.95]<br> Allianz Global Investors : Volatility Strategy  :  0.89% [542.90]<br> AQR Capital Management : Alternative Risk Premia  :  -2.31% [0.00]<br> AQR Capital Management : Style Premia Alternative  :  -4.98% [0.00]<br> BNP Theam : Absolute Alpha  :  0.47% [13.96]<br> Credit Suisse Multialternative : Credit Suisse Multialternative  :  -1.71% [0.00]<br> BNP Theam : Quant Equity  :  -1.72% [19.30]<br> >

To explore our extensive Risk Premia list, with dynamic rankings, please see Link

Crypto

Hole in One Josch : 554BC485571344C890D16DC3BE4460  :  63.78% [0.00]<br> EdgeHill Investment Group : Prometheus Cryptocurrency  :  10.03% [86.00]<br> LibertyRoad Capital : BTC Negative Gamma Strategy  :  6.63% [0.00]<br> LibertyRoad Capital : Covered Call BTC  :  5.50% [0.00]<br> LibertyRoad Capital : BTC Diversified Alpha Strategy  :  4.89% [0.00]<br> CryptoGen : CRYPTOGEN  :  -18.80% [0.00]<br> Mitja Kokovnik : KICKSTART  :  -18.94% [0.00]<br> CryptoIVPSI : CRYPTOIVPSI  :  -19.45% [0.00]<br> Rocket one : MELCHORCRYPTOPORTFOLIO  :  -19.49% [0.00]<br> Future Chain Index : Future Chain Index  :  -36.40% [0.00]<br> >

Hole in One Josch : 554BC485571344C890D16DC3BE4460  :  63.78% [0.00]<br> TheCryptoOwl Strategy : THECRYPTOOWL  :  -4.81% [0.00]<br> Crush : CCC Crush Crypto Core  :  2.09% [0.00]<br> Amigo Feliz II : AMIGOFELIZII  :  -1.44% [0.00]<br> Princess : BOSTI22  :  -5.53% [0.00]<br> LibertyRoad Capital : Covered Call ETH  :  1.63% [0.00]<br> LibertyRoad Capital : ETH Negative Gamma Strategy  :  -1.56% [0.00]<br> Sustainable Crypto Selection : SCS Sustainable Crypto Selection  :  -6.20% [0.00]<br> Low Fees Top Fundamentals : Low Fees Top Fundamentals  :  -9.71% [0.00]<br> INVESTMOX : INVESTMOXROLLERCOASTER INVESTMOX Rollercoaster  :  -9.87% [0.00]<br> >

To explore our extensive Crypto Strategy list, with dynamic rankings, please see Link

It is important to note that our rankings are not filtered for Asset Under Management, meaning that funds of any size can be included in our analysis. Our rankings are based solely on a simple return metric without adjusting for volatility, so some funds may have a higher risk profile than others.

To be included in our rankings, funds must have reported returns for the current reporting month. This means that we may not have data on all funds in a given category, and our rankings should be considered within the context of the funds that we do have information on.

Past performance is not indicative of future results.

  •  

Crypto Trading – Making a silent comeback?

Crypto Hedge funds had their day in the sun during the feverish Covid period in 2020 and 2021. The strong beta results generated a remarkable number of managers starting to market in 2021 and 2022. Our Crypto Index had two exceptional years in 20/21. Despite a rough recent period, we are continuing to see additional funds coming to the market.

In 2023, the index has bounced back, partly driven by a strong comeback for Tech. Lately, the indices have decoupled from the Nasdaq index, and May and June will likely have taken some oomph out of the results, on the back of increased regulatory scrutiny.

The NilssonHedge Crypto Trading is up 25% in 2023.

In hindsight, being directional throughout last year, was the wrong call for a market dominated by a significant drawdown. That said, even after exchange failures we continue to see many new strategies. This time around, we are seeing managers with more sophisticated approaches to markets, various arbitrage strategies, yield farming, and short-term trading.

Thus, Crypto Trading is not dead, but managers are much more sophisticated today than they used to be. Even the Long-Biased managers have, maybe by necessity, added hedging strategies to avoid rapid declines.

Crypto Traders – Numbers

Number of Crypto Trading in the NilssonHedge Database, In June 2023 we tracked close to 1000 strategies.

Looking across the NilssonHedge Crypto Hedge Fund database, we are thirteen manager shy of tracking one thousand strategies. Currently, the number of managers tracked is 987 and most of the new managers are non-directional (although a majority of the existing strategies are still highly directional).

We believe that our database is one of the larger databases focused on Trading Strategies. We typically do not have a large amount of Venture Capitalist strategies in the database.

Pre-2022, most of the strategies that we tracked had a HODL approach, buy Bitcoin or any portfolio of cryptocurrencies and hold on for dear life. And a lot of them discontinued return reporting during 2022 as it is difficult to entice investors into strategies with significant drawdowns. Today, we are seeing managers deploying a range of market-neutral strategies, generally a more sophisticated approach.

New Index – Market-Neutral Crypto

To reflect this reality, we will launch a subset of our Crypto Index focused on more market-neutral strategies. We expect to have done the research and will launch the index at the end of the month. This will generally have much lower volatility and be significantly less correlated to Crypto Beta.

Market Neutral strategies will impose significant Due Diligence hurdles. Multiple exchanges and an additional set of instruments are two of the many hurdles that may make these strategies harder to allocate to. On top of that, the underlying strategy is now much more complex than simply holding tokens.

Clouds on the Horizon?

One of the indicators that we track is the number of Sophisticated β€œretail” strategies (some of them have 20+ in aum), and here we are yet to see an improvement in the sentiment. That probably means that the counterparty for any Crypto trader has switched from a sentiment-driven trader to a likely institutional, market-inefficiency trader.

Coinbase recently made a substantial report on how to think about Crypto (partly using our data to illustrate correlations). The report can be found here: https://www.coinbase.com/institutional/research-insights/research/market-intelligence/asset-allocators-guide-to-crypto-hedge-funds

  •  

Flash Report – May 2023

Based on preliminary reporting by more than 1,300 hedge funds and liquid alternative strategies, May turned out to be a tricky month for many strategies. While we do not yet have the full picture of all strategies, we can infer a few conclusions regarding what worked and what did not work in May 2023. Despite flat to positive equity markets many strategies recorded losses.

On the positive side, CTAs seem to have done relatively well and have printed a modestly positive result of 0.5% taking the strategy back to flat returns, and recovering some parts of the March drawdown.

IndexMayAprilYTD
Crypto-6.2%-0.7%25%
CTA0.5%0.9%0%
Equity LS-0.9%0.2%1%
Event Driven-1.9%0.2%-2%
Fixed Income-0.3%0.3%1%
Market Neutral-0.1%0.1%1%
Risk Parity-1.0%0.2%4%
Risk Premia-0.6%1.0%1%

We observe modest to negative returns from equity-dependent/adjacent strategies. Event-Driven and Risk Parity strategies suffered the most during a month that was characterized by a positive, but largely range-bound equity market and falling bond prices. [Directional] Crypto strategies had a negative month but are still the best-performing strategy on a year-to-date basis with a result of +25%.

IndexMayAprilYTD
CTA Commodities-0.4%0.6%1%
CTA Commodities Disc-0.8%0.3%0%
CTA Disc Macro0.3%-0.3%0%
CTA Discretionary0.0%0.2%1%
CTA Fund of Funds0.9%2.1%1%
CTA Quant0.4%0.3%1%
CTA Short Term0.8%0.5%1%
CTA Systematic0.6%1.1%0%
CTA Systematic Momentum1.2%2.0%-3%

Diving deeper into the CTA sub-sector, we note that Trend Following managers returned 1.2%, taking the YTD result to negative 3%. Commodity managers, where in particular discretionary managers faced difficult conditions, lost 80bp, and are flat for the year.

We would like to draw attention to the diversifying index, the NilssonHedge Quant CTA Index, an index consisting largely of non-trend following strategies. Consisting of more than 140 managers there is ample room to find more niche strategies. Not all of them are crowded nor are they expected to deliver strong performance. But, diversification within the group has created an index that has done well to their larger peers in 2023.

While the daily indices contain a fair amount of noise, we can highlight that CTAs have managed to recover some of the Fixed Income related drawdowns that took place in March. However, the strategy is behind most of the other Liquid Alternative strategies on a year-to-date basis.

To check out how individual strategies did, the NilssonReport offers some quick insights.

Thanks for your support.

  •  

The NilssonHedge Benchmark Report

Behind the scenes, we have been working hard to create a unified, standardized, and informative Factsheet. The Factsheet allows you to inspect strategies, and gauge the competitiveness of a particular manager, compared to peers and benchmarks. This report is available on a bespoke basis and is currently only available upon request.

The report comprises five pages, the first one shows the manager compared to the NilssonHedge indices, including a number of stylized statistics. We volatility adjust the indices to the manager’s volatility.

Here we note that some of the NH Indices have large volatility compression, as they are highly diversified. About 2/3rds of the individual manager’s volatility is diversified away (the median manager has approximately 10% annualized volatility and our index has a volatility of about 3.5-4.0%). Thus, the volatility-adjusted index is hard to beat. Pages three and four will alleviate some of the problems with risk-adjusted index returns.

The second page plots various risk statistics:

  • The Drawdown chart, compared to the relevant benchmark. We highlight the deepest drawdown and also the longest recovery period.
  • Annualized Risk (here we take a shortcut and use the standard deviation of returns). Here also compared to the main style index.
  • The third chart shows a rolling 36-month correlation against a set of indices. We are currently experimenting with the number of benchmarks to include.

On pages three and four, we compare the manager to a broad peer group. Here we calculate every the VAMI of each and single competitor in their style group. At every point, we find the 25th and 75th percentile cutoff. This removes the volatility compression that can be found in indices and may thus be a better way to assess the quality of any single manager.

In addition to calculating the dispersion, we present the more traditional box plots. These are periodic returns and give any manager or allocator a quick way to understand the market environment a strategy performs strongly or poorly.

The fourth page contains volatility-rescaled data and may give different results for managers that are either more or less volatile than the median. This is a way to highlight the risk-adjusted returns. We also present the result of the highest correlated peers above a dynamic AUM threshold.

The sample factsheet can be downloaded below. Please note the disclaimer on the fifth page.

  •  

Best’n’Worst April-2023

April was an interesting month, with some Trend Following CTA making strong returns. Some Crypto managers have staged a strong comeback in 2023, but the majority of them are still in a severe drawdown. We also note strong performance from equity beta-driven strategies, with some nice results for Equity Long/Short strategies.

Based on the most recent return data that we have available, we can provide a comprehensive overview of the top-performing and worst-performing strategies for each category, taking into account both monthly and yearly results. Our analysis is based on proprietary composite data streams that we have compiled, but we must note that there is always the possibility of errors or inaccuracies in our calculations.

CTA

Soaring Pelican : Overnight Advantage  :  21.61% [0.90]<br> Mulvaney Capital Management : Global Diversified Program  :  15.27% [271.00]<br> ABR : Enhanced Short Volatility  :  14.17% [2.93]<br> SMN Investment Services : Structural Alpha Trend  :  13.64% [41.01]<br> EMC Capital Advisors : Tactical Commodity  :  11.94% [11.90]<br> Rosetta Analytics : RL Carbon  :  -5.66% [8.70]<br> QDRA Pty : Dynamic Macro  :  -6.18% [1.98]<br> Schindler Capital Management : Institutional Dairy Advantage  :  -6.59% [2.01]<br> Opus Futures : Macro Monitor Program  :  -6.66% [18.83]<br> Bensboro Advisors : Seasonal Futures Fund  :  -6.84% [4.01]<br> >


Skylar Capital Management : Natural Gas And Power  :  5.72% [758.62]<br> Soaring Pelican : Overnight Advantage  :  21.61% [0.90]<br> ABR : Enhanced Short Volatility  :  14.17% [2.93]<br> Numberline Capital Partners : Numberline  :  0.56% [0.73]<br> Mulvaney Capital Management : Global Diversified Program  :  15.27% [271.00]<br> Superfund Capital Management : Green SPC 1x  :  -1.97% [10.36]<br> Superfund Capital Management : Green Silver SICAV  :  2.30% [65.42]<br> Superfund Capital Management : Green SPC 1.5x  :  -1.41% [65.42]<br> Superfund Capital Management : Green SPC 2x  :  -1.70% [1.50]<br> Moddco Capital Associates : MCA  :  0.72% [0.07]<br> >

To explore the full list of CTAs and their rankings, including dynamic updates as new data becomes available, we invite you to visit our website using this Link. Here, you will find a wealth of information on the performance of different CTAs across a range of markets and strategies, as well as insights and analysis from our team of experts in the field.Β 

Market Neutral

Market Neutral is a popular strategy among investors due to its low volatility and steady returns over time. Unlike other strategies that may produce large gains or losses in a short period, Market Neutral tends to accumulate returns gradually over time. This makes it an attractive option for those looking to achieve steady, long-term growth without taking on excessive risk.

Osmosis : More World Sustainable  :  3.47% [33.48]<br> Cognios : Cognios Market Neutral Large Cap  :  3.10% [0.00]<br> MarshallWace : MW Tops Market Neutral  :  2.67% [1243.59]<br> Blackrock : Asia-Pacific Diversified  :  2.22% [32.78]<br> Crossmark Steward : Equity MN Instl  :  2.01% [0.00]<br> Pictet Asset Management : Agora  :  -2.24% [0.00]<br> Maverick : QM Neutral (GS)  :  -2.29% [360.76]<br> PIMCO : PIMCO RAE Fundamental Advantage PLUS  :  -2.40% [0.00]<br> DNCA Invest : Miuri  :  -2.55% [309.05]<br> Aphilion : Aphilion SIF  :  -3.23% [41.51]<br> >

Zest : North America Pairs Trading  :  1.40% [38.92]<br> Exane : Ceres  :  0.20% [193.44]<br> Blackrock : Asia-Pacific Diversified  :  2.22% [32.78]<br> Osmosis : More World Sustainable  :  3.47% [33.48]<br> Gondor Capital : Gondor Partners Ltd  :  1.69% [9.70]<br> Fulcrum Asset Management : Thematic Equity Market  :  -0.80% [400.95]<br> JanusHenderson : Global Equity Market Neutral  :  -0.66% [73.40]<br> RAM : Long Short European  :  -1.62% [154.93]<br> QQM Fund Management : QQM Equity Hedge  :  -0.90% [63.90]<br> PIMCO : PIMCO RAE Fundamental Advantage PLUS  :  -2.40% [0.00]<br> >

To explore our extensive list of Market Neutral funds and their dynamic rankings, we invite you to visit our website at the link provided here. Here, you will find a wealth of information on the performance of different funds, as well as insights and analysis from our team of experts in the field. Whether you are a seasoned investor or just starting out, our Market Neutral rankings can provide valuable guidance and help you make more informed investment decisions.

Equity Long/Short

Equity Long/Short strategies are investment approaches that involve taking both long and short positions in equities in order to potentially profit from the performance of individual stocks or the broader equity markets.Β 

Borea Asset Management AS : Borea Utbytte  :  6.61% [193.20]<br> Pareto Asset Management AS : Pareto Nordic Omega  :  5.30% [14.70]<br> Pareto Asset Management AS : Pareto Nordic Alpha B  :  4.53% [17.20]<br> Pareto Asset Management AS : Pareto Total  :  4.48% [809.40]<br> Nuance : Nuance Concentrated Value L-S  :  4.42% [0.00]<br> BNP : Environmental Absolute Return  :  -5.77% [37.79]<br> JanusHenderson : Horizon China  :  -5.81% [60.75]<br> Veritas : China  :  -6.47% [32.39]<br> Cederberg Capital : Greater China (Banor)  :  -6.96% [110.90]<br> Accendo Capital : Accendo Capital  :  -12.81% [249.60]<br> >

HELSINKI CAPITAL PARTNERS : HCP Focus Fund  :  0.35% [10.80]<br> Pareto Asset Management AS : Pareto Total  :  4.48% [809.40]<br> Incline : Global Long Short  :  4.16% [8.99]<br> Pareto Asset Management AS : Pareto Nordic Omega  :  5.30% [14.70]<br> Pareto Asset Management AS : Pareto Nordic Alpha B  :  4.53% [17.20]<br> Norron : Norron Select  :  -1.51% [47.10]<br> Forester : Forester Value  :  0.34% [0.00]<br> Finlabo : Dynamic US Equity  :  -2.06% [4.01]<br> Disciplined Alpha : U.S. Long Short  :  0.68% [5.39]<br> Accendo Capital : Accendo Capital  :  -12.81% [249.60]<br> >

To explore our extensive Equity Long/Short list, with dynamic rankings, please see Link

Event Driven

Event-Driven managers are commonly exposed to various arbitrage/spread risks related to specialist situations securities. Managers with concentrated exposure tend to end up on this list and exploring the drivers of out or underperformance may yield insights.

Neuberger Berman : Distressed Debt Extended Life Shares  :  10.10% [0.00]<br> Third Point : Third Point  :  4.32% [0.00]<br> Neuberger Berman : Distressed Debt Global Shares  :  2.53% [0.00]<br> Oceanwood : Opportunities  :  2.29% [131.44]<br> PrivilEdge : Amber Event Europe  :  2.01% [145.63]<br> Formue Nord : Fokus  :  -0.81% [72.50]<br> Gabelli : Mergers & Acquisitions  :  -0.94% [0.00]<br> York : Asian Event (Lumyna)  :  -1.79% [126.68]<br> Pictet : Agora  :  -2.15% [398.44]<br> Abrax : Merger Arbitrage  :  -3.35% [30.95]<br> >

Neuberger Berman : Distressed Debt Extended Life Shares  :  10.10% [0.00]<br> Portland : Hill Catalyst Driven  :  0.90% [26.20]<br> CIAM : Satellite Event Driven  :  0.87% [13.42]<br> RBC BlueBay : Event Driven Credit Fund (EDCF)  :  0.23% [0.00]<br> Hadron : Alpha Select  :  -0.04% [6.27]<br> Oceanwood : Opportunities  :  2.29% [131.44]<br> Cheyne : Cheyne Arbitrage (U Access)  :  -0.14% [81.10]<br> Alpine : Merger Arbitrage  :  -0.59% [224.84]<br> Abrax : Merger Arbitrage  :  -3.35% [30.95]<br> Third Point : Third Point  :  4.32% [0.00]<br> >

To explore our extensive Event-Driven list, with dynamic rankings, please see Link

Fixed Income

Similar to Equity Long/Short managers, Fixed Income managers are typically influenced by the underlying market conditions. However, for this list, the focus is on managers who are sensitive to a specific subsector of the fixed-income market, particularly those engaged in the lowest part of the capital structure.

Highbridge : Credit Fund  :  16.60% [0.00]<br> GCP : Asset Backed Income  :  7.53% [0.00]<br> VPC : Specialty Lending Investments  :  5.00% [0.00]<br> CABA Capital : CABA Flex  :  4.19% [18.50]<br> Borea Asset Management AS : Borea Kreditt  :  4.09% [54.80]<br> Allianz Global Investors : Fixed Income Macro  :  -1.42% [85.93]<br> KBC : Bonds Convertibles  :  -2.53% [0.00]<br> Chenavari : Toro Income Fund  :  -2.71% [0.00]<br> Marble Point : Loan Financing  :  -3.63% [0.00]<br> Blackstone : Loan Financing  :  -4.76% [0.00]<br> >

Highbridge : Credit Fund  :  16.60% [0.00]<br> Danske Bank Asset Management : Danske Invest Fixed Income Global Value  :  2.47% [812.40]<br> RBC BlueBay : Global Securitized Credit Opportunities Fund (CSCOF)  :  1.23% [0.00]<br> Danske Bank Asset Management : Danske Invest Fixed Income Relative Value  :  3.23% [412.50]<br> Capital Four Management : Capital Four Structured Credit Opportunities Fund  :  1.27% [78.00]<br> CQS : New City High Yield Fund  :  2.14% [0.00]<br> Axiom : Long Short Credit  :  -1.07% [12.40]<br> Nordea Asset Management : European Rates Opportunity  :  -0.49% [373.20]<br> GCP : Asset Backed Income  :  7.53% [0.00]<br> EJF Investments : Event Driven  :  -0.78% [0.00]<br> >

To explore our extensive Fixed Income list, with dynamic rankings, please see Link

Risk Premia

Risk Premia managers are commonly implemented well-explored and researched systematic strategies. These may be viewed as a general proxy for Hedge Fund exposure. Performance of specific factors may reveal differences and similarities to your own portfolio. To explore our extensive Risk Premia list, with dynamic rankings, please see Link

Nordea Asset Management : Nordea 1  Alpha 15 MA Fund  :  3.41% [5325.60]<br> Catalyst Funds : Systematic Alpha  :  3.05% [0.00]<br> Future Value Capital : Equity Dispersion  :  2.73% [114.00]<br> Allspring : Alternative Risk Premia  :  2.67% [29.86]<br> AQR Capital Management : Style Premia Alternative  :  2.57% [0.00]<br> Allianz Global Investors : Multi Asset Risk Premia  :  -0.60% [66.05]<br> Credit Suisse Multialternative : Credit Suisse Multialternative  :  -0.67% [0.00]<br> Man AHL : Alternative Style Premia  :  -0.79% [306.33]<br> Lumyna : Merrill Lynch MCLX  :  -1.23% [277.30]<br> BNP Theam : Quant Equity  :  -2.25% [19.30]<br> >

Quadriga : Stable Return  :  -0.54% [4.95]<br> Catalyst Funds : Systematic Alpha  :  3.05% [0.00]<br> Blackrock : Style Advantage  :  0.74% [95.06]<br> Neuberger Berman : US Equity Put Write  :  1.95% [517.43]<br> Nordea Asset Management : Nordea 1  Alpha 15 MA Fund  :  3.41% [5325.60]<br> Man AHL : Alternative Style Premia  :  -0.79% [306.33]<br> Capital Fund Management : Diversified  :  0.02% [79.10]<br> Credit Suisse Multialternative : Credit Suisse Multialternative  :  -0.67% [0.00]<br> BNP Theam : Absolute Alpha  :  -0.16% [13.96]<br> BNP Theam : Quant Equity  :  -2.25% [19.30]<br> >

Crypto

As usual Crypto tends to have the most volatile numbers. Returns tend to be double-digit (or even triple-digit for the best funds and for obvious reasons rarely more than double digits for the worst ones), simply due to the volatility of the asset class. To explore our extensive Crypto Strategy list, with dynamic rankings, please see Link

Amigo Feliz II : AMIGOFELIZII  :  38.65% [0.00]<br> TheFly The One : THEDGE  :  17.63% [0.00]<br> Princess : BOSTI22  :  16.95% [0.00]<br> Hole in One Josch : 554BC485571344C890D16DC3BE4460  :  16.28% [0.00]<br> Money4me : MONEY4ME  :  14.42% [0.00]<br> ETRADE : ETRADE  :  -12.66% [0.00]<br> Mitja Kokovnik : KICKSTART  :  -13.95% [0.00]<br> Crush : CCC Crush Crypto Core  :  -15.73% [0.00]<br> CryptoGen : CRYPTOGEN  :  -16.93% [0.00]<br> AbacusBlock Index : ABACUSBLOCK  :  -34.03% [0.00]<br> >

Β 

TheCryptoOwl Strategy : THECRYPTOOWL  :  2.16% [0.00]<br> Hole in One Josch : 554BC485571344C890D16DC3BE4460  :  16.28% [0.00]<br> Crush : CCC Crush Crypto Core  :  -15.73% [0.00]<br> Amigo Feliz II : AMIGOFELIZII  :  38.65% [0.00]<br> Princess : BOSTI22  :  16.95% [0.00]<br> Prophet Priest and King : KINGOFALL  :  -7.52% [0.00]<br> Crypto Asset Management : Strategy One  :  -4.10% [0.03]<br> Sustainable Crypto Selection : SCS Sustainable Crypto Selection  :  -1.12% [0.00]<br> INVESTMOX : INVESTMOXROLLERCOASTER INVESTMOX Rollercoaster  :  1.98% [0.00]<br> Low Fees Top Fundamentals : Low Fees Top Fundamentals  :  1.73% [0.00]<br> >

Past performance is not indicative of future results.

It is important to note that our rankings are not filtered for Asset Under Management, meaning that funds of any size can be included in our analysis. Our rankings are based solely on a simple return metric without adjusting for volatility, so some funds may have a higher risk profile than others.

To be included in our rankings, funds must have reported returns for the current reporting month. This means that we may not have data on all funds in a given category, and our rankings should be considered within the context of the funds that we do have information on.

Overall, our analysis provides a useful starting point for investors who are looking to compare and evaluate different investment strategies. It is important to keep in mind that no single metric or ranking can capture all of the nuances and complexities of the investment landscape, and investors should conduct their due diligence and consult with financial professionals before making any investment decisions.

Β 

  •  

Hedge Fund Indices – To Revise or Not To Revise

As we probably have told you countless times, we are providing a range of specialized Hedge Fund indices. These are useful for investors that need to benchmark managers. And for managers to gauge how they are doing compared to their average competitor. Some of our indices go back to the inception of the database, while others are more recent innovations.

The construction method is the same across all of our indices, we use our own proprietary classification methodology, to sort through a wide variety of strategies. We slice and dice the numbers to arrive at a set of interesting observations. What is particularly unique about the way we construct the indices, is that they are forgiving and allow managers to be re-included if they restart reporting.

If a manager temporarily stops submitting data, and then at some later point restarts reporting, we update our historical records. While this prevents the indices from being investable, the flipside is that they may be somewhat more representative than indices that do not revise historical data. But, we do not allow managers to backfill data as some indices out there do.

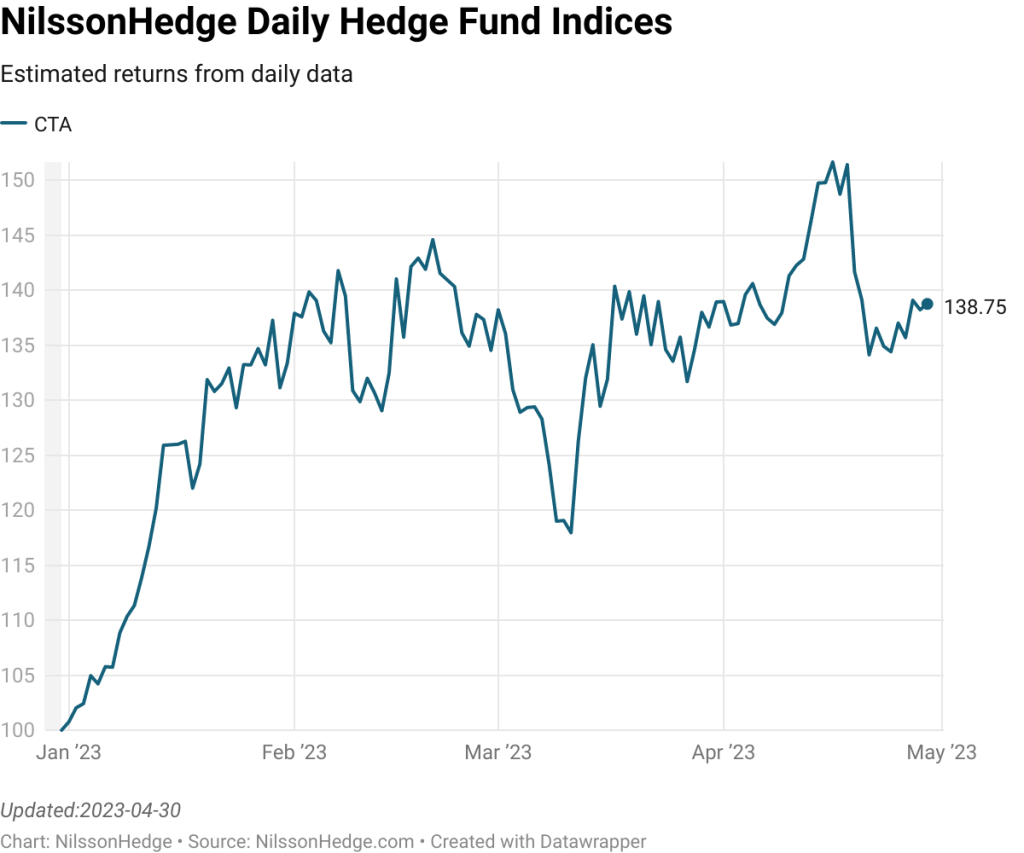
A proprietary feature in the datasets that we maintain is that they are time-stamped and we can track the evolution of a particular manager over time. In this case, we take a closer look at the NilssonHedge CTA index, our broadest representation of Managed Futures performance. In the chart above we plot how the cumulative returns looked at various dates.

A feature that is part of the design principles of the NilssonHedge Indices is that we are fully transparent about the constituents of each index, and also why they are included. Not only on a snapshot basis but since the inception of the index. This allows you to recreate the performance of the index and verify that our calculations are reasonable.

The indices are reconstituted annually, and managers are included as long as they are offering timely return reporting.

black internal hdd on black surface

Due to a change in how we stored and distributed the index data, we only started tracking our Index as of mid-2021 (a shoemaker's son always goes barefoot). We note that in general, looking at the data over time, there are relatively few revisions and they tend to take be neutral in terms of performance.

The other interpretation is that liquid strategies seldom have a need to substantially revise their numbers.

We take a look at our competitor's data and find that there have been substantial deviations over time. Here there is something else going on. Something was substantially altered in the performance data of the underlying strategies.

To their credit, there is only one major revision over the last five years, indicating that either a manager was excluded, or that a manager revised their track record substantially. The devil is in the detail, but Hedge Fund indices are hardly static and may change substantially over time.

We do not guarantee that this cannot happen to our indices, but we would at least be able to transparently point to which managers revised their numbers.

Thus, it is not only important to understand how a particular manager works and the individual drawbacks of a specific strategy. It is also important to understand how the benchmarks you are using are constructed, and how they may change and update over time. There are substantial revisions for some indices. Our databases allow for these types of research and may be a valuable tool when you are doing manager research.

Thanks for reading and supporting us. As a small favor, we recently disabled ads to give you a better experience.

  •  

Flash Report April-23

Like many other strategies, CTAs made a comeback after the tumultuous March. With the exception of a few hard-to-mark asset classes (Private Debt, Private Equity, and Infrastructure) CTA led the pack with a return of 1.1% (based on 46% reporting). This takes the loss for CTAs to do a minor 70bps for 2023. The NilssonHedge CTA index is showing slightly better numbers, but that is partly due to which managers have reported and which managers are included in the indices.

Thanks to a strong January, Crypto Strategies are still ahead of the pack with a 35% return for the year. Although not much has been happening since January. The NilssonHedge Crypto Index shows the impact of the difficult conditions throughout 2022 with a large turnover amongst the eligible managers.

In the CTA sector, on a year-to-date basis, strategies with a bend toward less focus on Trend Following have done better. We note that the median performance is marginally positive for other strategies.

For April, the story is more positive for the Trend Followers brethren and sistren with better numbers. So far, based on approximately half of the managers reporting data, more than 75% of them have positive numbers.

A close relative to the CTAs is the risk premia strategies. Occasionally these deploy trend-following strategies but typically access a much broader set of set strategies, including factor risk premia in equities and other asset classes.

The strategy had a big awakening during the Covid Crisis where β€œEquity Risk Premia” caused the strategy severe losses. During this time, several strategies shut down or retooled. The NH Risk Premia index is printing moderately positive numbers and has seen a good run over the last two years.

As per usual, our databases are updated and we have coverage of 1400+ strategies with April-23 numbers. Feel free to explore the free parts of the Database, for instance, the CTA Ranking report offers a quick way to assess how your Managed Futures portfolio is doing compared to peers.

Thanks for reading, and please feel to reach out to us, to see how we can help you with performance data.

  •  

Performance Preview April-23

CTAs managed to claw back returns and returned 1.5% for April. This is approximately a third of the exceptional speedy drawdown in March and is a sign that some positions are still in place for CTAs. The NilssonHedge CTA index is still down 2.1% for the year.

While Crypto Strategies has done the best on a year-to-date basis, most of the initial hoorah was in the initial part of the year, as the market renormalized. After that, we have had some spurts of performance, but the index has largely whipsawed.

In the wake of a relatively quick banking crisis (with the recent news with regards to β€œFirst Republic” it can be argued that it is still ongoing), Equity Long/Short strategies have benefited from the positive drift in equities. Event and Market Neutral have remained somewhat related but are slightly positive for the year.

In terms of exposure, and while imperfect compared to running actual models, it gives a general indication of what changed after the Trend-Following reversal in March. Equity positions have remained largely intact and short bond positions have been squared.

We also note that the USD debasement trade has picked up steam, as CTAs are generally short the USD against a basket of currencies. Up until last year, this was generally a long position. In other sectors, we do not see a high correlation. Here, it can be observed that correlation during reversal may tell us more about the tendency for markets to behave in one way rather than telling us a lot of individual exposures.

Next week, we expect to have a slew of return estimates for April. Stay tuned. To get the email directly in your inbox, feel free to subscribe to our weekly updates.

  •  

Best’n’Worst March 2023

March turned out to be a strange month, a short-lived banking crisis heavily influenced the result for trend-based trading strategies but did not impact the overall performance of other strategies.

Overall, our rankings provide a useful starting point for investors who are looking to compare and evaluate different investment strategies. However, it is important to keep in mind that no single metric or ranking can capture all of the nuances and complexities of the investment landscape, and investors should conduct their due diligence and consult with financial professionals before making any investment decisions.

All data is believed to be reliable, but cannot be guaranteed to be correct.

CTA

March 2023 was a month where the winners of 2022 gave back profits. We note that several of the best-performing systematic managers are now ranking close to the bottom of the list. In the end, the exposure to fixed income turned out to be the major determinant of March’s performance.Β  Here it should be noted that investors that have maintained exposure to those strategies, since early 2022, are still up significantly.Β 

P/E Investments : FX Strategy - Aggressive  :  13.05% [12400.00]<br> CTAFX.com : Managed FX Accounts II  :  12.30% [0.03]<br> DUNN Capital Management : WMA  :  11.41% [858.00]<br> DUNN Capital Management : Managed Futures Strategy (Arrow)  :  11.31% [0.00]<br> Altis Partners Jersey Limited : Enhanced Macro  :  10.99% [3.05]<br> Quantitative Investment Management : Global Program 3x  :  -9.79% [101.30]<br> Soaring Pelican : Overnight Advantage  :  -9.89% [900.00]<br> Superfund Capital Management : Green Silver SICAV  :  -10.27% [93.18]<br> AIS Capital Management : MAAP 3-6X  :  -16.37% [50.03]<br> FX NOR AS : Global Makro  :  -18.55% [0.00]<br> >


By studying the performance of individual CTAs, investors can gain a deeper understanding of the various factors that contribute to success in this space, including risk management, diversification, and the ability to adapt to changing market conditions.Β 

Skylar Capital Management : Natural Gas And Power  :  -1.12% [561.86]<br> Numberline Capital Partners : Numberline  :  -0.33% [0.65]<br> INSCH Capital Management SA : Kintore  :  1.59% [41.19]<br> WG Wealth Guardian : QT Program  :  -0.32% [1.50]<br> CTAFX.com : Managed FX Accounts II  :  12.30% [0.03]<br> Transtrend BV : Tulip Trend Fund  :  2.36% [127.23]<br> Superfund Capital Management : Green Silver SICAV  :  -10.27% [93.18]<br> Superfund Capital Management : Green SPC 1.5x  :  1.71% [87.89]<br> DUNN Capital Management : D'Best Futures Fund  :  10.31% [75.00]<br> Superfund Capital Management : Green SPC 2x  :  2.25% [2.65]<br> >

To explore the full list of CTAs and their rankings, including dynamic updates as new data becomes available, we invite you to visit our website at the Link provided.Β 

Market Neutral

Market Neutral is a popular strategy among investors due to its low volatility and steady returns over time. Unlike other strategies that may produce large gains or losses in a short period, Market Neutral tends to accumulate returns gradually over time.

RAM : Long Short European  :  3.55% [168.32]<br> AQR Capital Management : Equity Market Neutral  :  3.25% [0.00]<br> Aphilion : Aphilion SIF  :  3.02% [46.04]<br> DNCA Invest : Miuri  :  2.96% [347.70]<br> KLP Kapitalforvaltning AS : KLP Alfa Global Energi  :  2.79% [266.80]<br> PIMCO : PIMCO RAE Fundamental Advantage PLUS  :  -1.38% [0.00]<br> Seven : Fortress Fund  :  -1.48% [1.91]<br> LGT Capital Partners : LGT Sustainable Equity Market  :  -1.50% [108.19]<br> Wellington : Climate Market Neutral  :  -1.72% [33.62]<br> Maverick : QM Neutral (GS)  :  -3.76% [394.63]<br> >

While the average performance of Market Neutral funds is largely driven by factor performance, there are also specific funds that may be exposed to unique strategies that are not captured by academic factors.

Exane : Ceres  :  2.33% [243.32]<br> Zest : North America Pairs Trading  :  0.58% [33.54]<br> DNCA Invest : Miuri  :  2.96% [347.70]<br> Blackrock : Asia-Pacific Diversified  :  0.49% [30.39]<br> Pictet Asset Management : Agora  :  2.66% [0.00]<br> Cognios : Cognios Market Neutral Large Cap  :  -0.60% [0.00]<br> QQM Fund Management : QQM Equity Hedge  :  1.14% [63.90]<br> MarshallWace : Systematic Alpha Market Neutral  :  -0.50% [1149.97]<br> PIMCO : PIMCO RAE Fundamental Advantage PLUS  :  -1.38% [0.00]<br> Crossmark Steward : Equity MN Instl  :  0.18% [0.00]<br> >

To explore our extensive list of Market Neutral funds and their dynamic rankings, we invite you to visit our website at the link provided here.Β 

Equity Long/Short

Equity Long/Short strategies are investment approaches that involve taking both long and short positions in equities in order to potentially profit from the performance of individual stocks or the broader equity markets.Β 

Cleaves Asset Management : Cleaves Shipping Fund  :  13.75% [0.00]<br> Borea Asset Management AS : Borea Utbytte  :  8.61% [190.90]<br> Argonaut : Absolute Return  :  6.77% [108.57]<br> Symmetry Invest : Symmetry Invest AS  :  5.10% [107.70]<br> Redwood Partners : Redwood  :  4.89% [9.10]<br> Finlabo : Dynamic US Equity  :  -7.81% [4.01]<br> Coeli Asset Management : Coeli Absolute European Equity  :  -8.22% [148.60]<br> Prior & Nilsson Fond och Kapitalforvaltning : PriorNilsson Fastighet  :  -9.78% [1.80]<br> Jupiter : International Financials  :  -10.73% [30.37]<br> Redwood Partners : Redwood  :  -15.36% [7.80]<br> >

Therefore, while the performance of Long/Short equity strategies is influenced by the broader equity markets, the best and worst managers are typically those who are able to identify and capitalize on idiosyncratic security-specific situations, as opposed to simply relying on market trends.

HELSINKI CAPITAL PARTNERS : HCP Focus Fund  :  3.46% [9.60]<br> Pareto Asset Management AS : Pareto Total  :  4.21% [763.40]<br> Sherborne : Investors Guernsey  :  -0.79% [0.00]<br> Alkeon : Equity Long/Short  :  2.48% [56.85]<br> RiverPark : RiverPark Long/Short Opportunity  :  4.81% [0.00]<br> Zeal : Greater China (Lumyna)  :  -5.22% [11.60]<br> Forester : Forester Value  :  -3.19% [0.00]<br> Finlabo : Dynamic US Equity  :  -7.81% [4.01]<br> Accendo Capital : Accendo Capital  :  -3.88% [286.80]<br> Disciplined Alpha : U.S. Long Short  :  0.57% [5.39]<br> >

To explore our extensive Equity Long/Shortlist, with dynamic rankings, please see Link

Event Driven

Event-Driven managers are commonly exposed to various arbitrage/spread risks related to specialist situations securities. Managers with concentrated exposure tend to end up on this list and exploring the drivers of out or underperformance may yield insights.

Neuberger Berman : Distressed Debt Extended Life Shares  :  3.11% [0.00]<br> Portland : Hill Catalyst Driven  :  2.78% [26.20]<br> Ramius : Merger Arbitrage (Lumyna)  :  1.07% [49.82]<br> Formue Nord : Fokus  :  0.97% [75.20]<br> Kellner : Kellner Merger  :  0.88% [0.00]<br> Boussard Gavaudan : Absolute Return  :  -2.35% [117.35]<br> Cheyne : Cheyne Arbitrage (U Access)  :  -2.86% [81.10]<br> Third Point : Third Point  :  -4.17% [0.00]<br> Odey : Special Situations  :  -5.36% [76.86]<br> Oceanwood : Opportunities  :  -6.34% [131.44]<br> >

When a manager has concentrated exposure to a particular event or company, they may end up on a list of top performers or underperformers in the Event-Driven strategy. Exploring the drivers of their outperformance or underperformance may yield insights into the effectiveness of their investment approach.

Portland : Hill Catalyst Driven  :  2.78% [26.20]<br> CIAM : Satellite Event Driven  :  -1.95% [13.42]<br> Pictet : Agora  :  -1.78% [398.44]<br> Hadron : Alpha Select  :  -0.71% [6.27]<br> Camelot : Camelot Event Driven  :  0.65% [0.00]<br> Cheyne : Cheyne Arbitrage (U Access)  :  -2.86% [81.10]<br> Boussard Gavaudan : Absolute Return  :  -2.35% [117.35]<br> Neuberger Berman : Distressed Debt Global Shares  :  0.00% [0.00]<br> Oceanwood : Opportunities  :  -6.34% [131.44]<br> Third Point : Third Point  :  -4.17% [0.00]<br> >

Our Event-Driven list can be explore here: Link

Risk Premia

Risk Premia managers are commonly implemented well-explored and researched systematic strategies.

These may be viewed as a general proxy for Hedge Fund exposure. Performance of specific factors may reveal differences and similarities to your own portfolio. To explore our extensive Risk Premia list please see Link

Β 

Nordea Asset Management : Nordea 1  Alpha 15 MA Fund  :  3.95% [5325.60]<br> Neuberger Berman : US Equity Put Write  :  3.16% [517.43]<br> Blackrock : Style Advantage  :  2.94% [95.06]<br> Nordea Asset Management : Nordea 1  Alpha 10 MA Fund  :  2.90% [5442.00]<br> Quadriga : Stable Return  :  2.04% [4.95]<br> Credit Suisse Multialternative : Credit Suisse Multialternative  :  -3.81% [0.00]<br> AQR Capital Management : Alternative Risk Premia  :  -5.92% [0.00]<br> AQR Capital Management : Style Premia  :  -6.83% [337.18]<br> AQR Capital Management : Style Premia Alternative  :  -6.90% [0.00]<br> Nomura : Fixed Income Risk Premia  :  -12.28% [1.35]<br> >

Quadriga : Stable Return  :  2.04% [4.95]<br> Catalyst Funds : Systematic Alpha  :  0.12% [0.00]<br> Blackrock : Style Advantage  :  2.94% [95.06]<br> Lumyna : Merrill Lynch MCLX  :  1.71% [277.30]<br> Neuberger Berman : US Equity Put Write  :  3.16% [517.43]<br> Credit Suisse Multialternative : Credit Suisse Multialternative  :  -3.81% [0.00]<br> Nomura : Fixed Income Risk Premia  :  -12.28% [1.35]<br> Capital Fund Management : Diversified  :  0.71% [79.10]<br> BNP Theam : Absolute Alpha  :  -2.50% [13.96]<br> BNP Theam : Quant Equity  :  -0.35% [19.30]<br> >

Crypto

Crypto managers are performing in the first quarter of 2023, erasing some of the losses suffered in 2022.

Returns tend to be double-digit (or even triple-digit for the best funds), simply due to the volatility of the asset class. To explore our extensive Crypto Strategy list, with dynamic rankings, please see Link

Β 

Digital Capital Management : CAF Class F  :  30.31% [10.29]<br> Value Token : AUREAPRIMA  :  27.27% [0.00]<br> 3iQ Corp : The Bitcoin Fund  :  23.00% [237.87]<br> Disguise Edg : MMALUNA  :  22.78% [0.00]<br> Ethereal Capital : Ethereal Capital DeFI Index  :  22.76% [0.00]<br> Sustainable Crypto Selection : SCS Sustainable Crypto Selection  :  -20.90% [0.00]<br> Coincident Capital : Coincident  :  -24.00% [220.00]<br> FlyingDutch : FLIGHINGDUTCH  :  -25.37% [0.00]<br> Low Fees Top Fundamentals : Low Fees Top Fundamentals  :  -26.37% [0.00]<br> INVESTMOX : INVESTMOXROLLERCOASTER INVESTMOX Rollercoaster  :  -27.70% [0.00]<br> >

TheCryptoOwl Strategy : THECRYPTOOWL  :  21.04% [0.00]<br> AbacusBlock Index : ABACUSBLOCK  :  6.20% [0.00]<br> Crush : CCC Crush Crypto Core  :  -16.84% [0.00]<br> Hole in One Josch : 554BC485571344C890D16DC3BE4460  :  12.16% [0.00]<br> Digital Capital Management : CAF Class F  :  30.31% [10.29]<br> Bank Genese : BANKGENESE  :  3.19% [0.00]<br> Sustainable Crypto Selection : SCS Sustainable Crypto Selection  :  -20.90% [0.00]<br> Coincident Capital : Coincident  :  -24.00% [220.00]<br> Low Fees Top Fundamentals : Low Fees Top Fundamentals  :  -26.37% [0.00]<br> INVESTMOX : INVESTMOXROLLERCOASTER INVESTMOX Rollercoaster  :  -27.70% [0.00]<br> >

Past performance is not indicative of future results. Based on the most recent return data that we have available, we provide an overview of the best and worst-performing strategies for each category, taking into account both monthly and yearly results. Our analysis is based on proprietary composite data streams that we have compiled, but we must note that there is always the possibility of errors or inaccuracies in our calculations.Β 

It is important to note that our rankings are not filtered for Asset Under Management, meaning that funds of any size can be included in our analysis. Our rankings are based solely on a simple return metric without adjusting for volatility, so some funds may have a higher risk profile than others.

  •  

Database Update – What do we cover?

Nilsson Hedge provides a CTA/Managed Futures and Hedge Fund database at a competitive price. The median manager is a CTA or Managed Futures Managers, but we also cover more traditional strategies such Equity Long/Short. We have almost twelve thousand return streams that are used to create a comprehensive intelligence source for Hedge Fund Performance.

While initially starting out as a CTA/Macro focused database, we are now covering a large amount of more traditional Hedge Fund strategies. Today, of the active strategies, 1/3 are CTAs. We are much more than a CTA database.

Based on the data that we have in the database, we have the following estimates for strategy performance:

  • The estimated MTD performance for Hedge Funds (including Crypto Trading Strategies) is -0.0% taking the YTD number to 6.6%.
  • The estimated MTD performance for Hedge Funds (excluding Crypto Trading Strategies) is -0.7% taking the YTD number to 0.7%.The estimated MTD performance for CTAs is -1.6% taking the YTD number to -0.7%.
  • We note that this is an estimate for reporting funds, and that better performing funds typically report early. These estimates do not include funds that have stopped reporting. For the survivorship adjusted number, we would like to direct you to the NilssonHedge indices at https://nilssonhedge.com/index/.
  • As pointed out, Trend following strategies suffered in March. More info can be found here: https://nilssonhedge.com/reports/dispersion/

Explore our overview of Hedge Fund performance at https://nilssonhedge.com/reports/nilsson-report/

  • The Database contains 2947 different managers, representing 5960 different investment strategies.
  • For the current reporting month, 1704 managers have reported returns. For the prior month, we have 2054 live managers.
  • In terms of CTAs, for the current reporting month, 460 CTA programs have reported returns. For the prior month, we have 660 live programs.
  • In total, the database contains 35652 years of manager data.
  • We cover 705 bn of Assets in the Hedge Fund space. Out of which 423 bn of Assets in CTA/Managed Futures managers.
  • With more than 400,000 unique data points this is an interesting resource for academics and students. We offer free access to academic researchers.

Over the last three calendar months, we have added 137 new strategies to the database.

  • Database overview, including graveyard:
  • Number of CTA Strategies: 3167
  • Number of Equity Long Short Strategies: 454
  • Number of Market Neutral Strategies: 130
  • Number of Event Driven Strategies: 80
  • Number of Fixed Income Strategies: 208
  • Number of Crypto Strategies: 975
  • Number of Asset Allocation Strategies: 212
  • Number of Risk Premia Strategies: 78

To view estimates of current performance, our daily indices provide unique insights (https://nilssonhedge.com/index/daily-indices/). CTAs are staging a comeback in April.

Thansk for your attention! Your support is much appreciated.

  •  

What worked for CTAs?

First, we wish you all a Happy Holiday. Furthermore, we hope the testing times that Trend Following strategies endured in March enables the strategy to successfully resurrect during the rest of the year. As we are collecting more and more returns for March-22, we are getting a clear picture of how different strategies faired.

While not halfway through the month, we have close to 50% of the managers reporting numbers. There may be some early reporting bias in our numbers, but we believe it gives a reasonable picture.

Long story short, as long as you did not engage in trend following you actually did pretty ok. Unfortunately, a large amount of the larger managers are focused on Trend Following strategies in the more liquid markets.

While most Hedge Fund strategies have generated positive results YTD, the March Madness in Fixed Income markets, has caused the Q1 results for CTA to lag the other strategies.

To explore the managers that are captured so far, please check out our Ranking Page (login required).

Looking through the data, we note that most of the negative outliers are indeed Trend Following strategies. Other strategies had much more mixed results, with an average flat result for March. Finally, a month where diversification paid off. Given that March was not a particularly eventful month for Equity markets, option strategies faired well.

In terms of indices, our broad-based CTA index is down 1.5%. From a longer perspective, almost half of the inflation-driven pnl generated in the early half of 2022 has been given back. A lot of positions got reset over the last couple of weeks and CTAs are likely completely out of short fixed-income positions.

Strangely enough, the picture is similar for discretionary managers. Not the same pattern, but while uncorrelated, Discretionary managers have also faced difficult trading conditions post the half-year mark in 2022.

Commodity Specialists, which got a fair amount of positive attention in the last weeks. For instance, this report (by Bridge Alternatives) has so far reported a flat return, despite difficult trading conditions in several commodities. Commodity Specialists has had an exceptional run during the last four years and it may have been the most Sharpe Ratio efficient strategy over a tumultuous period.

As usual, our databases are updated and available for download.

  •  

Flash Report March 2023

March turned out to be an exciting month, but ultimately it was much ado about nothing. Except for some Macro funds that had a strong view on continued inflationary pressures, CTAs were the largest victim of the intra-month banking crisis. For a short moment, the ghosts of the Great Financial Crisis were reborn, but swift regulatory action managed to stave off contagion and systemic risk pressures. In the end, equities continued to climb a wall of worries.

In short:

  • Equities had positive returns, despite a banking crisis (Silicon Valley Bank, Credit Suisse, …).
  • Treasury Bonds strengthened significantly as capital was moved into less risky assets.
  • Commodities had a difficult month with the Energy Complex suffering.
  • The USD weakened, which is rather unique in a crisis scenario.
  • CTA, being largely short Fixed Income suffered as many Macro Funds, Corporate Treasurer, and Risk Managers bought β€œrisk-free” assets.
  • Despite a risk-off sentiment, Crypto strategies had positive returns

Our more traditional Liquid Alternative Indices faired rather ok in the first quarter. Equity Long/Short, Market Neutral, and Event Driven strategies are positive for the year. CTAs ended the first quarter with a significant drawdown.

IndexMarchYTD
Crypto3.3%38.9%
CTA-4.7%-3.6%
Equity Long/Short0.5%1.9%
Market Neutral-0.6%0.0%
Event Driven-0.3%0.5%

Next week, we will have a clearer picture of which CTAs lost and who managed to navigate the rapidly reversing Bond Markets. We note that CTAs are now likely scaled out of Bonds, slightly less exposed to Equities due to the increased volatility.

Using four simple Breakout Strategies to judge direction, we note that CTAs rapidly exited the short bond trade. The truly long-term trend followers may still be short-biased in bonds, but most other managers have flipped to a long position. This has happened before and will happen in the future. Trend following is not dead, but shaken.

  •  

Best’n’Worst February 2023

Back to our regular programming and we are pleased to share our ranking of liquid alternative strategies. While much will have changed once the March numbers start to trickle in a few days, we should enjoy the successes that some managers have been able to achieve.

Based on the most recent return data that we have available, we can provide a comprehensive overview of the top-performing and bottom-performing strategies for each category, taking into account both monthly and yearly results. Our analysis is based on proprietary composite data streams that we have compiled, but we must note that there is always the possibility of errors or inaccuracies in our calculations.

To be included in our rankings, funds must have reported returns for the current reporting month. This means that we may not have data on all funds in a given category, and our rankings should be considered within the context of the funds that we do have information on.

Additionally, if you find our analysis and insights valuable, we encourage you to sign up for our email list. By subscribing, you will receive regular updates and exclusive content related to investment strategies and market trends, which can help you stay informed and make better-informed investment decisions.

To sign up, simply visit our website and provide us with your email address. We promise not to spam you or share your information with third parties, and you can unsubscribe at any time. Don’t miss out on this valuable opportunity to stay ahead of the curve in the ever-changing world of finance.

CTA

It is worth noting that while the general Commodity Trading Advisor (CTA) industry tends to be trend-driven, there are always outliers that are driven by specific markets or market effects. This can make for a high degree of dispersion among the best and worst-performing funds within a given category, but it can also provide valuable insights into how different strategies react to different market developments.

P/E Investments : FX Strategy - Aggressive  :  13.05% [12400.00]<br> DUNN Capital Management : WMA  :  11.41% [858.00]<br> DUNN Capital Management : Managed Futures Strategy (Arrow)  :  11.31% [0.00]<br> Altis Partners Jersey Limited : Enhanced Macro  :  10.99% [3.05]<br> DUNN Capital Management : D'Best Futures Fund  :  10.31% [75.00]<br> Quantitative Investment Management : Global Program 3x  :  -9.79% [101.30]<br> Soaring Pelican : Overnight Advantage  :  -9.89% [900.00]<br> Superfund Capital Management : Green Silver SICAV  :  -10.27% [93.18]<br> AIS Capital Management : MAAP 3-6X  :  -16.37% [50.03]<br> FX NOR AS : Global Makro  :  -18.55% [0.00]<br> >

By studying the performance of individual CTAs, investors can gain a deeper understanding of the various factors that contribute to success in this space, including risk management, diversification, and the ability to adapt to changing market conditions. This can be particularly useful for those who are looking to build a diversified portfolio of alternative investments, as CTAs can offer a source of non-correlated returns that can help to balance out risk in traditional asset classes.

Β 

Skylar Capital Management : Natural Gas And Power  :  -1.12% [561.86]<br> ABR : Enhanced Short Volatility  :  -1.46% [3.45]<br> Glenhaven Capital : Glenhaven Global II  :  -1.80% [4.90]<br> Mulvaney Capital Management : Global Diversified Program  :  7.95% [240.00]<br> Numberline Capital Partners : Numberline  :  -0.33% [0.65]<br> Robust Methods : Robust Methods LLC  :  -9.76% [0.00]<br> Quantitative Investment Management : Global Program 3x  :  -9.79% [101.30]<br> Blue Creek Capital Management : Blue Creek Global Opportunistic Program  :  8.00% [2.00]<br> Moddco Capital Associates : MCA  :  -5.90% [0.11]<br> Superfund Capital Management : Green Silver SICAV  :  -10.27% [93.18]<br> >

To explore the full list of CTAs and their rankings, including dynamic updates as new data becomes available, we invite you to visit our website at the Link provided. Here, you will find a wealth of information on the performance of different CTAs across a range of markets and strategies, as well as insights and analysis from our team of experts in the field. Whether you are a seasoned investor or just starting out, our CTA rankings can provide valuable guidance and help you make more informed investment decisions.

Market Neutral

Market Neutral is a popular strategy among investors due to its low volatility and steady returns over time. Unlike other strategies that may produce large gains or losses in a short period, Market Neutral tends to accumulate returns gradually over time. This makes it an attractive option for those looking to achieve steady, long-term growth without taking on excessive risk.

RAM : Long Short European  :  3.55% [168.32]<br> AQR Capital Management : Equity Market Neutral  :  3.25% [0.00]<br> Aphilion : Aphilion SIF  :  3.02% [46.04]<br> DNCA Invest : Miuri  :  2.96% [347.70]<br> KLP Kapitalforvaltning AS : KLP Alfa Global Energi  :  2.79% [266.80]<br> PIMCO : PIMCO RAE Fundamental Advantage PLUS  :  -1.38% [0.00]<br> Seven : Fortress Fund  :  -1.48% [1.91]<br> LGT Capital Partners : LGT Sustainable Equity Market  :  -1.50% [108.19]<br> Wellington : Climate Market Neutral  :  -1.72% [33.62]<br> Maverick : QM Neutral (GS)  :  -3.76% [394.63]<br> >

While the average performance of Market Neutral funds is largely driven by factor performance, there are also specific funds that may be exposed to unique strategies that are not captured by academic factors. This can create opportunities for investors to gain an edge by identifying and investing in funds that are able to deliver above-average returns due to their specialized knowledge or approach.

Exane : Ceres  :  2.33% [243.32]<br> Zest : North America Pairs Trading  :  0.58% [33.54]<br> DNCA Invest : Miuri  :  2.96% [347.70]<br> Pictet Asset Management : Agora  :  2.66% [0.00]<br> Exane : Overdrive  :  2.02% [168.63]<br> Fulcrum Asset Management : Thematic Equity Market  :  -1.15% [400.98]<br> Man GLG : GLG Innovation Equity  :  -1.28% [182.88]<br> JanusHenderson : Global Equity Market Neutral  :  -1.04% [105.68]<br> Cognios : Cognios Market Neutral Large Cap  :  -0.60% [0.00]<br> Crossmark Steward : Equity MN Instl  :  0.18% [0.00]<br> >

To explore our extensive list of Market Neutral funds and their dynamic rankings, we invite you to visit our website at the link provided here. Here, you will find a wealth of information on the performance of different funds, as well as insights and analysis from our team of experts in the field. Whether you are a seasoned investor or just starting out, our Market Neutral rankings can provide valuable guidance and help you make more informed investment decisions.

Equity Long/Short

Equity Long/Short strategies are investment approaches that involve taking both long and short positions in equities in order to potentially profit from the performance of individual stocks or the broader equity markets. As per common knowledge, it is believed that approximately half of the returns for these strategies are influenced by the underlying equity markets.

This means that if the equity markets are performing well, then a Long/Short equity strategy is likely to produce positive returns, and if the markets are underperforming, the strategy is likely to produce negative returns.

Cleaves Asset Management : Cleaves Shipping Fund  :  13.75% [0.00]<br> Borea Asset Management AS : Borea Utbytte  :  8.61% [190.90]<br> Argonaut : Absolute Return  :  6.77% [108.57]<br> Symmetry Invest : Symmetry Invest AS  :  5.10% [107.70]<br> Redwood Partners : Redwood  :  4.89% [9.10]<br> Zeal : Greater China (Lumyna)  :  -7.44% [18.95]<br> Platinum : World Portfolios Asia  :  -7.89% [128.12]<br> Veritas : China  :  -8.79% [32.19]<br> Cederberg Capital : Greater China (Banor)  :  -10.46% [111.85]<br> JanusHenderson : Horizon China  :  -11.76% [59.19]<br> >

Therefore, while the performance of Long/Short equity strategies is influenced by the broader equity markets, the best and worst managers are typically those who are able to identify and capitalize on idiosyncratic security-specific situations, as opposed to simply relying on market trends.

HELSINKI CAPITAL PARTNERS : HCP Focus Fund  :  1.82% [9.60]<br> Petrus Advisers : Special Situations  :  3.86% [80.57]<br> Cleaves Asset Management : Cleaves Shipping Fund  :  13.75% [0.00]<br> Redwood Partners : Redwood  :  4.89% [9.10]<br> DNCA Invest : Venasquo  :  4.37% [123.00]<br> AmericaFirst : AmericaFirst Defensive Growth  :  -4.35% [0.00]<br> Forester : Forester Value  :  -3.98% [0.00]<br> Accendo Capital : Accendo Capital  :  0.03% [297.60]<br> Pensum Asset Management : Global Opportunities  :  -3.97% [16.80]<br> Disciplined Alpha : U.S. Long Short  :  -5.91% [8.59]<br> >

To explore our extensive Equity Long/Shortlist, with dynamic rankings, please see Link

Event Driven

Event-Driven managers are commonly exposed to various arbitrage/spread risks related to specialist situations securities. Managers with concentrated exposure tend to end up on this list and exploring the drivers of out or underperformance may yield insights.

Pictet : Agora  :  2.77% [424.68]<br> CIAM : Satellite Event Driven  :  2.10% [15.53]<br> Driehaus : Event Driven  :  0.82% [0.00]<br> PrivilEdge : Amber Event Europe  :  0.82% [150.14]<br> Formue Nord : Fokus  :  0.70% [75.70]<br> Portland : Hill Catalyst Driven  :  -1.37% [25.28]<br> PSAM : Global Event (Lumyna)  :  -1.84% [614.92]<br> Third Point : Third Point  :  -1.96% [0.00]<br> Camelot : Camelot Event Driven  :  -2.67% [0.00]<br> Odey : Special Situations  :  -3.17% [78.80]<br> >

When a manager has concentrated exposure to a particular event or company, they may end up on a list of top performers or underperformers in the Event-Driven strategy. Exploring the drivers of their outperformance or underperformance may yield insights into the effectiveness of their investment approach.

Portland : Hill Catalyst Driven  :  -1.37% [25.28]<br> CIAM : Satellite Event Driven  :  2.10% [15.53]<br> Pictet : Agora  :  2.77% [424.68]<br> Hadron : Alpha Select  :  -0.36% [6.17]<br> Odey : Special Situations  :  -3.17% [78.80]<br> PSAM : Global Event (Lumyna)  :  -1.84% [614.92]<br> Boussard Gavaudan : Absolute Return  :  -0.08% [160.43]<br> AllianceBernstein : Event Driven Portfolio  :  -0.59% [174.78]<br> Third Point : Third Point  :  -1.96% [0.00]<br> Alpine : Merger Arbitrage  :  -1.21% [244.90]<br> >

To explore our extensive Event-Driven list, with dynamic rankings, please see Link

Fixed Income

Similar to Equity Long/Short managers, Fixed Income managers are typically influenced by the underlying market conditions. However, for this list, the focus is on managers who are sensitive to a specific subsector of the fixed-income market, particularly those engaged in the lowest part of the capital structure.

CABA Capital : CABA Hedge  :  4.01% [139.40]<br> Danske Bank Asset Management : Danske Invest Fixed Income Global Value  :  3.58% [786.00]<br> Nykredit Asset Management : Nykredit KOBRA Hedge Fund  :  2.91% [5.80]<br> Nykredit Asset Management : Nykredit MIRA Hedge Fund  :  2.89% [27.40]<br> Danske Bank Asset Management : Danske Invest Fixed Income Relative Value  :  2.72% [440.00]<br> Manulife : Asian Bond Absolute  :  -3.23% [62.45]<br> Lazard : Emerging Markets Debt Blend  :  -3.31% [0.00]<br> Formuepleje Fund Management : Formuepleje Fokus  :  -3.37% [145.80]<br> Legg Mason : Western Asset Macro Opp  :  -5.51% [1805.85]<br> Secured : Secured Income Fund Plc  :  -9.23% [0.00]<br> >

Β 

The lowest part of the capital structure refers to the debt securities that have the highest risk of default, but also potentially offer higher yields. These managers are typically seeking to generate higher returns by taking on higher levels of credit risk, and they may specialize in a particular sector, such as high-yield corporate bonds or distressed debt.

Axiom : European Financial Debt Fund Limited  :  2.24% [0.00]<br> Danske Bank Asset Management : Danske Invest Fixed Income Global Value  :  3.58% [786.00]<br> Capital Four Management : Capital Four Credit Opportunities Fund  :  1.65% [278.40]<br> Danske Bank Asset Management : Danske Invest Fixed Income Relative Value  :  2.72% [440.00]<br> Selwood : Market Neutral Credit (Alma)  :  1.49% [141.33]<br> Ironshield : Credit Fund  :  -0.17% [70.07]<br> CQS : New City High Yield Fund  :  -0.39% [0.00]<br> Stadion : Trilogy Alternative Return  :  -1.94% [0.00]<br> SME : Credit Realisation  :  -0.47% [0.00]<br> GCP : Asset Backed Income  :  -2.84% [0.00]<br> >

To explore our extensive Fixed Income list, with dynamic rankings, please see Link

Risk Premia

Risk Premia managers are commonly implemented well-explored and researched systematic strategies. These may be viewed as a general proxy for Hedge Fund exposure. Performance of specific factors may reveal differences and similarities to your own portfolio. To explore our extensive Risk Premia list, with dynamic rankings, please see this Link

Β 

Nomura : Fixed Income Risk Premia  :  10.80% [1.41]<br> AQR Capital Management : Style Premia Alternative  :  5.83% [0.00]<br> AQR Capital Management : Style Premia  :  5.63% [340.68]<br> AQR Capital Management : Alternative Risk Premia  :  4.52% [0.00]<br> Blackrock : Style Advantage  :  3.23% [98.57]<br> Loomis Sayles : Alternative Risk Premia  :  -1.16% [20.70]<br> Quadriga : Stable Return  :  -1.68% [4.79]<br> Neuberger Berman : US Equity Put Write  :  -1.70% [562.43]<br> Mount Lucas Management Corporation : AlphaCentric Symmetry Strategy  :  -1.88% [0.00]<br> Estlander & Partners : Glacies  :  -2.54% [1.20]<br> >

Quadriga : Stable Return  :  -1.68% [4.79]<br> Nomura : Fixed Income Risk Premia  :  10.80% [1.41]<br> Catalyst Funds : Systematic Alpha  :  -0.11% [0.00]<br> AQR Capital Management : Style Premia  :  5.63% [340.68]<br> AQR Capital Management : Style Premia Alternative  :  5.83% [0.00]<br> BNP Theam : Absolute Alpha  :  0.29% [14.64]<br> Nordea Asset Management : Nordea 1  Alpha 10 MA Fund  :  0.07% [5442.00]<br> Nordea Asset Management : Nordea 1  Alpha 15 MA Fund  :  0.12% [5325.60]<br> BNP Theam : Quant Equity  :  0.01% [32.98]<br> Capital Fund Management : Diversified  :  -0.16% [84.85]<br> >

Crypto

As usual Crypto traders are the wildest bunch on the street. Returns tend to be double-digit (or even triple-digit for the best funds), simply due to the volatility of the asset class. To explore our extensive Crypto Strategy list, with dynamic rankings, please use this Link

Β 

GoldHorn : Crypto Venture  :  42.23% [0.00]<br> Hole in One Josch : 554BC485571344C890D16DC3BE4460  :  36.46% [0.00]<br> Crush : CCC Crush Crypto Core  :  33.91% [0.00]<br> Rexus Prime : REXPRIME  :  32.49% [0.00]<br> LiesCo Fund Vitali Lis : LIESCO  :  26.84% [0.00]<br> Moon Fund : MOONFUND  :  -17.41% [0.00]<br> Prophet Priest and King : KINGOFALL  :  -21.60% [0.00]<br> DrivenByData : ANALYTICODESCRETIO  :  -22.90% [0.00]<br> Capital PLUS ULTRA Capital : SEMPERINVEST PLUS ULTRA  :  -25.14% [0.00]<br> Bank Genese : BANKGENESE  :  -34.40% [0.00]<br> >

Β 

Crush : CCC Crush Crypto Core  :  33.91% [0.00]<br> TheCryptoOwl Strategy : THECRYPTOOWL  :  15.06% [0.00]<br> AbacusBlock Index : ABACUSBLOCK  :  9.22% [0.00]<br> Lavaliere Capital Management : Lavaliere Capital Fund  :  15.64% [35.00]<br> IGO Strategy Mate : IGOSTRATEGY  :  13.27% [0.00]<br> Algoz Technologies : Digital Asset Fund  :  -8.40% [2.20]<br> The sky's the limit : 123456 DeFi strategy  :  -14.85% [0.00]<br> Prophet Priest and King : KINGOFALL  :  -21.60% [0.00]<br> Bank Genese : BANKGENESE  :  -34.40% [0.00]<br> Capital PLUS ULTRA Capital : SEMPERINVEST PLUS ULTRA  :  -25.14% [0.00]<br> >

Overall, our analysis provides a useful starting point for investors who are looking to compare and evaluate different investment strategies. However, it is important to keep in mind that no single metric or ranking can capture all of the nuances and complexities of the investment landscape, and investors should conduct their due diligence and consult with financial professionals before making any investment decisions.

Past performance is not indicative of future results.

  •  

What a week, huh? Captain, is it Monday, Wednesday, or Friday?

There is a popular meme going around that shows an intoxicated Captain Haddock downing a stiff drink, complaining about having bad a rough week. Tintin smartly corrects him that it’s only Wednesday.

For Managed Futures managers, we can only imagine is how this week felt, especially so after having a rough day on Friday the 10th, when Silicon Valley Bank was halted. SVB was ultimately taken over by the FDIC over the prior weekend.

The NilssonHedge CTA index lost 5.1% in March, so far.

A lot of the goodwill that Trend Followers built throughout 2022 will likely have been undone. Janet Jackson’s song, β€œwhat have you done for me lately” sadly also applies to Trend Followers. No matter how strategic and long-term your client is.

30-Year bond (Barchart)

The Bond trend was a nice case of how a trend follower strategy typically walks up the stairs and finally jumps out of the window as the trend change. Or as in this case, figuratively being defenestrated by the collective force of risk managers, traders, and asset allocators striving to reduce duration, credit mismatches, and losing trades in their books. A week where a triple witching coincided with a banking crisis.

While the end of the prior week was not stellar, this week represents a major turn of fortune for trend followers. The market changed from pricing in a FED that might eventually stop increasing policy rates, to pricing in a major banking crisis. The pricing is now offering substantial odds that the FED may actually decrease rates throughout 2023. An implicit macro view held by the average trend followers was the β€œinflation is transitory for longer” theme.

Daily returns for the NilssonHedge CTA index

CTAs, as measured by the NilssonHedge Daily CTA index, lost 3.5% on Monday as bonds rallied. Tuesday offered a small relief and perhaps a good point to liquidate short-duration positions into weakness and the index recorded a gain of 0.9%.

Unfortunately for Trend Followers, the bond rally continued on Wednesday. At this point, a lot of CTAs had reduced fixed income positions by approximately half, in wake of the trend changes and increased volatility. Wednesday resulted in a loss of 1.8%.

SOFR Dec 23 Futures (Barchart)

Thursday offered a modest relief (+0.5%), but the appetite for government securities continued on Friday. This time, the loss was more normal with a loss of 80bps. This was a near-perfect combination of punches with the two first being the strongest. Here we note that our index is not a pure Trend Index, but also contains managers using other strategies.

Largely explaining the results for the week is the rally in the US 10y futures, which moved approximately 5 handles (from 110 to 115) from Friday the prior week to Friday this week.

What is pleasing to see is that the sensitivity that CTAs have to bond moves have been rapidly reduced (both position and risk-driven reductions), the moves were so significant that CTA suffered one of their absolutely worst daily losses (not the worst, but close), 2-day losses, etc. While CTAs did not trigger the bond rally, they and countless other entities added fuel to the fire as they needed to close out existing shorts.

Not only did the benchmark bonds increase significantly in price, but also the shorter duration instrument (Eurodollar and the SOFR futures) had extraordinarily steep price changes. This also contributed significantly to the negative week.

On the back of this, at least one Global Macro with significant pedigree has closed. Graticule, a Singapore-based fund, closed shop after having taken wrong-way bets in short rates. Given how markets have been trading there may be more fund closures.

As the SVB and FRB (First Republic Bank) crisis morphed into the international area and threatened banks with larger balance sheets (CS…) the quickly evolving banking crisis is still ongoing. Despite various interventions over the last week regulators have yet to install the necessary confidence into markets.

Our Daily CTA Index is now close to the maximum drawdown. The speed of the move is similar to the COVID-related March 2020 drawdown that we saw. You will see a similar picture for other daily CTA indices.

A number of lessons will probably be learned from this. Here are a few discussion points that may or may not be trivial:

  • Market diversification matters: We have seen the largest losses suffered by managers with concentrated positions in Short Rates.
  • Risk Management – volatility-driven position reductions when market volatility increases is a risk management component occasionally frowned upon by some managers.
  • Rebalancing frequency: some CTAs rebalance continuously, while other rejig their portfolios weekly or even monthly. The unusual rapid market moves will refocus attention on this.
  • Long-Term Trend Following as a crisis alpha – perception matters and most investors that have been sold managed futures as crisis protection will be dissatisfied. CTAs came into this crisis short bonds (and long equity) and failed to provide protection against the start of the Banking Crisis 2.0. Equities held up fairly well during the week but sold off in the prior weeks.
  • Short-term strategies may naively offer better crisis alpha during rapid changes. If the crisis continues, long-term trend followers will eventually adjust their position. If the crisis is magically resolved over the next few weeks and we go back to business as usual, trend managers may be in for another whipsaw.
  • Short Duration and Trend Following – 2022 was one of the few years when short-duration bets paid off for trend followers. An interesting question is how much of that profits were given back in the recent rally and how your systems should be constructed to capture trends/outliers while not being subject to large givebacks when trading against the wind (carry). And how it’s compatible with providing equity market stress protection. While equity stress protection is not a stated goal for many managers, it is often the precise reason why long-term trend followers have a substantial allocation from institutional investors.

As usual, these market moves as this will probably not repeat in the future but will result in a number of manager reviews, and potential reassessment of the strategy, followed by flows in and out of managers as the dust settles. Buckle up and put on your best suit for the upcoming reviews

If there is any silver lining to this debacle, it is that since 2019, Managed Futures is still (barely) outperforming other liquid alternative strategies. The setback is painful and Trend Following has again shown that it is a pain arbitrage. It is a difficult partner, sometimes loving and caring, but occasionally also violently abusive.

If you have come this far, you can explore our index data for further insights:

As we are about to publish we learn that UBS has acquired CS. The terms of the deal are beyond our comprehension to fully analyze. But let’s hope that this is a light at the end of the rather short tunnel, and not another train (analog Bear Sterns followed by Lehman).

No Trend Following is not dead, but it is going to take some time to re-establish positions and recover the losses.

Is the CS rescue light at the end of the tunnel?

As per usual, our databases are updated and available to subscribers.

  •  

Crypto – SVB and USDC

Over the weekend, the ultimate fate of SVB (Silicon Valley Bank) will be determined. The FDIC has taken control of the bank and is working through the liquidation process to preserve as much capital as possible. A number of (former) Libertarians and free-market Hedge Fund managers have asked for a Government bailout of SVB.

Friday was a bad day for most Hedge Fund strategies. CTAs suffered as Bond Futures rallied sharply. Prior to Friday, CTAs were generally short duration and the rally caused large losses. What looked like a good start to the year, is now back to a more mundane year for most managers. However, the angst and market action were centered around the de-pegging of the USDC.

The Circle Logo

In this short update, mostly to sort through our own thoughts, we present the share price of SVB, and the impact on the US Dollar Coin (β€œUSDC”), a common stablecoin. And finally, we estimate the impact on β€œHodlers” as some of the strategies that we track had substantial exposure to the USDC.

SVB (Yahoo Finance) was halted on March 10th, 2023

SVB (was) is a large bank and regulators are currently working through the situation. The exact financial impact is still unsure. The expectations for widespread contagion are somewhat limited. There may be a permanent impact on β€œregional US” banks as they may face higher regulatory pressure in the future.

In the end, as many pundits have pointed out, the implosion of SVB stems from a mismanaged duration and interest rate risk. SVB was likely almost unhedged with regard to interest rates.

Source: SVB Strategic Q1’23 Update

The largest impact is likely on a number of startups and Venture Capitals. SVB had a large share of smaller emerging ventures as clients. The recent repricing of the tech/startup sector had a negative impact on SVB’s balance sheet. Together with a fall in bond prices and β€œhold-to-maturity” accounting this caused stress on the balance sheet of SVB. Ultimately leading to the demise of the bank.

In the Crypto space, there is a potential for collateral damage as the USDC that had exposure to SVB of $3.3bn or approximately 8%. The Coin broke the Peg on Friday and has been trading in a volatile manner. As the value of the SVB deposits is not likely zero, but rather valued slightly above 50 cents or more on the dollar the impact will be less.

USDC Price Chart (Coinbase)

USDC could be a potential way of trading any claims on SVB deposits. Cash timing is somewhat uncertain here though. There was an argument that USDC could result in a bank run as there was an understanding that any USDC would be convertible at par to regular USD.

Circle has promised to resume normal conversion on Monday but presumably, that requires a resolution of any advanced dividends from the deposits that they had. USDC offered relatively high transparency and was quick to disclose its exposure. It is unclear if USDC will offer conversion at par.

During Friday, the USDC traded at highly distressed levels, but the coins recovered considerably as the initial panic subsided. What is nice about Crypto Markets is that they are open 24/7 offering a real-time assessment of risk aversion.

USDC vs USDT (β€œTether”)

One of our proprietary data sets has access to Crypto Positions for a large share of the managers that we track. We noted a substantial reduction in the number of USDC held (that was the most popular stablecoin), in favor of Tether (USDT). We note that USDT offers less transparency than USDC but the platform where we source our data only offers a few stablecoins.

The move out of USDC to Tether likely caused a permanent loss for many strategies. In 2022, the concept of impermanent loss was widely adopted across the DeFi crowd. In the wake of Luna, we now see somewhat better risk behavior, but the selling pressure presumably contributed to the de-pegging of the USDC.

In the end, Crypto Strategies, while having ~20% exposure to USDC suffered a minor impact. We estimate that this was less than 1% on Friday/Saturday as most other Coins kept up well.

NilssonHedge Daily Crypto Index

In the end, we do not expect this to be an event similar to the LUNA coin. Depending on regulatory action, the markets may return to more stability on Monday. Ironically, CTAs seems to have been the main victim.

As per usual, our databases are updated and available to subscribers.

  •  

Performance Preview – Februrary 2023

As we only have two trading days left in February, we thought providing our readers with a performance preview of the expected results would be helpful. Much can obviously change in the final 48 hours so any observation here is preliminary. Using our daily indices, we comment on the expected February hedge fund results.

In a month where the equity market lost traction, CTA shows its diversification worth by providing modest portfolio protection and positive returns.

Our latest estimate is that a diversified portfolio of Managed Futures managers is up around 1.5%. L/S equity gave up returns in line with equity markets. Event Driven and Market Neutral strategies seem to have fared better and will probably have positive returns for February 23.

NilssonHedge Daily CTA Index shows a small gain YTD and a positive February 2023 return.
The NilssonHedge CTA Index is likely to be positive in February

Directional Crypto Managers had a strong revival in January, but the result is likely to be more modest this month. With two days to go, Crypto Strategies are positive. The result is only +2% which is not even a significant move for directional Crypto positions.

Trend Followers have likely kept on reducing positions in Equities and Bonds (but likely still short or neutral in these market sectors), and partly establishing new short USD positions. This seems to have worked throughout February and CTAs are likely to have recovered the initial January drawdown. To get a glimpse of estimates of market sensitivities we have developed aΒ pageΒ that is showing short-term correlation and beta estimates.

Since the inception of our Daily Indices, which has indeed been a very special period in Global Markets. CTA has better than other strategies. Equity L/S has lagged in equity markets but preserved capital as of late. Even Driven suffered from a lack of deal flows in 2022 (but also a lack of equity risk premia). As the Risk-Free rate increased the premiums available in the market have gotten larger. Market Neutral / Quant Equity is continuing to claw back the Value related drawdown that almost took out the strategy up until early 2021.

In Crypto Markets, the demise of FTX seems to have reduced volatility substantially. In itself an interesting observation. At this stage, we are not sure how to interpret it.

Our daily indices are freely available for download and the intereted analyst can dig into them.

  •  

Best’n’Worst January 2023

Using our extensive database, we have ranked close to 2,000 reporting hedge funds. From the best to the worst result in January. As noted by other market commentators, January was difficult for Trend Followers but was generally suitable for most other strategies, including the non-Trend CTAs. Most Hedge Fund strategies delivered positive performance.

Asset Allocation/Risk Parity did the best as long-only assets performed strongly. This also helped Equity L/S and Fixed Income strategies that have a persistent beta. On the flip side, we saw flat performance for Market Neutral and a small, unnoteworthy, gain for CTAs. Cryptos did really well as Technology assets rallied strongly.

CTA

A large share of the worst managers, on a performance basis, for January 2023 are the managers that did really well in 2022. Gravity is a mighty foe and the trend is your friend until it bends. Natural Gas traders continued to be fueled by rapid weather changes, and short volatility strategies continued to recover. To see the full CTA list, with dynamic rankings, please see Link

Skylar Capital Management : Natural Gas And Power  :  40.72% [588.41]<br> ABR : Enhanced Short Volatility  :  22.50% [3.45]<br> Soaring Pelican : Overnight Advantage  :  17.81% [0.99]<br> Glenhaven Capital : Glenhaven Global II  :  16.35% [5.00]<br> Numberline Capital Partners : Numberline  :  13.11% [0.72]<br> WG Wealth Guardian : QT Program  :  12.21% [1.50]<br> QTS Capital Management : Tail Reaper  :  11.18% [3.40]<br> Tudor Investment Corp : Tudor Momentum Fund Ltd.  :  10.28% [719.39]<br> Pan Capital Management LP : Energy Fund  :  9.43% [1067.00]<br> FX NOR AS : Global Makro  :  9.36% [0.00]<br> P/E Investments : FX Strategy - Aggressive  :  -6.95% [12800.00]<br> Quest Partners : Quest Equity Hedge Program (QEH)  :  -7.29% [22.95]<br> Superfund Capital Management : Green Silver SICAV  :  -7.47% [123.61]<br> DUNN Capital Management : D'Best Futures Fund  :  -7.90% [87.00]<br> Superfund Capital Management : Green SPC 2x  :  -8.24% [2.68]<br> DUNN Capital Management : Managed Futures Strategy (Arrow)  :  -8.74% [0.00]<br> DUNN Capital Management : WMA  :  -8.94% [933.00]<br> Schot Capital Limited : Multi Diversified Program Mini  :  -10.26% [1.00]<br> THS Capital Management : Diversified Futures Accelerated Growth  :  -10.45% [2.60]<br> Moddco Capital Associates : MCA  :  -10.76% [0.12]<br> >

Market Neutral

Market Neutral is one of the least volatile strategies, where returns tend to accumulate over time, rather than printing lumpy returns on the upside or downside. Factor performance tends to dominate the average performance, but specific funds can be exposed to particular strategies that are not captured by academic factors. To explore our Market Neutral database, with dynamic rankings, please see Link

Zest : North America Pairs Trading  :  6.70% [33.54]<br> Maverick : QM Neutral (GS)  :  3.49% [394.63]<br> Pictet Asset Management : Agora  :  3.08% [0.00]<br> RAM : Diversified Alpha  :  2.65% [102.24]<br> Perdurance : Market Neutral (Rotschild)  :  2.61% [10.03]<br> Seven : Fortress Fund  :  2.53% [1.91]<br> Aphilion : Aphilion SIF  :  2.33% [45.25]<br> Invesco : Invesco All Cap Market Neutral  :  2.14% [0.00]<br> Blackrock : Asia-Pacific Diversified  :  1.73% [30.39]<br> AQR Capital Management : Equity Market Neutral  :  1.49% [0.00]<br> Fulcrum Asset Management : Thematic Equity Market  :  -1.42% [400.98]<br> Memnon : Market Neutral  :  -1.64% [58.93]<br> JanusHenderson : Global Equity Market Neutral  :  -1.78% [105.68]<br> BNP Theam : Quant Dispersion US  :  -2.03% [119.09]<br> Gotham : Gotham Neutral  :  -2.12% [0.00]<br> QQM Fund Management : QQM Equity Hedge  :  -2.90% [63.90]<br> RAM : Long Short Global  :  -3.57% [34.69]<br> Cognios : Cognios Market Neutral Large Cap  :  -3.68% [0.00]<br> RAM : Long Short European  :  -4.41% [168.32]<br> Crossmark Steward : Equity MN Instl  :  -4.62% [0.00]<br> >

Equity Long/Short

Long/Short Equity strategies had a good start to the year. In particular technology-focused managers with a beta tilt did really well. This is a strategy that is highly expected to do well when the equity beta is positive. To explore our extensive Equity Long/Short list, with dynamic rankings, please see Link

HELSINKI CAPITAL PARTNERS : HCP Focus Fund  :  23.05% [9.60]<br> Alkeon : Equity Long/Short  :  17.42% [57.94]<br> BNP : Environmental Absolute Return  :  15.63% [66.45]<br> Incline : Global Long Short  :  15.28% [8.79]<br> Greenwich Ivy : Global Tactical Fund  :  12.33% [0.00]<br> Prentice Capital Management : Equity Long/Short Conservative  :  12.27% [25.73]<br> RiverPark : RiverPark Long/Short Opportunity  :  11.40% [0.00]<br> Petrus Advisers : Special Situations  :  11.39% [80.57]<br> Coeli Asset Management : Coeli Global Opportunities  :  11.35% [0.00]<br> Prior & Nilsson Fond och Kapitalforvaltning : PriorNilsson Fastighet  :  11.29% [1.70]<br> Forester : Forester Value  :  -3.24% [0.00]<br> Pensum Asset Management : Global Opportunities  :  -4.00% [0.00]<br> Giano : LS Equity (ML)  :  -4.18% [7.73]<br> Coeli Asset Management : Coeli Energy Transition  :  -4.23% [52.00]<br> Clear Peak Capital : UK Long/Short Equity  :  -4.75% [2.95]<br> Counterpoint : Counterpoint Tactical Equity  :  -5.07% [0.00]<br> UBS : Equity Opportunity  :  -6.78% [89.05]<br> Accendo Capital : Accendo Capital  :  -7.19% [296.40]<br> Disciplined Alpha : U.S. Long Short  :  -8.51% [8.59]<br> Thames : Absolute Return  :  -8.70% [204.00]<br> >

Event Driven

As one of the strategies is dependent on equity risk premia but has a low beta to equity markets Event Driven has struggled in the last few years. Several aggressive, highly volatile managers did well, partly based on long positions in selected securities. To explore our Event-Driven list, with dynamic rankings, please see Link

Odey : Special Situations  :  7.62% [78.80]<br> CIAM : Satellite Event Driven  :  5.84% [15.53]<br> Gabelli : Mergers & Acquisitions  :  4.79% [0.00]<br> Camelot : Camelot Event Driven  :  4.71% [0.00]<br> Driehaus : Event Driven  :  3.05% [0.00]<br> York : Asian Event (Lumyna)  :  2.86% [155.83]<br> Gabelli : Gabelli ABC  :  1.99% [0.00]<br> Advent Global : Advent Global Partners (ML)  :  1.70% [154.61]<br> WCM : Alternatives Event-Driven  :  1.55% [0.00]<br> AQR Capital Management : Sustainable Corporate Arbitrage  :  1.33% [75.42]<br> First Private : Systematic Merger Opportunities  :  -0.34% [9.13]<br> Ramius : Merger Arbitrage (Lumyna)  :  -0.44% [67.78]<br> Abrax : Merger Arbitrage  :  -0.65% [40.87]<br> Candriam Investors Group : Risk Arbitrage Opportunities  :  -0.87% [48.79]<br> Weiss Alternative : Monthly Distribution (Dunham)  :  -0.97% [0.00]<br> Cheyne : Cheyne Arbitrage (U Access)  :  -1.42% [94.24]<br> Third Point : Third Point  :  -1.44% [0.00]<br> AllianceBernstein : Event Driven Portfolio  :  -1.59% [174.78]<br> Formue Nord : Fokus  :  -1.60% [79.70]<br> Alpine : Merger Arbitrage  :  -2.63% [244.90]<br> >

Fixed Income

Like Equity Long/Short managers, Fixed Income managers are usually driven by the underlying market conditions. For this list, we typically find managers that are sensitive to a specific subsector, and especially managers that are engaged in the lowest part of the capital structure. To explore Fixed Income managers, with dynamic rankings, please see Link

Secured : Secured Income Fund Plc  :  8.33% [0.00]<br> Axiom : European Financial Debt Fund Limited  :  7.73% [0.00]<br> Nykredit Asset Management : Nykredit EVIRA Hedge Fund  :  5.92% [40.90]<br> Danske Bank Asset Management : Danske Invest Fixed Income Global Value  :  5.82% [786.00]<br> Capital Four Management : Capital Four Credit Opportunities Fund  :  5.45% [278.40]<br> Selwood : Market Neutral Credit (Alma)  :  5.01% [141.33]<br> Bluebay : Emerging Market Unconstrained Bond  :  4.72% [387.47]<br> Boussard Gavaudan : Convertible  :  4.69% [36.66]<br> Manulife : Asian Bond Absolute  :  4.65% [62.45]<br> Lazard : Emerging Markets Debt Blend  :  4.61% [0.00]<br> Excalibur Asset Management : Excalibur  :  -0.32% [92.40]<br> Stadion : Trilogy Alternative Return  :  -0.45% [0.00]<br> Legg Mason : Brandywine Global Credit Opportunities  :  -0.48% [39.82]<br> Redhedge : Relative Value  :  -0.55% [113.57]<br> DLD : Convertable Arbitrage  :  -0.69% [143.15]<br> Schroders : ISF Sustainable European  :  -0.71% [19.90]<br> CQS : New City High Yield Fund  :  -1.93% [0.00]<br> Ironshield : Credit Fund  :  -2.02% [70.07]<br> GCP : Asset Backed Income  :  -3.80% [0.00]<br> SME : Credit Realisation  :  -4.52% [0.00]<br> >

Risk Premia

In a strong month for Equity markets, we noted strong results from managers that load on ERP (Equity Risk Premia) or VRP (Volatility Risk Premia). Several of the strongest result for Risk Premia managers related to those strategies. To explore the Risk Premia managers in the database, with dynamic rankings, please see Link.

Quadriga : Stable Return  :  13.57% [4.79]<br> Catalyst Funds : Systematic Alpha  :  9.26% [0.00]<br> Estlander & Partners : Glacies  :  4.69% [1.20]<br> Neuberger Berman : US Equity Put Write  :  3.21% [562.43]<br> AQR Capital Management : Style Premia  :  2.58% [340.68]<br> Credit Suisse Asset Management : Liquid Alternative  :  1.45% [692.82]<br> Lumyna : Merrill Lynch MCLX  :  1.32% [318.58]<br> GAM International Management : GAM Systematic Alternative Risk Premia  :  1.22% [12.31]<br> AQR Capital Management : Style Premia Alternative  :  1.20% [0.00]<br> Loomis Sayles : Alternative Risk Premia  :  1.08% [20.70]<br> Allspring : Alternative Risk  :  -1.23% [0.00]<br> Allspring : Alternative Risk Premia  :  -1.24% [30.09]<br> Nordea Asset Management : Nordea 1  Alpha 7 MA Fund  :  -1.52% [685.20]<br> BNP Theam : Absolute Alpha  :  -1.75% [14.64]<br> Metzler : Alternative Multi Strategy  :  -1.98% [26.98]<br> Nordea Asset Management : Nordea 1  Alpha 10 MA Fund  :  -2.23% [6132.00]<br> Future Value Capital : Equity Dispersion  :  -3.11% [134.07]<br> Nordea Asset Management : Nordea 1  Alpha 15 MA Fund  :  -3.29% [5559.60]<br> Capital Fund Management : Diversified  :  -3.87% [84.85]<br> BNP Theam : Quant Equity  :  -4.00% [32.98]<br> >

Crypto

Patience paid off for a large set of Crypto Managers and HODLers was rewarded with outsized returns. To explore our extensive Crypto Strategy list, with dynamic rankings, please see Link.

TheCryptoOwl Strategy : THECRYPTOOWL  :  146.2% [0.00]<br> Crush : CCC Crush Crypto Core  :  121.9% [0.00]<br> AbacusBlock Index : ABACUSBLOCK  :  120.3% [0.00]<br> NFT Powered : GRAZZPNONFUNGIBLETOKENS  :  100.8% [0.00]<br> Lavaliere Capital Management : Lavaliere Capital Fund  :  99.84% [28.00]<br> Risky Biscuits : Risky Biscuits  :  90.85% [0.00]<br> IGO Strategy Mate : IGOSTRATEGY  :  86.33% [0.00]<br> Jan Sander Tabak : GRAZZP GRAZZP  :  84.78% [0.00]<br> Blockchain Fund : MIDCAPGROWTHSECTOR  :  83.04% [0.00]<br> SUPER HOW DeFi : DEFIOCEAN  :  74.43% [0.00]<br> FutureProof : POSCRYPTO  :  -0.36% [0.00]<br> BitcoinTradingStrategy : BITCOINTRADINGSTRATEGY  :  -0.53% [0.00]<br> ANB Investments US : Full Strategy Fund  :  -0.75% [27.00]<br> Anchor Crypto Growth Fund : ANCHORGROWTH  :  -1.88% [0.00]<br> Capital PLUS ULTRA Capital : SEMPERINVEST PLUS ULTRA  :  -2.22% [0.00]<br> Rexus Prime : REXPRIME  :  -2.61% [0.00]<br> Algoz Technologies : Digital Asset Fund  :  -2.80% [2.81]<br> Algoz Technologies : Market Neutral  :  -2.80% [2.81]<br> Rational Active Allocation : RAAINDEX  :  -3.14% [0.00]<br> MaiCapital Limited : Blockchain Opportunity Fund SP  :  -3.15% [8.73]<br> >

Past performance is not indicative of future results. This email is intended for sophisticated investors.

  •  

Jack – a man with a talent for numbers

NilssonHedge asked OpenAI to write a short success story for one of our many users. It turned out to be pretty ok. We do apologize in advance for the somewhat chatty nature of this post.

The databases are updated and available for download.

Once upon a time, in a city of finance and business, there was a young man named Jack who was trying to make it big in the world of investing. He had a natural talent for numbers and was always looking for new ways to maximize his returns.

One day, while searching for information on the latest hedge fund trends, Jack stumbled upon NilssonHedge, a database that collected returns and other important information on various hedge funds. He was fascinated by the wealth of available information and quickly became a frequent visitor to the site.

As he delved deeper into the data, Jack realized that there were patterns and trends emerging. He could identify which hedge funds were performing the best and which were struggling. He also discovered that the funds with the highest returns often had certain characteristics in common, such as a focus on trend strategies.

Excited by this new knowledge, Jack decided to start his own fund of hedge funds, and he used NilssonHedge as a valuable resource in building and managing his portfolio. He was able to make informed decisions based on the information he had access to and his fund quickly became one of the top performers in the market.

Word of Jack’s success spread quickly, and soon, other investors and fund managers were seeking out NilssonHedge to help guide their investment decisions. The database became the go-to resource for anyone looking to stay ahead of the curve in the hedge fund industry.

And so, NilssonHedge went from being a small and relatively unknown database to one of the most trusted and respected sources of information in the world of finance. Jack’s success was a testament to the power of data and the impact that NilssonHedge had on the industry.

From that day forward, NilssonHedge remained the standard by which all other hedge fund databases were judged, and its influence continued to grow and shape the world of finance for years to come.

  •  

Adding Additional Indices

We have been working behind the scenes the last few weeks and have created additional refinements when it comes to diving deeper into benchmarking exercises. We have created the following indices:

Correlation Plot for the NilssonHedge Indices

While a lot of the indices are correlated (e.g. CTA Momentum and the Systematic CTA index), the drifts will be slightly different and may be useful for benchmarking style pure managers or understanding specific parts of the market structure.

We are touching up the final classification of the underlying managers and may revise the constituents list in the next few days.

We are also working on adding a β€œVolatility Arbitrage” index which should be ready in a few weeks.

Correlation plot for the NilssonHedge CTA Indices.

The Quant Index has been defined as managers that are engaged in primarily non-trend strategies (AI, Fundamental, Short Term, etc.) and has generally delivered an interesting risk profile. The Discretionary Commodity index is the least correlated to the broader CTA Indices with a correlation of 0.2.

In particular, for investors looking for diversification, the CTA Quant Index has a relatively low correlation to the general CTA index of 0.67. Momentum on the other hand is 0.95 correlated to our broader CTA index.

In other news, we have distributed the first 2023 version of the NilssonHedge database and given the risk-on nature of the month, traditional alternative strategies did really well. Crypto Managers generated a whopping 32% highlighting their Cathie Wood / ARK correlation.

  • We start the year with some 1,267 strategies with data, representing 67% of the strategies in the database.
  • On the CTA side, consisting of a large share of private vehicles 222 managers have reported numbers as of β€œpixel-time”.

If you are interested to explore the structure of our new indices, please head over to our shop and subscribe to the free index data.

  •  

New Members in the NilssonHedge Indices

During the last few weeks, we have been engaged in a number of housekeeping issues. One of them is our index reconstitution. We will be launching several new CTA indices that give additional details for specific sectors.

Every year we reconstitute our indices, a largely automated process, but which involves a fair amount of discretionary oversight to ensure that our indices are representative and relevant. This year, we have some 2900 different strategies in our various composites. Not all managers fit nicely into one composite.

The indices are disseminated through our database, website, partners, and the analytical software packages that NilssonHedge has partnered up with. These indices are generally not proper benchmarks from a regulatory perspective but rather performance indicators.

As a small notice, these indices are not designed to be investable and represent the average return from managers which requires continuous rebalancing. Index figures are updated continuously throughout the month and reflect the current state of the database.

Except for carveouts, there will be no backtracking of the indices. In cases when a new index is launched, it will be based on the historical, actual state of the database as of the launch date. Carveouts (i.e. a separate benchmark based on an existing index; CTA Systematic or CTA Discretionary managers are two examples).

Return data will be continuously updated and will incorporate lagging managers who for various reasons have decided to restart reporting. This may introduce variability in the historical rate of returns.

Remember that NilssonHedge calculates strategy composites based on available data and our individual return stream may not perfectly match the managers’ official track records. We seek to give researchers and allocators a better view of the average investor experience, rather than the asset-weighted investor experience that would be the typical outcome from traditional track records. This may cause minor deviations for particular managers.

Constituents

Every index starts with the index members. Members are selected based on the semi-systematic framework, based on the NilssonHedge classification framework. Below we describe the algorithm for selecting strategies that will form part of an index.

Our methodology for selecting constituents is straightforward and based on the following rules:

  • At the end of January, each year, NilssonHedge isolates the managers and strategies that have reported returns for December, in the prior year. In this case, we need data for December 2022 at the end of this month (January 2023). We put emphasis on timely reporting and disclosure of results.
  • This list remains fixed throughout the year, regardless of the number of new managers in the database. As such, expect the number of managers to gradually decline throughout the year.
    • Given the indices are calculated based on the average, the index is rebalancing toward reporting managers on a monthly basis.
  • There are currently no requirements on assets under management, length of track record, or other qualitative aspects of the underlying firms.
  • The monthly indices are generally not backfilled and represent the out-of-sample results. The exception is if we create a carveout of a particular subindex.
    • For instance, our Discretionary CTA index was launched in 2020, but historical returns were based on the structure and manager classification of the database as of December 2018.
    • In such cases, the indices will include managers that have stopped reporting to avoid survivorship biases.
  • The daily indices have been partially backfilled based on the status of the database. We disclose the β€œgo-live” date for affected indices.

NilssonHedge is discretionarily classifying strategies based on a semi-automated assessment of strategies, based on among other things keywords and potentially additional touch points with added managers. Our keyword search algorithm is similar to the one described in β€œMan vs. Machine: Comparing Discretionary and Systematic Hedge Fund Performance”.

Classification Framework

Some managers are easy to classify, and some other managers are not easy to classify due to their hybrid investment strategy. The classification always involves a certain amount of discretionary judgment.

We classify managers into four different categories:

  • Type: The headline strategy, to name a few: CTA, Crypto, Market Neutral. We may not follow the managers’ self-classification of their own strategy but try to classify them based on our perception of the strategy and how the return stream behaves in terms of volatility, correlation, and betas to markets.
    • As an example, is that our CTA encompasses classical Managed Futures managers, Global Macro managers, and asset managers that may not have registered with the NFA and may thus not formally hold themselves out to be a β€œCTA”.
    • Likewise, we do not have a pure classification for Macro Managers, that may engage in trading of cash securities, swaps, and other instruments that are not typically part of the classical toolbox for a CTA.
  • Style: Here we typically classify a manager depending on their investment framework. The main division is if the manager is systematic or discretionary.
    • As practitioners may have observed even strictly systematic managers have a large degree of discretionary elements, and discretionary traders may use systematic elements or models.
  • Strategy: Based on the specific investment strategy implemented we further classify the return stream into a number of sub-strategies.
    • Trend Following, Fundamental, and AI are sample strategies. The Strategy category is more fluent.
    • Super strategies exist:
      • Quant, a new index, which consists of AI, Behavioral, Contrarian, Fundamental, Market Neutral, Short Term subject to a systematic implementation.
  • Sector: The final classification is based on the sectors a program has exposure to.
    • Super Sector:
      • Commodities consist of all commodity sectors’ specific managers (Energy, Metal, and Agricultural) and managers that may have exposure to all commodity markets without a disclosed focus.

Transparency

Each week, we update the performance of our indices and present them in the below format via the NilssonHedge webpage. Moreover, we disclose the index members, per year. This can be found in a tabular form at the bottom for each Nilsson Hedge index.

  •  
❌