❌

Reading view

Here’s How Blockchain Can Fix Bank Runs

Disclaimer: The following article has been syndicated from its original source, Banking is Broken: How Blockchain Can Fix Bank Runs, with the permission of authors Ivan Hong and Sherry Jiang.

Bank runs are happening at unprecedented speeds. In just three days, we witnessed two of the largest bank failures in American history. Signature Bank, a New York-based regional bank, shuttered suddenly on Sunday, marking the third-biggest bank failure in U.S. history — just two days after the country’s second biggest failure, Silicon Valley Bank.

Despite this, there is a chorus of voices that want us to believe that all is fine in banking. “Americans can have confidence that the banking system is safe”, said Biden. “There is no systemic risk to our financial system”, said Britain’s Chancellor, Jeremy Hunt.

These reassurances are understandable, regardless of their believability. In 2014, rural banks in China’s eastern city of Yancheng stacked piles of cash in plain view behind teller windows to calm depositors queueing at bank branches for a third straight day — following rumors that they had run out of cash. American banking tycoons Marriner and George Eccles, did something similar during the Great Depression to fend off multiple bank runs.

But history has shown that some skepticism is warranted. “We believe the effect of the troubles in the subprime sector on the broader housing market will be limited and we do not expect significant spillovers from the subprime market to the rest of the economy or to the financial system,” declared Federal Reserve Chairman Ben Bernanke in May 2007 — just a year before the Global Financial Crisis — the worst banking crisis since the Great Depression.

While we may not see a wave of bank collapses like in 2008, the rapidity and scale of the run on both Signature and Silicon Valley Bank reveal deep structural flaws with the very design of fractional reserve banking in the internet age.

This is a story bigger than any one bank. Bigger than the failure of risk management. Bigger than economic vulnerability created by the aggressive seesawing between artificially high and low interest rates. It is a story of how fractional reserve banking is fundamentally broken and antiquated.

The Big Con: Fractional Reserve Banking

There is a profound contradiction at the heart of fractional reserve banking. Deposits are liabilities of the bank that must be repaid on demand. But most of those deposits are being loaned out to earn an interest — and those loans have maturities that cannot be recalled on demand. The balance on your bank account statement is an illusion — it isn’t actually there.

Fragility is baked into the very nature of fractional reserve banking, because it creates liquid claims against illiquid assets. Put simply, at any given time banks never have enough money to fulfill their promise to repay all their depositors on demand.

The word “con”, is shorthand for a “confidence trick”. And although we are largely content to forget this inconvenient truth as we go about our daily lives, mere confidence is the cornerstone of banking today.

“The root problem with conventional currency is all the trust that’s required to make it work. The central bank must be trusted not to debase the currency, but the history of fiat currencies is full of breaches of that trust. Banks must be trusted to hold our money and transfer it electronically, but they lend it out in waves of credit bubbles with barely a fraction in reserve”, explained Satoshi Nakmoto in a forum post announcing the Bitcoin White Paper in September 2009.

For the uninitiated, this is not merely the fringe opinion of a techno-anarchist. “Under a fractional-reserve banking system (the system in operation virtually everywhere in modern developed economies), banks have to hold a fraction of their deposits (a liability for them) as deposits at the central bank (called reserves) (an asset for them), but they can “lend out” the remainder”, wrote Paul Sheard, Standard & Poor’s chief global economist.

One of the first modern scholarly analyses of this fundamental contradiction was a paper titled, “Bank Runs, Deposit Insurance, and Liquidity,” written by Douglas W. Diamond and Philip H. Dybvig, published in the Journal of Political Economy in 1983.

Confidence In An Internet Age?

The fall of Silicon Valley Bank is being described as the fastest bank run in history. This is not a coincidence. The banking environment has changed dramatically, and the current fractional reserve banking is no longer compatible with the rapidity of information dissemination in modern society.

The reserve ratio was a concept first introduced in American banking in 1863 to protect depositor funds from being used by banks in risky investments. Federal deposit insurance was pioneered in America in 1934, in an effort to stop the rampant issue of bank runs. Yet, with each passing decade, the use of these tools appear increasingly inadequate to do their one job — prevent bank runs.

In the past, rumors spread by radio, newspapers and television. To demand for withdrawals, depositors had to physically queue and only during the opening hours of banks’ branches. In the internet age, rallies and crashes in financial markets are not only more extreme in magnitude, but also faster. The diffusion of information (reliable or not) spreads at the speed of a 140 character tweet. Furthermore, internet banking has also dramatically shortened the time it takes for depositors to demand withdrawals from troubled banks.

These concerns are not new. Industry observers have been sounding alarm bells as early as 2019. “A digital bank run in a hypothetical future would be much more dangerous as it would happen in seconds and minutes when clients could simply use mobile banking apps to transfer money to another account,” said Susanne Chishti, chief executive of Fintech Circle, in an interview given to Raconteur magazine.

Former Canadian central banker Mark Zelmer’s independent review into the UK’s Co-operative Bank, noted that Open Banking “may come at the cost of less stable deposit-taking institutions”. In the report, Zelmer concluded, saying, “I would not be surprised if smaller institutions find their deposit bases become less sticky over time and more likely to run at the first hint of trouble”.

This remark by Zelmer has now become a shocking reality just 4 years later. SVB, the 16th largest bank in America that has operated for 40 years, collapsed in just a mere 48 hours, when the first hint of trouble around its $1.8B losses on securities soon spread like wildfire over social media and online spaces:

Timeline of SVB’s collapse

  • March 8, 2023: SVB announced that it would sell $2.25B of shares to fix its balance sheet. SVB suffered a $1.8B loss on the sale of long-term bonds, which were decimated in value when the Fed started hiking interest rates, and simultaneously experienced thinning deposits because many startups started withdrawing because of the current macro climate
  • March 9, 2023: Shares of SVB plummeted 60%. SVB tries to calm venture capital investors, but Pandora’s box has already been opened. VCs urge their portfolio companies to pull funds from SVB, Slacks across startup and tech groups start lighting up, and Twitter grows in full force of FUD. “OK I am hearing from dozens of founders about what to do at SVB. It’s an all out bank run.” wrote Howard Lerman on Twitter.
  • March 10, 2023: SVB collapsed, shares were halted, and regulators shut down operations.

In comparison, the previous banking crises of Northern Rock (2007), Bear Stearns (2008), and Home Capital Group (2017) all took place over the course of several months. Northern Rock first sought emergency funding from the Bank of England in September 2007, but didn’t ultimately become nationalized until February of 2008. Bear Stearns started struggling in 2007 when the housing bubble burst, but the rumors around its decline and ultimate shutdown did not come until March 2008.

In just 15 years, the time it took for a bank to collapse went from a few months to just a few days. This unprecedented speed of collapse coming from a digital bank run will not be just an anomaly. It will become the new normal.

Our current model of fractional reserve banking is ill-suited to our networked age. Liquidity crises can very quickly become solvency crises — all of which hangs on the confidence of depositors and investors.

Confidence, as we all know, is an incredibly fragile thing in an internet age. Yet, unbelievable as it may sound, it is in this increasingly frail house of cards, this dangerous con — that we are asked to store our entire life’s savings.

Better Banking Designs

The pursuit of more resilient alternatives to fractional reserve banking has been going on for decades. As early as 1933, a group of economists hatched an idea known as the “Chicago Plan”. They hoped to identify the causes of the Great Depression. Among the culprits they identified was fractional reserve banking.

Their solution? A 1:1 ratio of loans to reserves. The Chicago Plan would not only have subjected checking deposits to 100% reserves, but banks could no longer make loans out of savings deposits. To obtain the capital to make loans, they would have to raise money by equity-financed investment trusts.

Despite generating a lot of interest at the time, the plan fell into obscurity. It resurfaced briefly several years later, following the US recession of 1937–1938, and once more in the wake of the 2008 subprime mortgage crisis.

In March 2015, Iceland published the results of an intensive study that explored the viability of ending fractional reserve banking. The report, commissioned by the prime minister, explored alternatives to the fractional reserve system, including a revival of the Chicago Plan.

It proposed the separation of bank deposits into two types of accounts: (i) interest-free Transaction Accounts kept at the Central Bank, which are not available for banks to invest, and redeemable on demand, and (ii) yield-bearing Investment Accounts which are invested by the bank, and only redeemable at maturity, ranging from 45 days to a few years.

Funds can be transferred from a Transaction Account to an Investment Account. Banks can offer Investment Accounts with different risk profiles, maturity and interest rates, catering to different types of savers.

The Smart Contract Solution

Fractional reserve banking is a walking contradiction propped up by mere confidence. Confidence is increasingly fragile in an internet age where both the circulation of information, and the ability to act happens 24/7, at the speed of a click. Deposit insurance, and reserve ratios — the two primary tools developed to shore up confidence in fractional reserve banking are proving to be increasingly inadequate.

SVB and Signature weren’t the first, and certainly won’t be the last internet-fuelled bank run. There are two possible responses: (i) restrict deposit withdrawals in crises, (ii) restrict lending to prevent crises. The first two are highly unpalatable to depositors and banks respectively.

In every crisis from the Great Depression, to the 2008 subprime mortgage crisis, to Silicon Valley bank — robust alternatives to fractional reserve banking have been proposed, but not implemented. Largely because private individuals lacked the tools to build alternatives to commercial banks, or central banks.

Today, the advent of DeFi and cryptocurrency has changed that. We now have in our hands, the tools to seize a historic opportunity to build an on-chain alternative to fractional reserve banking.

This is one example of how a design might work.
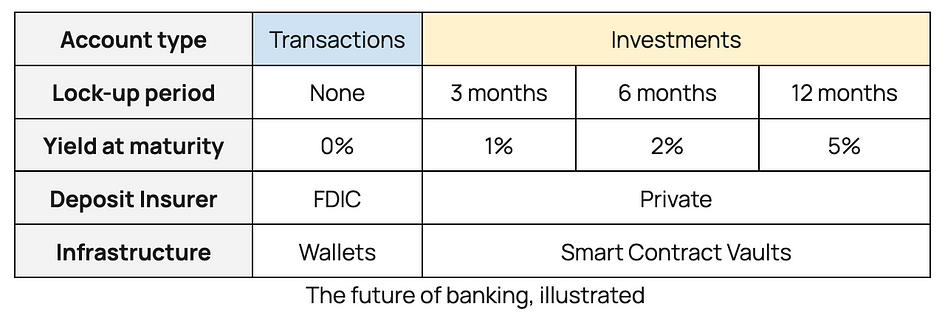
This design will eliminate the creation of liquid liability claims against illiquid assets, and prevent bank runs — without having to eliminate banks’ ability to make loans, or impose deposit withdrawal limits in times of crisis.

By separating liquid funds (e.g., “checking account”) that people use for transactions from funds people are willing to risk more for investments, this design provides transparency and assurances that people’s funds are actually safe being kept safe and not being commingled for other purposes. In addition, because liquid assets are being held in self-custody solutions like wallets, there is no need to have trust in another third party like a bank.

All of these features can be automated, and enforced via smart contracts. It removes the need for attestation or independent audits, and minimizes the difficulties of banking supervision and oversight.

Conclusion

What has occurred over the past week with Signature and SVB hopefully will spur a re-examination of our current banking system at a foundational level.

While on-chain finance and DeFi are still in their nascent stages in technology and economic design, they have the enormous potential to solve the deep structural issues of our banking system and create a new one more compatible with our modern digital society.

[Editor’s Note: This article does not represent financial advice. Please do your research before investing.]

Featured Image Credit: Sherry Jiang
  •  

Why Real-World Assets (RWA) Are The Key To DeFi’s Future Growth

The Transformative Potential of RWAs

The Real World Assets (RWAs) narrative is heating up, and this could be the pivotal moment for the mass adoption of crypto and blockchain. It is common knowledge that TradFi is plagued by antiquated and fragmented technology, resulting in an inefficient fiat banking and securities system. The inevitable tokenization of real-world financial assets seeks to remedy this long-standing problem as TradFi, and physical assets are represented as digital tokens on-chain. 

Asset tokenization represents the conferred rights of ownership to physical and financial assets as digital tokens on-chain. The tokenization of real-world assets enables them to be traded with greater ease,  faster settlement and reduced costs with self-executing smart contracts, increased transparency and improved liquidity for traditionally illiquid or semi-liquid financial instruments.  

Crypto Narratives Alpha Series 💎 04

The Real-World Asset (RWAs) narrative in DeFi is grossly underrated.

The question is, are you paying attention?

Here's a deep-dive into RWAs, and some emerging players to add to your watchlist: ↓🧵

— Viktor DeFi 🛡🦇🔊 (@ViktorDefi) February 13, 2023
Notable Protocols that have made significant strides in Adopting RWA

Notable Protocols That Have Made Significant Strides In Adopting RWA

1. MakerDAO

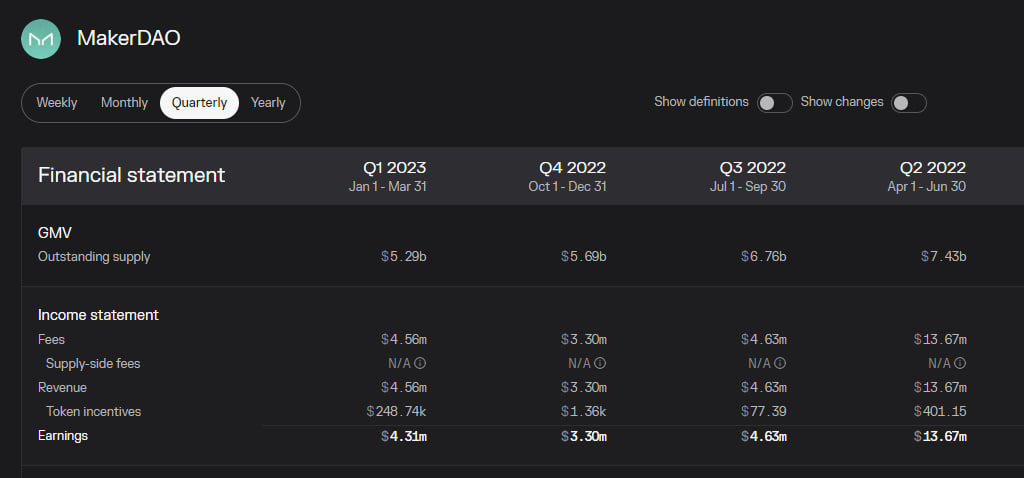
MakerDAO is a blue-chip DeFi project that hardly requires any further introduction. In the past year, MakerDAO has actively worked on diversifying its reserves and establishing other revenue streams. RWAs account for 75% of their revenues and have accumulated over US$600M in RWA collateral.

Key milestones for them include their US$10M partnership with Huntingdon Valley Bank where RWAs are bridged and serve as collateral when lending out DAI, and the recent partnership in December 2022 with Block Tower to fund US$220M of real-world assets via Centrifuge. 

2. Ondo Finance

Ondo Finance announced tokenized funds that allow users to be shielded from crypto’s volatility and earn sustainable returns. These tokenized funds enable stablecoin holders to invest directly in TradFi instruments through three separate RWA funds, subject to fees of 0.15%.

The Ondo Short-Term US Government Bond Fund (OUSG) invests in short-term US treasuries through the Blackrock US Treasuries ETF (SHV), the Ondo Short-Term Investment Grade Bond Fund (OSTB) invests in investment-grade corporate bonds through the PIMCO Enhanced Short Maturity Active ETF (MINT). In contrast, the Ondo High Yield Corporate Bond Funds (OHYG) invests in high-yield corporate bonds via the Blackrock iBoxx $ High Yield Corporate Bond ETF (HYG).

Ondo Finance Strategy (@Airdrop_Adv)

Ondo Finance’s goal is to make institutional-grade financial products and services available to everyone, on-chain.

They raised $30M
Token confirmed, airdrop teased.

Requirements: Supply USDC or DAI, Borrow when available https://t.co/AQwM8Pp5TO

— Shiro (@CryptoShiro_) March 1, 2023

3. Maple Finance

Following defaults and a radical overhaul, Maple Finance has distanced itself from uncollateralized lending and leaned towards RWAs to make a comeback.

They removed traditional DeFi over-collateralization thresholds for borrowers as long as they have RWAs to back their debt. Maple has partnered with London-based AQRU to devise new pools that invest in US Treasury bonds and insurance refinancing with yield-generating strategies adopted from TradFi.

Maple provides the blockchain-based technology required to set up and maintain the pool, whereas AQRU is responsible for managing the pool and loan book. For a start, the new pool has a target yield of 10% per annum with a minimum notional of USDC 500k and a 45-day lockup period.

To align with regulatory requirements, the pool will be available only to accredited investors such as asset managers and DAO treasuries that comply with KYC/AML standards.

4. Phuture Finance

Phuture Finance is building one of the largest crypto index funds, it leverages traditional index funds to create one of the largest decentralized crypto index funds. Phuture Finance has three core products, Phuture DeFi Index (PDI), Colony Avalanche Index (CAI) and USDC Savings Vault (USV).

Similar to how traditional index funds are structured to provide investors with exposure to a financial market index instead of a single stock to diversify risks, PDI and CAI are market capitalization-weighted indexes that offer exposure to the top DeFi protocols in the Ethereum and Avalanche ecosystems, respectively.

USV is a vault that generates interest on depositors’ idle USDC. $PHTR is the native token primarily used for governance and incentivizing users.

Mass adoption is coming to crypto, but it’s only a matter of when

Indexes are going to be huge and few players are already taking advantage of that.

Want to know who I'm betting on, Find out 🧵

— DeFI Saint 🦇🔊 (@TheDeFISaint) January 26, 2023

5. Backed Finance

Backed charges on the issuance and redemption of assets are held in designated collateral accounts with their custodian. Backed serves as a service provider and does not engage in any form of investment activities, their primary target group is also accredited investors.

Backed currently does not have a native token and has no plans to launch one. The platform went live recently and received an overwhelming response for its first token, the Backed Core S&P500 or bCSPX. The tokens are expected to be fully collateralized by the underlying assets and fully transferable.

"DeFi cannot grow its collateral assets by 100x without RWAs. The securities market, which is over a $100 trillion market, offers the potential for much greater growth."

— Aylo (@alpha_pls) March 1, 2023

Conclusion

Global institutions such as Goldman Sachs, Siemens and KKR strive to bring traditional real-world assets on-chain. This bodes well for the crypto and blockchain industry, as these assets are worth trillions of dollars. If done right, mainstream adoption of crypto and blockchain is no longer a far-fetched dream. 

However, it is noteworthy that TradFi is a highly regulated industry, and greater regulatory clarity is critical to propel financial asset tokenization forward. It is a win-win situation for both TradFi and DeFi, DeFi gains by having another source of collateral option for lending protocols which can, in turn, improve liquidity and mitigate risk, while TradFi benefits from increased liquidity and efficiency as lower operational costs.

Also Read: Why Real-World Assets Are Needed For DeFi To Succeed

[Editor’s Note: This article does not represent financial advice. Please do your research before investing.]

This article is done by our freelance writer, Clarence Lee

Featured Image Credit: Chain Debrief 

  •  

The Shocking Truth About Bitcoin’s Limited Supply

Over the last few years, Bitcoin established a key narrative for itself as an inflation hedge. The narrative became especially strong during the Covid-19 pandemic, which saw M2 money supply in the United States more than double over a few years.

However, with the orange coin’s prices tumbling over 70% since it’s all-time-high, some have dismissed the its labels as an “inflation hedge” as nothing more than a marketing slogan.

Often termed “digital gold”, Bitcoin seems to have failed in this aspect, despite inflation numbers across the globe coming in at record highs. So why do people still cling on to this seemingly lost narrative of Bitcoin as an inflation hedge when it has seemingly underperformed all expectations?

Also Read: NFTs Are Exploding … On The Bitcoin Network

Understanding Exactly How Scarce Bitcoin is

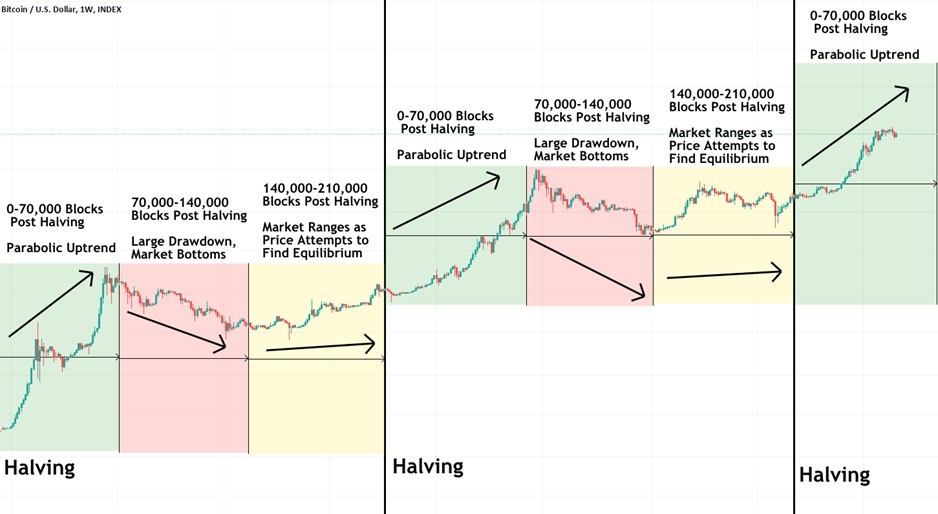
By now, most of us know about the Bitcoin “halving” cycles, which occur approximately once every four years. During halvings, rewards paid out to Bitcoin miners are halved, which decreases the new supply of Bitcoin and has historically led to bull rallies.

Image Courtesy: Dan Leclair via Bitcoin Magazine

However, it is truly difficult to fully contextualize how effective the halvings are.

Did you know, for example, that more than 90% of all Bitcoin have already been mined? As stipulated in the Bitcoin whitepaper, only 21 million Bitcoin will ever exist, of which 19.3 million, or 92%, area already in circulating supply.

From the time of writing (6th March 2023) till the next halving approximately 400 days later, there will be 60,438 blocks mined, with a reward of 6.25 Bitcoin per block for a total of ~370,000 Bitcoin.

In terms of dollar value, that translates to ~$8.5 billion, barely a third of the average daily Bitcoin trading volume in the last few months.

By 2048, 99.9% of all Bitcoin would have been mined, with the last 0.1%, or 21000 Bitcoins being mined over the next 100 years. The last Bitcoin itself will be mined over a period of 40 years.

Bitcoin Dormancy Surpasses Available Supply on Exchanges

As whales, institutions, and entire countries continue to allocate toward long-term Bitcoin holdings, the available supply for trading continues to dwindle across exchanges.

Image Courtesy: Glassnode

As Bitcoin continued to crash, whales begun accumulation, especially at the $16,000 to $20,000 range, with more than 60,000 Bitcoin added by smart money in just the last 3 months.

Image Courtesy: Glassnode

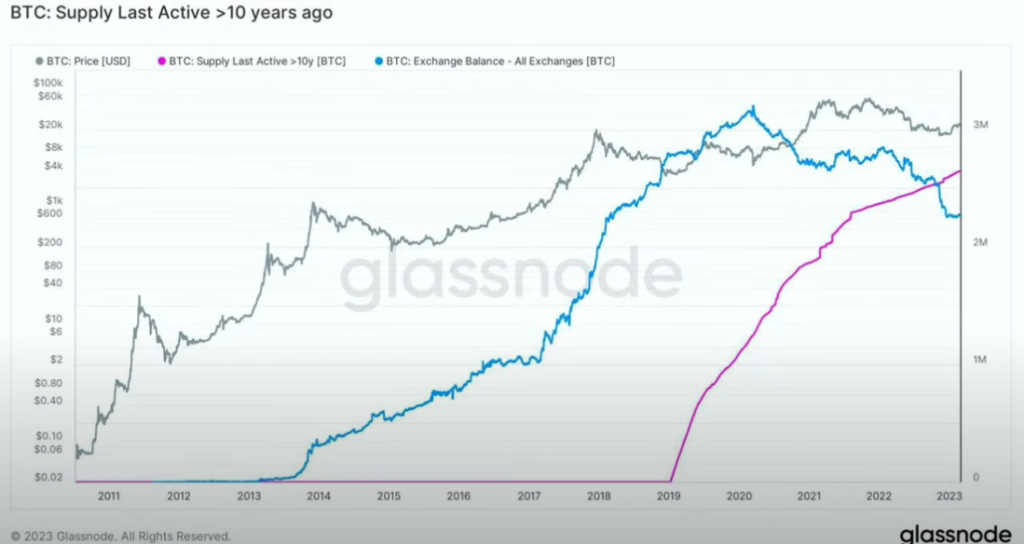
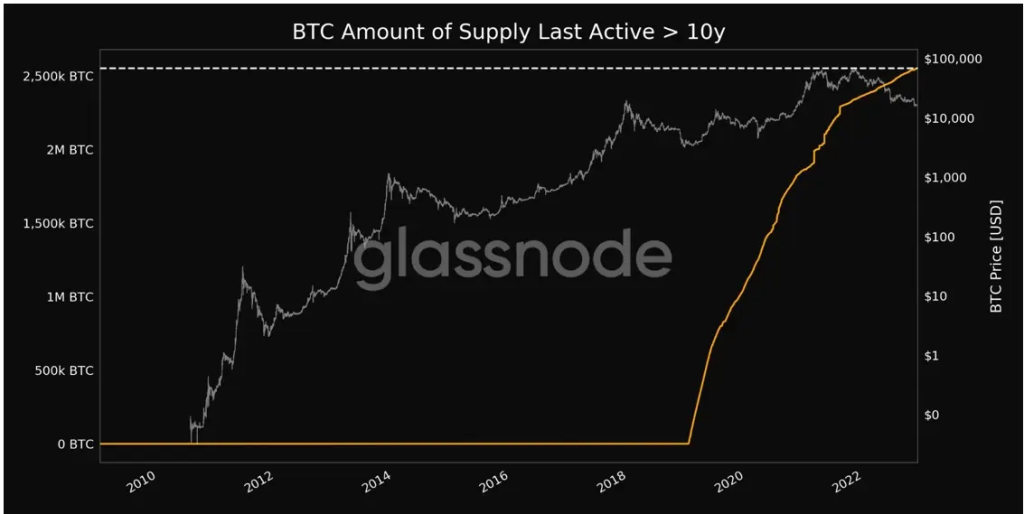
Furthermore, the amount of Bitcoin that has remained dormant for a decade or longer recently passed available Bitcoin on exchanges, at 2.5 million Bitcoin. This includes the original 1 million Bitcoins mined by Satoshi Nakamoto, the pseudonymous creator of Bitcoin, that since remained untouched in over a decade.

At the time of writing, the approximately 2.5 million Bitcoin translates to 13.2% of supply, which some analysts suggest could never be reactivated again. This could be due to multiple factors, such as the loss of private keys, passing on of the owner, or incorrect tranasctions.

It looks like that with the deaths of Mircea Popescu and John McAfee a significant amount of $BTC might be lost forever.

RIP https://t.co/8KGPows3Kh

— Alexander Mardar (@amardar1) June 28, 2021

High-profile cases such as known Bitcoin billionaire Mircea Popescu’s passing and TV personality Alex Jones losing 10,000 Bitcoins are just some of the many instances where Bitcoin is permanently taken out of the circulation.

Image Courtesy: LookintoBitcoin

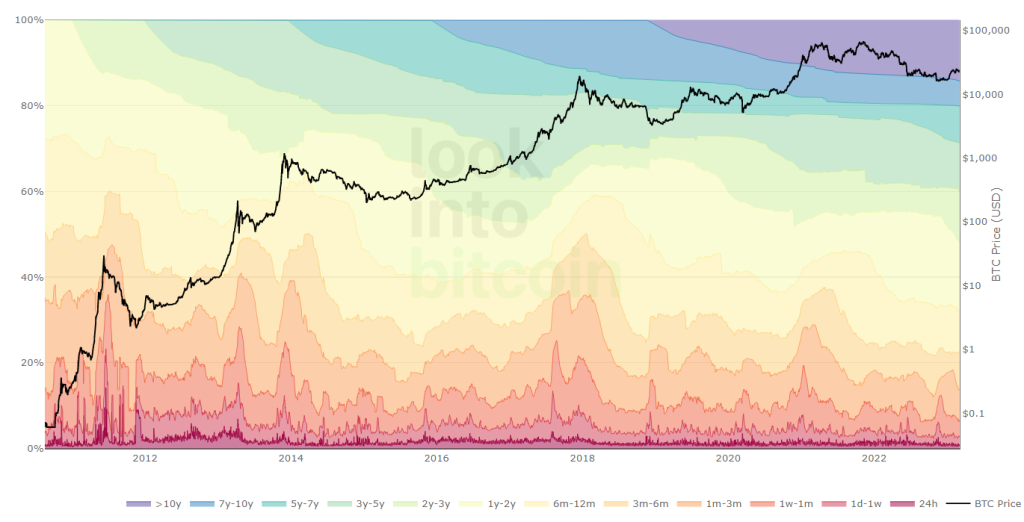
Interestingly, approximately 6 million Bitcoin, or ~30% of circulating supply, has not moved in the last 5 years or more. While we cannot expect all 6 million of these coins to remain dormant forever, it is likely that a significant amount of Bitcoin will continue to be taken out of the circulating supply every year due to various reasons.

Can Bitcoin Hold The Narrative as an Inflation Hedge?

This article speaks mostly to the scarcity of Bitcoin and the theoretical reduction of circulating supply over time. Equally as important (or even more so), is of course the demand for Bitcoin.

The leading cryptocurrency has increasingly fallen out of favour from both retail and institutional investors due to it’s lack of smart contract support, which prevents key aspects of Web3 such as smart contracts and DeFi to function on the blockchain.

However, advances in technology regarding Bitcoin are being made in strides, and the recent hype around Bitcoin-native NFTs, named ordinals, have landed them a valuation of $4.5 Billion by 2025.

Furthermore, the inflation hedge narrative does not necessarily have to be the only driving force for Bitcoin’s demand. The leading cryptocurrency still remains the de-facto method for many institutions and companies to gain exposure to Web3, due to how straightforward and simple it is.

SEC Chairman Gary Gensler: Everything other than #Bitcoin…[is a security].

— James Lavish (@jameslavish) February 26, 2023

Additionally, the SEC, chaired by Gary Gensler, seems to be taking regulatory action against every cryptocurrency under the sun, except for Bitcoin. This could be a major driver for institutional investors to allocate toward Bitcoin instead of other cryptocurrencies to remain compliant with U.S regulations.

Also Read: We Asked 5 Industry Leaders For Their 2023 Market Outlook

[Editor’s Note: This article does not represent financial advice. Please do your own research before investing.]

Featured Image Credit: Chain Debrief

  •  

Why Real-World Assets Are Needed For DeFi To Succeed

After looking into many crypto predictions in 2023, one narrative stood out. Real-World Assets (RWA). Yet, it continued to live within the shadows of many other narratives even when poised to bring users the biggest value.

The pursuit of dog coins and animal pictures has often diluted the true purpose of crypto; yes, I agree they bring adoption in a certain way, a community spirit, some may say, but when markets take a turn for the worst, what use do they all have?

Since 2020, the emergence of L1 tokens has gained significant attention. But it almost seems “just a capital rotation game, it creates no real inherent value.” This results from a pure and trustless DeFi ecosystem without a connection to the real external world.

The point of crypto is to improve society, which means providing products/services that people actually want in a superior format

In regards to finance, this means RWAs (traditional commodities, currencies, and securities)

Without RWAs, what exactly do we aim to achieve here?

— ChainLinkGod.eth (@ChainLinkGod) January 23, 2023

What is RWA?

It essentially refers to assets of value in the real world (real estate, traditional securities, commodities etc.) being tokenized and represented on a blockchain, allowing them to be traded and transferred in a digital form.

Tokenizing real-world assets unlocks cashflow unaffected by Crypto’s volatility, and many RWA protocols have caught many institutional investors’ attention.

I am excited about the promise of crypto unlocking global liquidity, and providing RWA for customers globally in ways that traditional fintech institutions are constrained. Focusing on “0-1” access to financial instruments, as opposed to incremental access, will do well.

— Chia Jeng Yang (@chiajy2000) January 25, 2023

RWA is here, but still undiscovered

Token Terminal

Based on the cumulative fees among the top 10 lending protocols over the past 180 days, four of which consist of RWA lending protocols (TrueFi, Maple Finance, Goldfinch, and Centrifuge).

The mechanics of the most prominent players in DeFi, such as AAVE and Compound, depends heavily on leverage. RWA, on the other hand, offer under-collateralized lending outside the circular crypto world.

Why undiscovered? RWA protocols are all below a $100M circulating market cap. To put things into perspective, the almighty Dogecoin has little to no value and a market cap of $11B.

We have to bridge a huge gap before we see its success, but that leaves plenty of leg space for RWA to grow. If RWA is already good, it’s only about to get better.

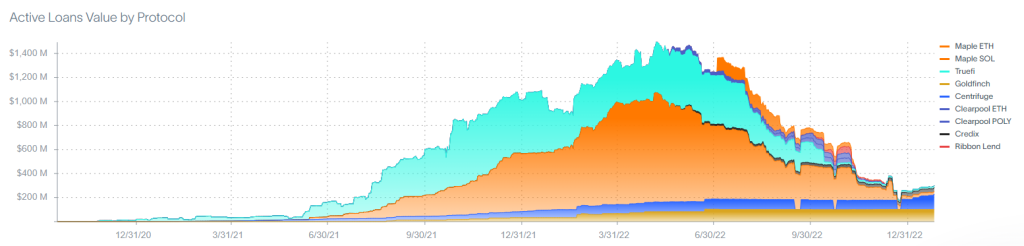
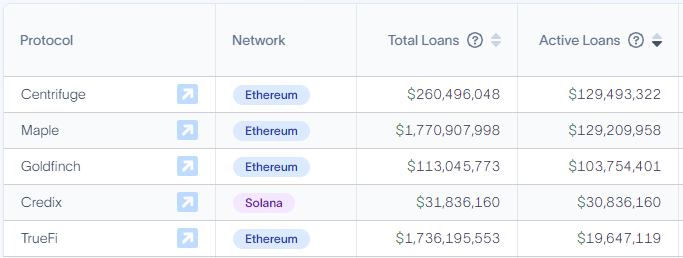
According to rwa.xyz, the value of the active loans recently surpassed $415M, with the cumulative value of all loans reaching $4.4B.

rwa.xyz

The race towards the RWA throne has been competed by five protocols, with Centrifuge leading the charge.

rwa.xyz

Greyson Alto on Twitter did a pretty decent analysis on RWA based on data provided by rwa.xyz. He looked into the trends of based interest rates of new loans to the percentage and amount of non-current loans that have defaulted.

Furthermore, he found out that six out of the seven protocols have a listed native token. Using the active loan amount as a relevant driving variable to price ultimately drives revenue.

Looking into the loan-to-market cap ratio also provides value by looking horizontally over time rather than trying to compare protocols vertically. “For example, Centrifuge and Goldfinch have very positive value trends, while TrueFi and Maple show troublesome trends over time.”

2023s top blockchain narrative, RWAs in the form of private credit, is rapidly growing in terms of sentiment, education, and value created

I continue to look further, this time going through data from @rwa_xyz on 1,400+ loans

Below are several insights🧵

lmk your thoughts/

— Grayson Alto (@AltoGrayson) January 25, 2023

With an average APR of 11.66%, here is a breakdown of active loans by sector. The top 3 sectors are Fintech, real estate and carbon projects.

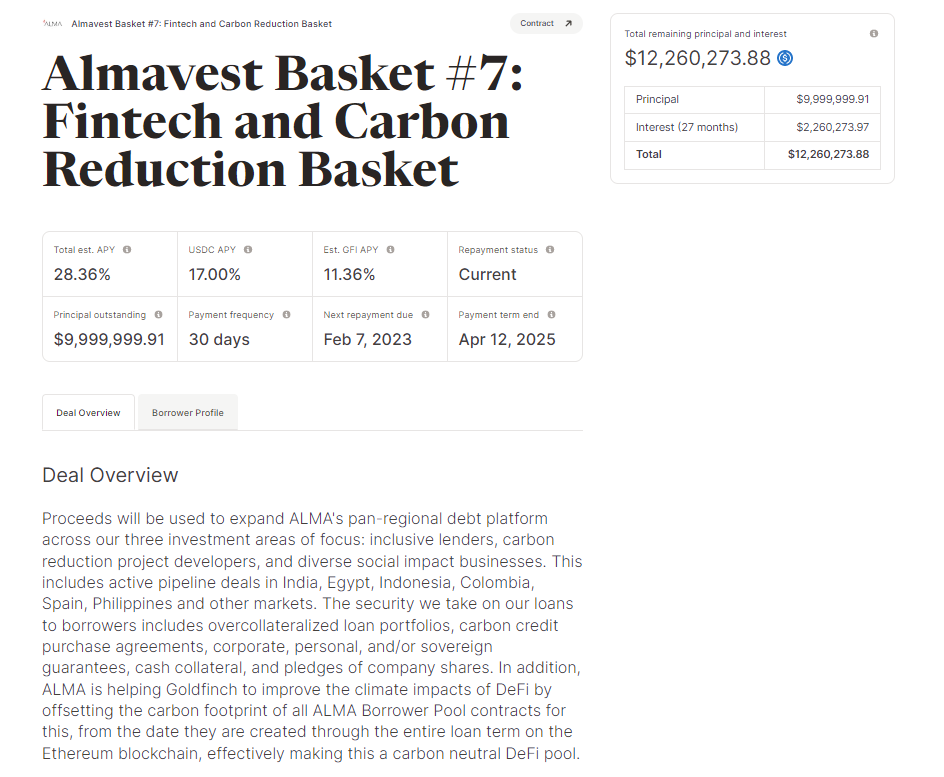
Goldfinch’s carbon project yielding 27% APY

We talked about Goldfinch in our previous article. They are a decentralized lending protocol allowing crypto borrowing with off-chain collateral. It targets emerging markets and aims to bring the world’s credit activity on the chain.

One of the many baskets they have is managed by Alamvest, which focuses explicitly on Fintech and Carbon reduction. It is essentially a credit fund that deploys capital for sustainable development into high-growth, impact-oriented companies in emerging markets.

Another basket, managed by Cauris, is the Africa innovation pool, which currently provides a 28.53% APY with 17% USDC APY.

This may be a good alternative for generating yield through tokenizing real-world assets, but it has certain downsides and risks.

The risk

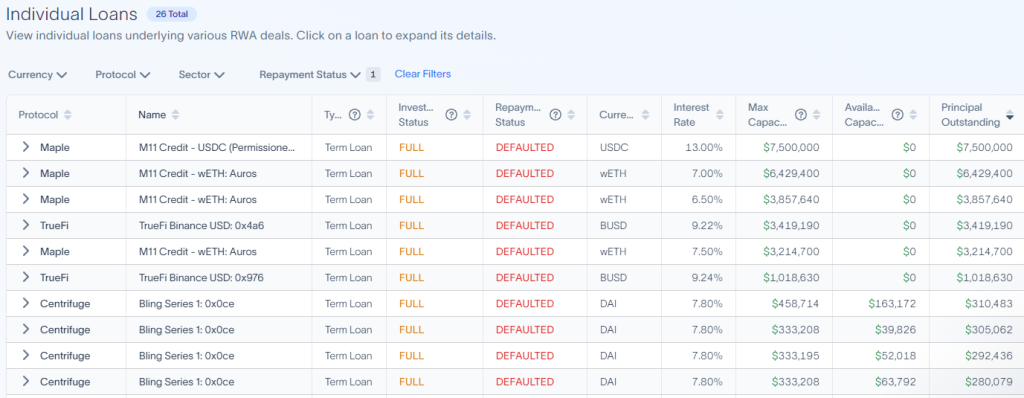
By looking at the total defaulted loans by protocol, Maple has the highest score of $68M. This was mainly due to the contagion spillover with the collapse of FTX, where creditors on Maple defaulted their loans.

Read more about how Maple Finance Found Itself In A Sticky Situation.

Defaulted loans – A default on debt happens when a borrower fails to repay the funds according to the initial agreement.

When a loan defaults, protocols in varying approaches would either stop supplying more capital to any of a Borrower’s pools or kickstart a liquidation mechanism.

In the case of Maple, their 2.0 upgrade is aimed at handling defaults more quickly by the loan managers, aka pool delegates, who would be the first ones to take the loss in the event of a default.

On the other hand, Goldfinch mitigates risk through a system of auditors who vote to approve borrowers and a mandatory “unique entity check” for all loan participants. This will come in the form of SBT, Soulbound tokens, basically a non-transferrable NFT.

TrueFi utilizes portfolio managers who independently manage their funds and make lending decisions, including setting loan terms with borrowers. To become a portfolio manager, any applicant would need to go through the approval of TrueFi governance.

Hopefully you've heard of #TrueFi, our upcoming uncollateralized DeFi lending platform, by now. 👀

Here's a TL;DR on how it works 👇 pic.twitter.com/Olobz6d9na

— TrueFi (@TrueFiDAO) November 18, 2020

RWA Case study: MakerDAO and a Huntingdon Valley Bank

As of August 2022, the Maker Protocol has amassed over $600 million of real-world asset collateral. One significant milestone is the Huntingdon Valley Bank (HVB) partnership. They pioneered the first commercial loan participation between a U.S. Regulated Financial Institution and a decentralized digital currency.

HVB, impressed by MakerDAO’s access to deep DeFi liquidity, proposed a partnership to fund 100M DAI. The partnership with Huntingdon Valley Bank (HVB) allows MakerDAO to put their idle DAI to work, real-world bridge assets, use RWA as underlying collateral when lending DAI and leverage HVB’s established regulation with the government.

The first collateral integration from a US-based bank in the DeFi ecosystem is getting closer.

The Maker Governance votes to add RWA-009, a 100 million DAI debt ceiling participation facility proposed by the Huntingdon Valley Bank, as a new collateral type in the Maker Protocol pic.twitter.com/fOdusdjCFS

— Maker (@MakerDAO) July 4, 2022

Here’s a TLDR on how the partnership works

-HVB sends loan requests to MakerDAO’s trust “Ankura.”

-Ankura approves or disapproves of them.

-When approved, HVB can access funds from the RWA Master Participation Trust.

-Interest generated from the loans is split 50/50 between the two entities.

According to Messari, despite accounting for a relatively small portion (12%) of MakerDAO’s balance sheet, RWA generates a significant amount (nearly 60%) of the protocol’s annual revenue.

Closing thoughts

The market faces fierce competition, and with crypto falling behind AI in mindshare, it becomes clear what crypto has to do. That is, creating clear value for consumers is clear, and it is by no means impossible.

RWA would be the likely answer. We saw DeFi had proliferated in recent years, with its TVL rising from 0 to a high of 60 billion. Still, including RWA in DeFi could improve liquidity and risk profiles in the market, bringing more reasons for people to get into DeFi.

As interest in crypto leverage decreases and interest rates in the real world increase, Real-World Assets (RWA) are becoming more prominent as a potential opportunity for DeFi users to incorporate into their portfolios and access different asset classes.

RWA protocols aim to provide capital to real-world businesses and expand the possibilities of DeFi, but this comes with its own set of challenges, namely regulation. Success in RWA will depend on obtaining legal licenses and addressing the lack of legal enforcement, which currently hinders the growth and tokenization of underlying collateral in the space.

Despite these challenges, the potential for RWA is clear.

Also Read: I Looked Into The Historical Cycles Of Crypto, Here’s What I Found

[Editor’s Note: This article does not represent financial advice. Please do your own research before investing.]

Featured Image Credit: Chain Debrief

  •  

5 On-Chain Indicators To Spot Crypto Market Bottoms

To buy or not to buy? That is the question. The short answer to that is nobody knows. I buy the dip, and the dip dips even more; when I choose to wait for the dip to dip, the market pumps. No lunch is ever free, but today we look into on-chain indicators which may, but not guarantee, help you spot crypto market bottoms.

While timing the bottom is a straightforward and simple concept, most of us WILL not get it right. Instead, experts suggest a lazy but effective approach to making money: dollar cost averaging. But the DCA approach takes time, and timing the bottom seems faster. You probably clicked on this article for that very reason.

1. On-Balance Volume (OBV)

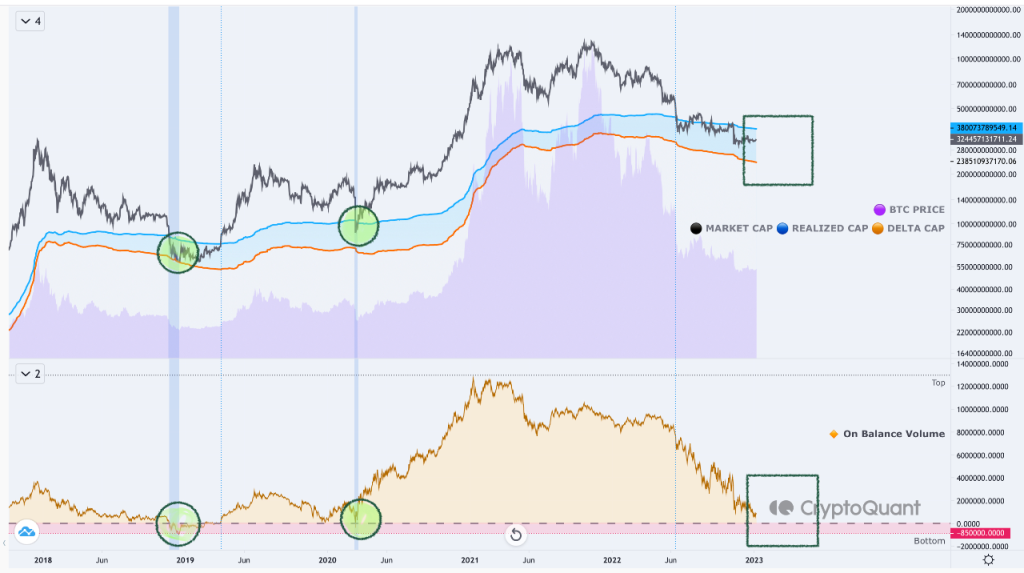
The first indicator which may help you identify a possible market bottom is referencing the price with on-balance volume. OBV measures buying and selling pressure as a cumulative indicator that adds volume on up days and subtracts volume on down days.

This bangs on the fact that the volume will correlate with the price movement. If the price of an asset goes down, so will the volume similarly, and vice versa.

Judging from past cycles, the market bottomed out when the market cap fell below the realized cap, and the OBV indicator reflected values close to zero. Reversals and market recovery began when the market cap touched the delta cap and OBV index dropping below zero.

CryptoQuant

2. MVRV Ratio

We have gone through the MVRV ratio on our technical thursdays segment on IG, head over for a refresher.

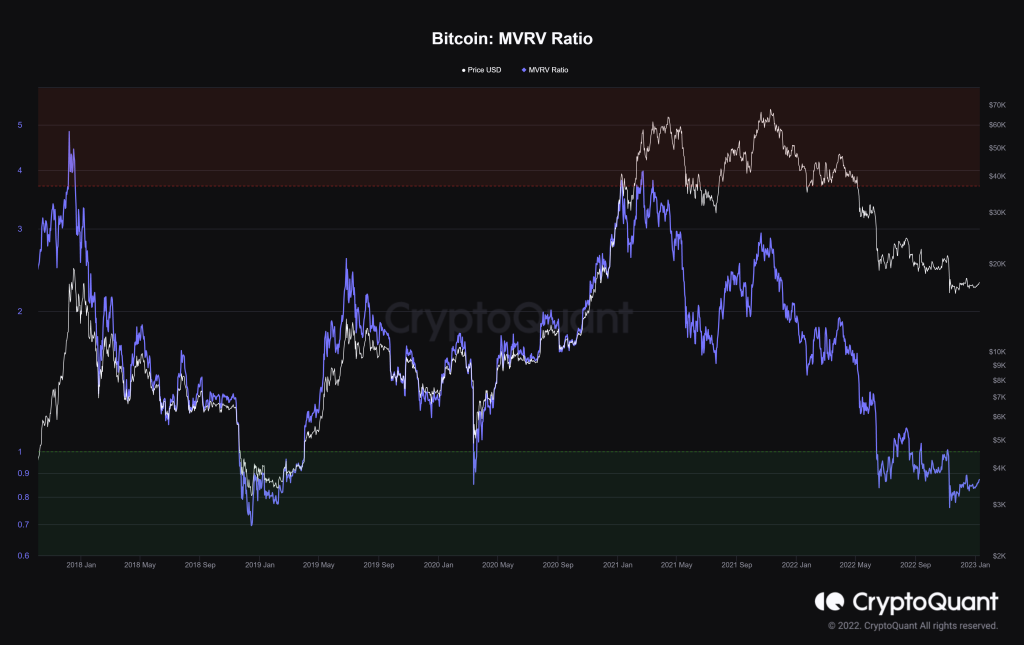
MVRV, known as market value to realized value, refers to the asset’s fair value. It is often used to identify market tops and bottoms, reflecting periods of extreme investor unrealized profit/loss.

The BTC MVRV charts have fallen to their lowest levels in three years. Currently, we are hovering around the range at the bottom. Historically, values over ‘3.7’ indicated the price top and values below ‘1’ indicated the price bottom.

3. All Exchange Inflow (mean)

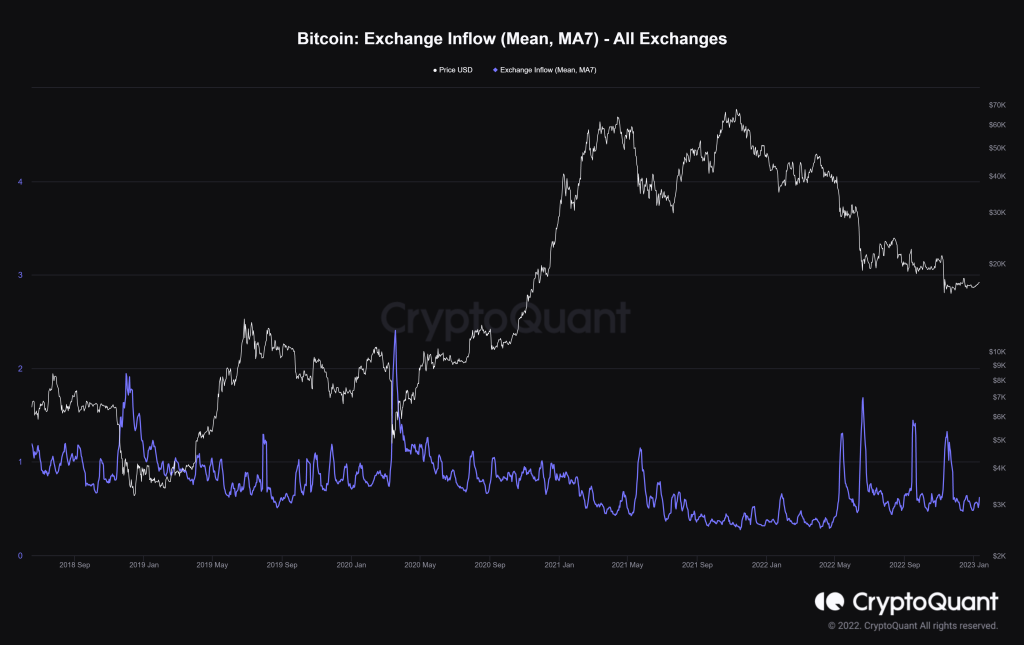
Exchange flow is the number of coins deposited into the exchange wallets, and exchange outflow is the number of coins withdrawn from exchange wallets.

A high value indicates investors are sending a greater number of coins in a transaction. It will also likely lead to higher selling pressure which could lead to a future price drop.

Here is a glimpse of how you are able to buy BTC at global bottoms. Historically, when BTC sees over a 30% plummet or more, the all-exchange inflow (MA7) will likely have a sudden spike to the exchange inflow range of close to 2 and/or higher. You take your entry positions after the indicator cools down, historically a signal for market bottoms.

From the chart above, if you were to follow this strategy, you would have ridden the massive wave in price surge twice. 2022 showed quite an anomaly, with the all-exchange inflow spiking and cooling off on four consecutive occasions, it does not seem we have reached the bottom yet, but a great range to accumulate.

#Ethereum price tops and bottoms are defined by coin flow
by @joao_wedson

Link👇https://t.co/y0b47kBLU8

— CryptoQuant.com (@cryptoquant_com) January 9, 2023

4. Stock to flow

Crypto has its very own stock-to-flow model too.

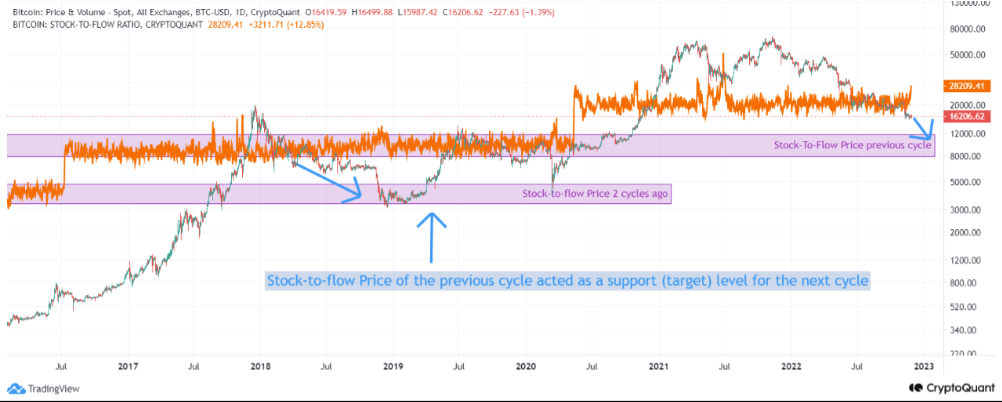
In the 2018 cycle, Bitcoin’s downtrend finally stopped after breaking out of the previous Stock-to-flow price cycle.

The stock-to-flow model measures the new supply relative to the existing supply. As the name suggests, Stock refers to the total existing supply, while the flow is the new supply of an asset created yearly. 

While this measures and compares the relative abundance of scarcity, could it signal us to head out of these choppy waters? Maybe, maybe not.

CryptoQuant

If the aforementioned is going to be true, we have yet to see the worst of the markets; a larger storm is incoming. This very storm will take BTC to $8-11K levels which will not only spells disaster but spiral crypto markets into complete fear.

5. BTC BVOL, Historical Volatility

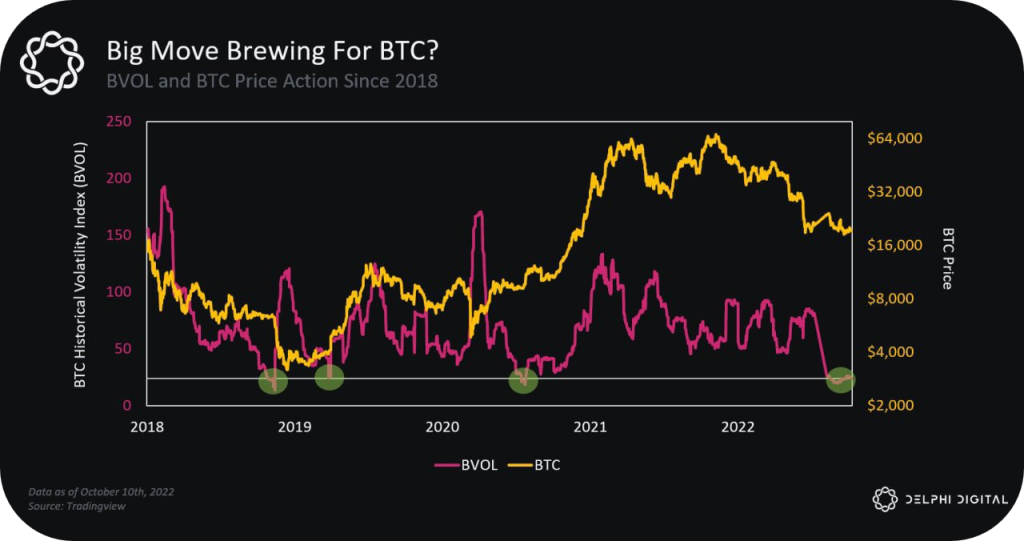
BVOL is the measure of Bitcoin’s historical volatility. The higher the BVOL score, the more volatile and riskier BTC as an asset is. The market trading sideways would likely lead to a lower BVOL score.

A low BVOL score is usually followed by an explosive move in price in either direction. Since 2018, Bitcoin has only been reduced to low levels of volatility only four times. Currently, we are in one of those times. 

Could we see another leg upwards? Or do we continue to search for the bottom?

Closing thoughts

Honorable mentions, SOPR ratio.

Market bottom detection by SOPR ratio
by @ghoddusifar

Check👇https://t.co/6ZOIFoUTXy

— CryptoQuant.com (@cryptoquant_com) April 19, 2022

These indicators are not set in stone and are not 100% guaranteed success. Although they give you an idea of where the current market is referencing historical bottoms, timing the bottom is still difficult.

Instead, with the identified “bottoming” range we are currently at, it gives you a perfect time to accumulate a dollar cost average and ride any waves when the market is ready.

I think 2023 will be the year of a cool down, and we only see a significant upside in the tail end of it.

Also Read: The Rise And Fall Of Crypto Lending: What Went Wrong

[Editor’s Note: This article does not represent financial advice. Please do your research before investing.]

Featured Image Credit: ChainDebrief

  •  

What Is EigenLayer And How It Might Revolutionize Ethereum

Ethereum has built an empire of greatness, the home to innovative DeFi products, a large canvas for NFTs and where smart contracts are popular. Doing it all in a decentralized manner has its tradeoff, speed and security. While the layer2 scaling solutions are a scaling force to be reckoned with, EligenLayer found an innovative way to revolutionize Ethereum.

What is Eigen?

Eigen enables users to restake their ETH and extend cryptoeconomic security to additional applications on the network. The Eigen smart contract layer will automatically re-stake your ETH by setting withdrawal permissions and enhancing security by validating new applications built on Ethereum.

Staked ETH is currently yielding around 5-6%

But imagine you could use this staked ETH to secure other projects and earn even more yield on your ETH?

A 🧵 on @eigenlayer by @WestieCapital pic.twitter.com/6BKhMSJoxC

— Blockworks Research (@blockworksres) October 18, 2022

Sounds like a perfect win-win for any ecosystem.

To be an Ethereum validator, you are minimally required to commit 32ETH. Still, EigenLayer allows this commitment to secure Ethereum’s proof of stake and other applications services such as Oracles and bridges.

And get this, it does all that AT THE SAME TIME.

But why? As you will not only be securing the Ethereum network, you will do so with other apps, and those apps could get you additional yield on top of ETH’s native APY.

Here is a recap of what the CEO of Eigenlayer Sreeram Kannan spoke about over a discord AMA last year.

1/ We recently spoke with @eigenlayer CEO and Co-Founder @sreeramkannan, during our Discord AMA.

Here’s what you missed 🧵 pic.twitter.com/RERIefyZIv

— vVv (@vvvdotnet) October 8, 2022

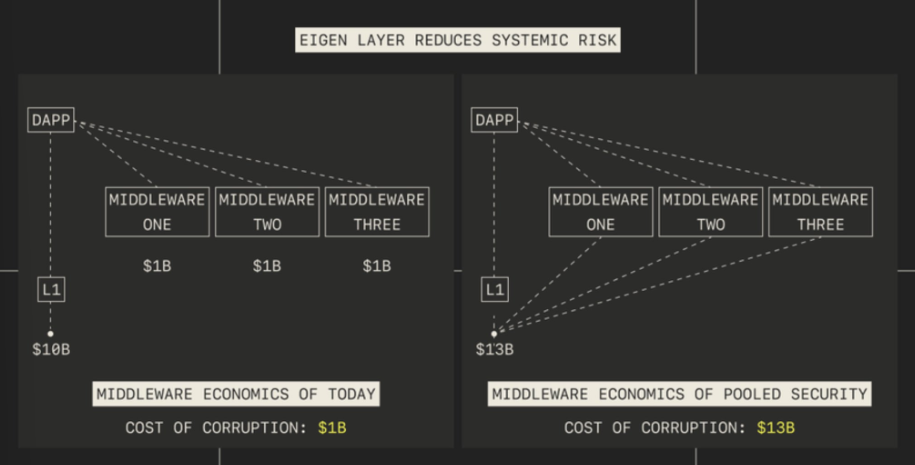
According to NewOrderDAO’s predictions for 2023, “Eigen will be the most important innovation for Ethereum. Through re-staking, which leverages an existing trust network to secure other infrastructure and middleware layers, Eigen significantly reduces security costs and systemic risk.”

The chart above shows that the cost of corruption needed to bring down a particular dApp will be much higher as the middleware security will all be contributed to a pooled security.

If the attacker wants to attack a protocol backed with Eigen support, they have to attack the security provider and the network of ETH validators supporting the protocol.

Their attempt to improve Ethereum as a base layer might be a viable option in a way that we have not seen flashbots modify the Ethereum client to support off-chain transactions ordering auctions for MEVs.

The risks

With your dedicated funds allocated to Eigen, you are also giving control of your staked ETH to Eigen. This gives rise to security concerns over the validator.

Irony eh? It ensures security but derives security concerns over validators.

An application could potentially steal your stake if there is a security flaw. When Eigen communicates with the middleware to secure bridges, oracles etc., there is a chance your ETH gets slashed if there’s any misbehaving.

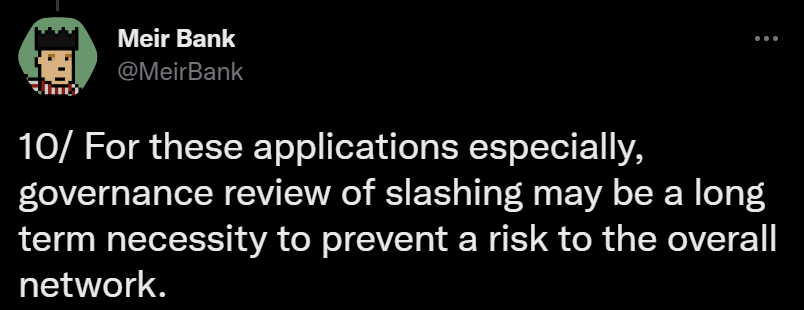
There could also be a delay in slashing. According to Meir Bank, “it will be possible for Eigenlayer to delay slashing pending a governance process to confirm or overturn a slash before it is finalized.”

This means the role of validators in performing due diligence is paramount for this success. Otherwise, when large numbers of ETH validators run an application, it could seriously impact Ethereum, leading to a considerable percentage of ETH supply loss.

Use cases

Some use cases arise with the full development of Eigenlayer; here is a quick summary before diving into some of them.

I'm far too smooth-brained to have any idea about whether or not @eigenlayer will work. But it's definitely one of the most interesting and potentially groundbreaking concepts to emerge in crypto as of late.

Here are some takes by people much smarter than me...

🦙 🏫 ⬇

— Alpaca College (@AlpacaCollege) October 29, 2022

Bridges

The best use cases for Eigenlayer are protocols with a low chance of being slashed. For instance, protocols that go live often might not be a good fit as there is always a high chance that a server could crash and eventually lead to stakes being slashed.

On the other hand, Bridges might be a better fit. Bridges such as Hyperlane have a low chance of being slashed because of their flexibility and no liveness requirements for nodes. This gives Eigenlayer a conducive environment for it to thrive.

Other protocols include Succinct, Axelar network along with squid.

Layer2 rollups

While we see the emergence of multiple layer2s storming into the scene, Eigenlayer will run rollup sequencers, enabling sequencers for L2s like Optimism and Arbitrum to be decentralized and secure.

“Decentralized sequencers will either be able to create transaction priority auctions like Flashbots or use fair/randomized order.”

Oracles

This might be another good fit because they are secured by the token’s value, like $LINK. By securing an oracle network with more collateral, oracles can gain 10x in security, reducing the likelihood of a profitable Oracle attack on DeFi.

RPC Nodes

A Remote Procedure Call (RPC node) is a computer server that allows users to read data on the blockchain and send transactions to different networks.

Eigenlayer will enable genuinely decentralized RPC nodes. Existing solutions like the POKT network and either centralized providers like Infura could make a possible move to Eigenlayer. Decentralized RPC is critical to avoid censorship on the client level.

Appchains

The rise of the appchain thesis at the end of 2022 created a lot of discussion among web2 leaders. On the Eigenlayer, various deployment protocols can bootstrap their security for new appchains, with value accrual returning to ETH as the base security as collateral.

Another well-known protocol coming to Cosmos.

In Terra's days of glory, Prism had over $500M TVL.@dYdX and @mars_protocol will also launch their own Cosmos chain soon.

Appchain Thesis is getting more popular🪐 https://t.co/zmHbOsDZcE

— The DeFi Investor 🔎 (@TheDeFinvestor) December 2, 2022

Closing thoughts

In the recent interview with Eigenlayer’s CEO on a bankless podcast, Sreeram talked about how Eigen runs on internal governance devnet and the onboarding of first protocols.

This project might have its token, eventually. But will that change anything? I see Eigenlayer as a new way to see Ethereum, not just for security and securing the network, but we must think beyond it.

What if Binance could run BSC but secure it from staked ETH?

What if we could run Chainlink oracles but secure it from staked ETH?

Huge alpha there. Event driven state updates (like collateral refilling, liquidation, atomic arbs with value flow to arb-ed protocols) can be built on @eigenlayer. https://t.co/bSolcnK6hS

— EigenLayer (@eigenlayer) October 20, 2022

What if we could mint a stablecoin on DeFi, but use $ETH staked in our solo validator as collateral?

The possibilities are endless, and while they all come with their respective arguments and trade-offs, it may be a barter I’d take.

Trust and security in crypto are the hardest to obtain yet most accessible to lose; having this installation of Eigen may prove to be one of the better trust layers out there. Eigen is the first in the business, but they probably won’t be the last. As this sector spurs, new ideas and innovation will kickstart new use cases and solo validators, improving decentralization and trust and security.

Also Read: Key Takeaways From Messari’s Top 10 DeFi Trends In 2023

[Editor’s Note: This article does not represent financial advice. Please do your research before investing.]

Featured Image Credit: ChainDebrief

  •  

Here’s What They Won’t Tell You About The Bear Market

It’s 2023 and there is no doubt that we are in the midst of a multi-year bear market. While this has become painfully obvious with the collapse of CeDeFi, the new narratives and thought leaders in crypto have yet to be properly etched out.

However, many crypto participants have been quick to latch onto trends, nostalgic of the gains made or missed in the bull market.

If you’re still in crypto however, it’s time to re-evaluate your view of the market, and where the bear will take us.

Also Read: This Bear Market Is Trying To Teach You Something

“Web3.0” is Dead, Long Live Crypto

Love it or hate it, the term “web3.0” comes from a centralized, capitalistic point of view. The incessant need to rebrand “crypto” originated from its negative connotations with cyber criminals, drugs, and online gambling.

Furthermore, the infancy of crypto meant that there were a lot of rough patches that the industry as a whole had to figure out.

2) We're going back to "crypto" (native, organic, punk rock) vs. "Web3" (bad juju, consultant approved, weak) in 2023.

More Personal Wallets, Privacy, DeFi, DePIN.

Less exchanges, black box lenders, and ponzinomics.

— Ryan Selkis 🥷 (@twobitidiot) December 22, 2022

Web3.0 was a term used sparsely in conjunction with the ideals of crypto – decentralization and self-custody.

With only builders and long-term believers remaining, it is nigh time that these ideals lead the entire space, and we return to what crypto was originally about.

Once we reach proper product-market fit is achieved in crypto, we won’t need buzz words like “web3.0” – it will simply sell itself.

Fundamentals are in, and Retail Will Be Destroyed

With the collapse of most decentralized and centralized ecosystems, there will likely be a reemergence of importance in “DYOR”, with extreme checks and balances for funds still looking to invest.

Gone are the days of spray and pray tactics which guaranteed any VC a 100x on launch day. Instead, there will likely be an equities-like evaluation of any major project alongside extremely critical scrutiny.

While memes can, and will continue to succeed, the constant 1000x pumps pushed by crypto influencers will die in the bear.

What is @bonk_inu and how has it taken over @solana? This new dogcoin has a > $50M market cap and rising! 🐕#SOL #Solana #BONKhttps://t.co/boioqYvW7f

— BSC News (@BSCNews) January 3, 2023

A key example is Bonk Inu, a doge-like memecoin native to the Solana Network. Despite it’s narrative-grabbing rise, it has managed barely double digit returns since its release.

Products like GMX, Cap Finance, and Uniswap, instead, may see a return to stardom, as we migrate our funds back to Dino-Defi, if anything at all.

7/ Dying yields meant on-chain asset managers became invisible to most of crypto

However, as the market cycle shifts away from memes to fundamentals, asset managers could stand to net higher returns https://t.co/dniovi6ehT

— Chain Debrief (@ChainDebrief) January 3, 2023

With the return of fundamentals, one thing is for sure – retail’s advantage will slowly be chiseled away, much like with equity markets.

There’s No Point in DCA-ing

“Time in the market beats timing the market” is a popular saying amongst crypto influencers.

The phrase is borrowed from the stock market, which has a historic upward trend, and an average return of 10%.

In crypto, however, most coins fall spectacularly from grace.

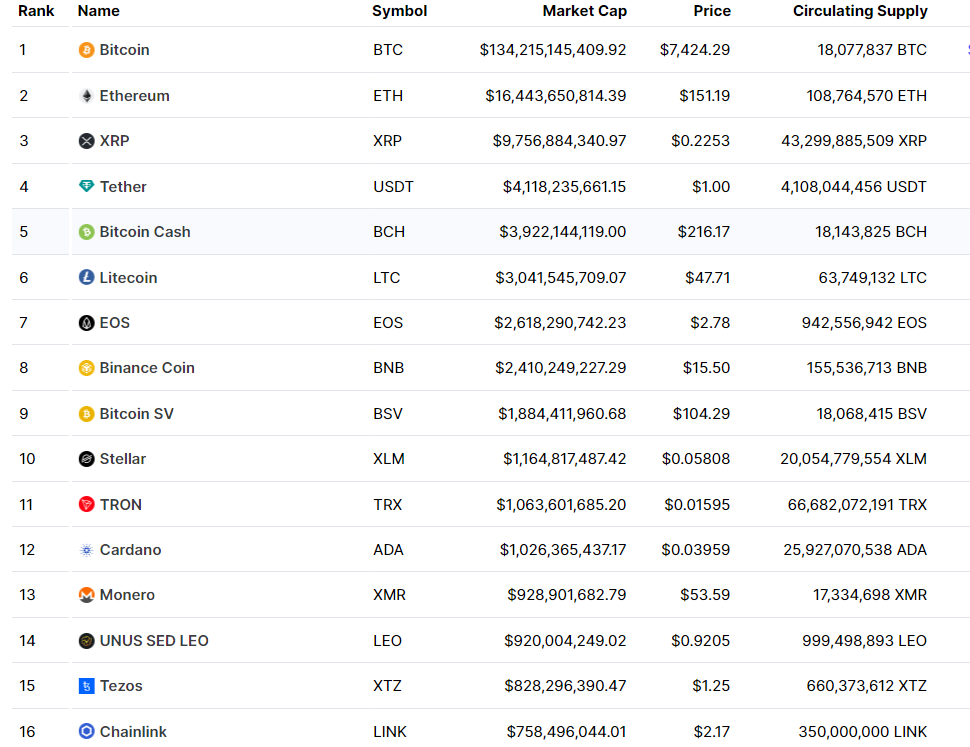
Image Courtesy: Coinmarketcap

A quick look at the top coins of 2019 shows that many of them have failed to outperform even Bitcoin, aside from Ethereum.

As such, fans of the DCA method have two major outcomes they have to decide between

  • DCA into a non-blue chip that is likely to fail
  • DCA into ETH/ Bitcoin and not outperform the market

While the latter option is likely a safe 5-10x, factoring in the rugs, volatility, and headaches along the way, it may be best to chase those kinds of multiples elsewhere.

Closing Thoughts

If you’re still here in 2023, it means that you haven’t (yet) given up on crypto. You’re here despite FTX, despite rugs, and despite >99% crashes.

However, pure conviction is not the end all be all. Whether you are a speculator or a builder in the space, theories need to be re-written and past portfolio all time highs have to be relinquished.

Coming into the new year, we should all approach Web3.0, I mean crypto, with a fresh slate.

Also Read: Key Takeaways From Messari’s Top 10 DeFi Trends In 2023

[Editor’s Note: This article does not represent financial advice. Please do your research before investing.]

Featured Image Credit: ChainDebrief

  •  

Here’s How To Onramp Your Funds Without Using FTX

I’m sure everyone’s wish for Christmas and the New Year is that no more centralised entities go bust and that we start seeing higher prices. Well, we can’t control both, but at least we can limit our exposure to the former and be advocates of self-custody.

A centralised exchange (CEX) holds custody of your money. If a CEX abuses this custodial relationship, you can potentially lose everything that you have inside, ahem FTX. It’s not the end of the world without CEXes because there are fiat-to-crypto onramps for topping up your wallet and getting right into non-custodial DeFi without ever having to store a single cent on those arcane exchanges.

Today, we will look at how users can get into crypto without ever entrusting their funds to the hands of a CEX. Here’s our guide to crypto on-ramping without a CEX.

1) MoonPay

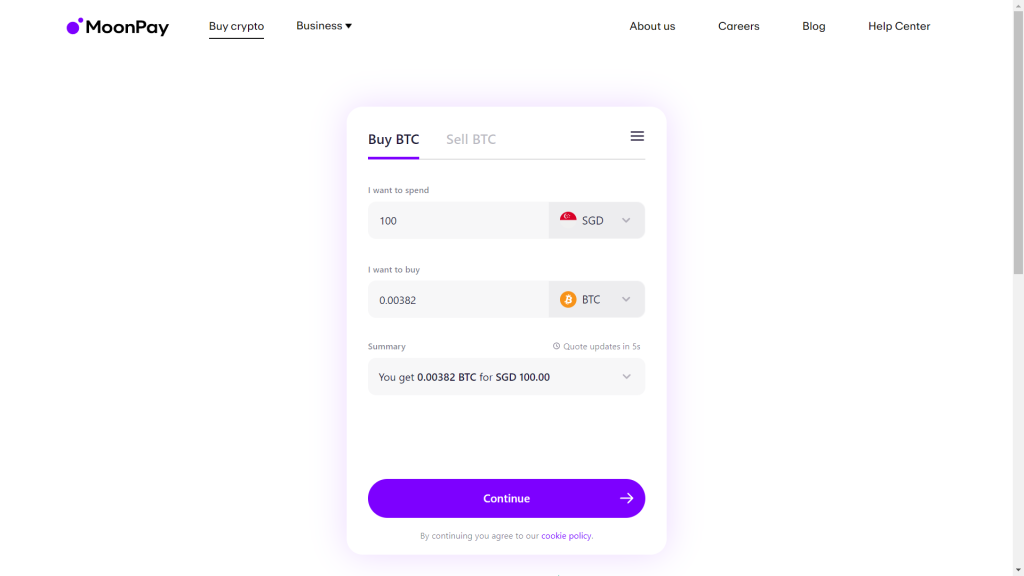
MoonPay is a financial technology company that builds payment infrastructure for cryptocurrencies. Their suite of on-and-off-ramp products provides a seamless experience for users to convert between fiat currencies and crypto using all major payment methods, including debit and credit cards, local bank transfers, Apple Pay, Google Pay, and Samsung Pay.

MoonPay is active in more than 160 countries and is trusted by 300+ leading wallets, websites, and applications to accept payments and defeat fraud.

Image Credit: MoonPay

MoonPay offers 23 different crypto coins for users to easily swap with a fee of 1% for bank transfers. For more information on their fee structure, you can click here.

1/ Go direct to DeFi 🚄

Starting today, you can now purchase crypto on the Uniswap Web App using a credit/debit card or bank transfer at the best rates in web3 thanks to our partnership with @moonpay! 💸https://t.co/YVyk8e6d2h

— Uniswap Labs 🦄 (@Uniswap) December 20, 2022

2) Transak

Transak is an onramp and offramp service that supports 130 cryptocurrencies on 75+ blockchains via cards, bank transfers and other payment methods in 125+ countries.

Image credit: Transak

Transak sources liquidity from over ten exchanges to offer the best price for their customers and offers a robust risk engine with less than a 0.05% fraud rate thus far.

Making crypto more accessible for millions of users via @CoinbaseWallet!

We are excited to announce @Transak's integration with @CoinbaseWallet🚀

🇵🇭 Buy Crypto from the Philippines
🇹🇭 and Thailand
🤩Pay with 10+ local payment methods

👉https://t.co/3c2TaXnNya pic.twitter.com/Cugvd7VPvx

— Transak (@Transak) December 2, 2022

For more information on their fee structure, you can click here.

3) Ramp

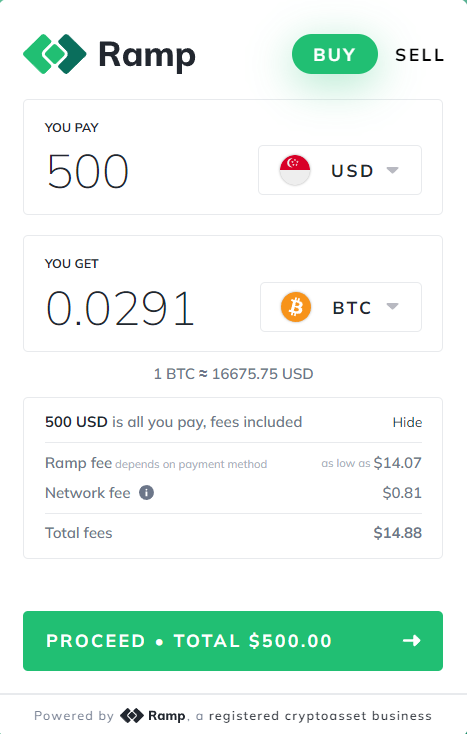
Ramp is a crypto onramp and offramp service that specialises in facilitating in-app crypto purchases for web3 projects. Ramp aggregate multiple local payment methods to offer the best price, UX, and broadest coverage. Users can purchase crypto using debit and credit cards, bank transfers, Apple Pay and Google Pay, with local payment methods in the works.

Image Credit: Ramp

Why Ramp?

  • Security: Ramp is fully non-custodial and audited by an expert at Quantstamp. Registered as a crypto asset business by the FCA.
  • Ease of use: Experience the state-of-the-art onboarding process for newbies and pros.
  • Smart KYC: Get verified most easily – connect your bank and get your crypto in seconds.
  • Competitive rates & fees: The more you buy, the less you pay. Fees start from a mere 0.49%.
  • Fastest fiat-to-crypto: Ramp’s instant verification and settlement get your crypto in minutes.

Finally, @RampNetwork also announced the release of one of the fastest and cheapest off-ramps in crypto, with support for 34 assets across 17 different blockchains.

Optimism users in the US can use it to off-ramp $DAI and $ETH.https://t.co/M0vCT4BabW

— Optimism (✨🔴_🔴✨) (@optimismFND) December 16, 2022

For more information on their fee structure, you can click here.

4) Banxa

Banxa is a financial technology platform that provides fiat-to-crypto onramp services plus off-ramping services for stablecoins. Banxa offers more global and local payment options than any other on-and-off-ramp solution resulting in conversion rates up to three times higher than credit card-only solutions.

Image Credit: Banxa

With Banxa, users have access to 79 different cryptocurrencies, including lesser used stablecoins such as USN, SUSD and CUSD.

Banxa announces its partnership with @1inch to create greater access to DeFi assets by tapping into Banxa's global/local payments options. Read more here: https://t.co/C1Vxw6Ukha

— Banxa (@BanxaOfficial) November 29, 2022

5) Mt Pelerin

Mt Pelerin is a non-US, no-KYC crypto onramp based out of Switzerland.

Mt Pelerin offers an ultra-competitive and attractive rate compared to all the other fiat-to-crypto platforms out there. Users get live market prices and the lowest fees with no hidden costs. On top of that, no identification is required, and anyone can purchase their preferred crypto instantly by card or bank transfer.

Users also have the ability to withdraw them at any time in 14 different currencies back to their bank account in one of the 171 countries supported.

Image Credit: Mt Pelerin

Mt Pelerin offers users a feeless purchase for their first CHF500 or equivalent in a year. Above that, a small percentage fee is charged, which can be discounted if you own their native token MPS.

For more information on their fee structure, you can click here.

Conclusion

While centralised exchanges are popular because they provide easy venues for fiat-to-crypto and crypto-to-crypto trading, they can mishandle customers’ funds. Such ease comes at the cost of a custodial relationship where the exchange ultimately controls any funds you choose to store with them.

By the basis of virtue, a CEX should always maintain customer holdings 1:1. The nightmare scenario is a situation like the FTX debacle where SBF’s trading arm commingled customer funds.

Hence, engaging in a fiat-to-crypto platform allows you to have custody over your assets from the get-go. These onramps are compelling because they offer users ways to quickly go from cash to crypto and right to their personal wallets without giving up control of their funds.

It is important to note that these fiat-to-crypto platforms still have centralised elements, and many require to Know Your Customer info. These platforms are great alternatives if you want to get your crypto directly without touching a CEX.

[Editor’s Note: This article does not represent financial advice. Please do your own research before investing.]

Featured Image Credit: Chain Debrief

  •  

The Harsh Reality Of Crypto; Secrets VCs Are Not Sharing With You

The bear market has brought a time of quiet reflection to investors in the space. Did DeFi fail? Does the Metaverse really have a future? Are trading NFTs just a Ponzi? Is my coin better than any others? What makes or break a project? These are some of the crypto questions VCs might not want to answer or tell you the truth on.

Today, let’s deep dive into a thread warning us on what we as retail investors should be wary of.

Crypto isn't a fair playing field.

The truth is that 99% of "retail" investors are at the behest of the top whales and VCs. So, how can you break the mould?

🧵: Here are 5 things that crypto whales and insiders don't want you to know (but you should). 👇

— Miles Deutscher (@milesdeutscher) May 3, 2022
Credits: Miles Deutscher

[Author’s Note: This article was adapted from a tweet by @milesdeuscher, a crypto influencer on Twitter. What you read should be used for educational and learning purposes and does not serve as financial advice.]

1. The Problem With DeFi Tokens

DeFi has worked quite wonderfully and reliably for its users. Lending, borrowing, trading spot on a DEX, or even trading synthetic assets or derivatives have been a solid demonstration of what decentralized financial products on-chain are like.

However, one key structural problem exists with DeFi platforms. It is, in my opinion, an open secret: where do the tokens fit in?

In DeFi, liquidity mining rewards exist for a reason: it serves to bootstrap the ecosystem by attracting total value locked and more liquidity, thus allowing it to generate some revenue – e.g borrowing fees, vault management fees, trading fees. But what happens after the bootstrap phase?

Miles argues that while tokens are a good way for decentralizing governance and enable a secondary market, most of these tokens are simply unnecessary.

Tokens that do not capture value long term and earn a piece of the protocol’s revenue are valueless and ultimately dump hard once the hype from farming fades away.

Image Credit: @milesdeutscher

Miles also raises a good point on DeFi token emissions: while these are attractive as initial rewards with high APR, they gradually enter the circulating supply and due to inflationary pressures, cause the value to plummet over time.

2. Bullish Crypto Unlocks by VCs? Think Again

2021 is a story of bullish unlocks

— Zhu Su 🔺 (@zhusu) January 7, 2021
Credit: @zhusu

In general for projects, VCs and private rounds get into these tokens at massive discounts during seed rounds or private rounds. Here are some details on the private rounds for the following L1s:

  • SOL: $0.04
  • FTM: $0.043
  • AVAX: $0.50
  • BNB: $0.15

Most of us retail forget that the market price might fall 50% from your initial entry, but private investors might still be up many times and in heavy profit.

The bullish unlock meme which worked in the past is unlikely to happen in the bear market as massive unlocks happen and private investors want to realize their gains and minimize their losses in a market downturn.

In fact, you should look at the portion of the supply that is unlocked and how steep the “cliffs” are when circulating supply increases.

Gradual unlock vs steep cliff unlock. Image Credits: @cobie

Consider that token unlocks could also occur alongside protocol emissions, leading to a rapid increase in circulating supply over time.

And when the musical chairs stop and everyone is rushing for the exits, will the market demand be able to support current valuations?

$dydx down 92% and still $2bn+ FDV

2022-2023 will be a rough year for altcoins, people will start to understand the importance of FDV’s.

— Algod🫐 (@AlgodTrading) May 21, 2022
Credit: AlgodTrading

3. Lack Of Product

Miles’ next criticisms can be broadly applied to the wider crypto market, but is most apparent among Metaverse projects and “GameFi” – many of these projects have massive valuations (>$100m) without any actual game/NFT released or any form of actual revenue back to the holder.

While the market is pricing in future growth, how does this apply in a bear market where growth becomes relatively stagnant and unlocks on token supply start happening?

Personally, NFTs and GameFi have been a good exposure for beginners to enter the market and take a look at what blockchain offers. However, we still have a long road ahead, and I just do not agree with the fact that gaming projects that have not created a strong use-case for its token can be worth hundreds of millions of dollars.

4. APRs are meant to incentivise liquidity

In the real world, when companies first launch they often offer promotions to incentivise people to spend money/grow accustomed to their product.

In crypto, instead of incentivising via discounts, DeFi projects use token emissions to incentivise early liquidity.

This model has worked very successfully for the likes of $LUNA (via @anchor_protocol) and @CurveFinance as claimed by Miles.

However, these emissions end up being their downfall. Often times, the tokenomics lead to over dilution and a huge increase in circulating supply.

The question still stands, “what happens when emissions run out?” Well, protocols will need to pivot from incentivising liquidity towards incentivising fees.

Holders should primarily generate a return via fees, not emissions.

5. Crypto Whale/VCs Movements

For this section, Miles gives the age old adage by Warren Buffet: “Be fearful when others are greedy, and greedy when others are fearful.”

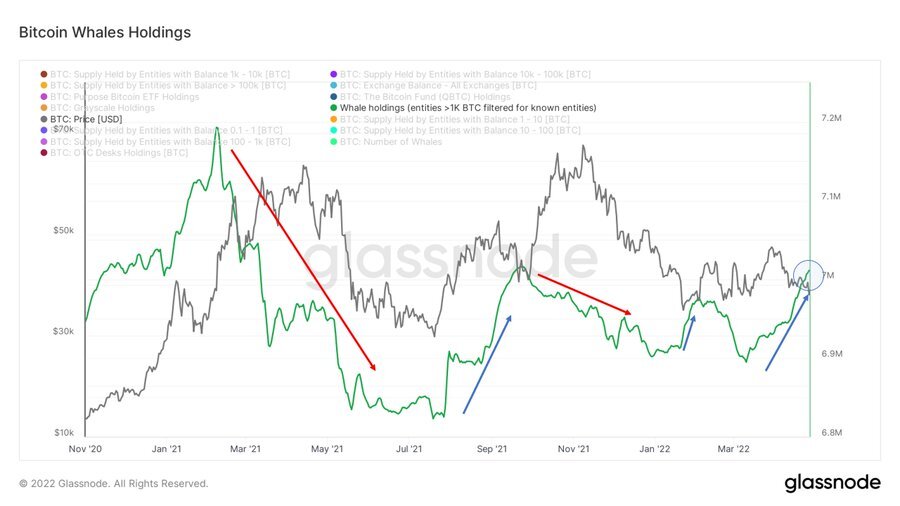
Whale holdings are roughly inversely correlated to price, and they tend to accumulate when the market is in max fear, and sell when people are too greedy.

Image Credit: glassnode

This suggestion does make sense and highlights that most of us retail are often just small fishes in the sea – we often tend to ride the trends of what they are doing and most of the time, end up as exit liquidity.

To me, looking at on-chain data and what wallets are doing is just one part of a strategy you should employ. Furthermore, their accumulation and holdings might not paint the exact picture of what they are actually doing.

You should be aware that whales are just like you, and often, funds and whales do blow up and they can be wrong.

Solutions for retail

So far we have the following problems:

  • Farming tokens are inflationary and (usually) valueless. Your holdings are eventually diluted.
  • Token unlocks are significant in bear market
  • Lack of actual product/delivery compared to funds raised

Does the team have a track record? Who are the investors? Is the current valuation reasonable compared to other projects in the same category?

Examining tokenomics is also important. Here are the following suggested from Miles’ tweets:

  • Projects that generate real revenue from fees compared to emissions
  • Revenue flows back to holder (a.k.a token value accrual)
  • Tangible user growth
  • Do not blindly chase yield

Closing Thoughts

I featured this tweet in the article as it highlights some very obvious incentive problems in crypto, and these weaknesses become very apparent in the bear market.

Of course, talking about it during the bull run is usually ineffective as number go up and people that stay in the sidelines apparently have fun staying poor.

It also does not seem clear to me (so far) what the best token value accrual mechanics are, and how exactly do certain projects and alts justify their prices once demand starts to fall off. Finding that one project or protocol that has strong incentive structures tied to their token, and can be sustainable in the long run is my goal in this current climate.

I always take a default stance of skepticism and believe that having strong critical opinions on a project and helps to filter out bad projects before I make a decision. Hopefully this tweet helps you the same way as it did for me – until then, do your own research, and survive.

[Editor’s Note: This article does not represent financial advice. Please do your own research before investing.]

Featured Image Credit: Chain Debrief

Also Read: House Money Effect: 4 Mistakes That Crypto Investors Will Fall Prey To

  •  

Top 5 Crypto Tools That Will Turn You Into An On-Chain Wizard

In crypto, public blockchains are permissionless and every on-chain transaction is recorded and stored on the public ledger. This article will talk about several on-chain analytics tools in crypto readily accessible for you.

For instance, all the transactions on the Ethereum blockchain are all stored on the blockchain for everyone to see. Every swap and every NFT purchase can be tracked on-chain.

With that said, there’s no better place to get alphas than on the chain itself. Everyone wants to be an on-chain wizard but not many know where to start and what tools to use.

Without further ado, here are the top 5 tools that will turn you into an on-chain wizard:

1. Etherscan

Image Credit: Etherscan

Etherscan is a blockchain explorer for the Ethereum network. The website allows you to search through transactions, blocks, wallet addresses, smart contracts, and other on-chain data.

On the surface, Etherscan is just a block explorer that normies use to look at transactions. But deep down, Etherscan can be used for a variety of functions from making transactions to reading token data.

Credit: Wallet Stats on Etherscan
Credit: Etherscan Token Details

I think the best function of Etherscan is the ability to make transactions on it. It is easy to use and users can bypass buggy websites & crappy UI to interact directly with the smart contract.

Want to master Etherscan? Here Are 10 Ways To Master Etherscan And Discover The Next Crypto Alpha Before Everyone Else

2. Debank

Credit: Behance

Debank is an all-in-one cryptocurrency portfolio tracker designed to manage DeFi assets.

Debank allows users to track their full portfolio through various chains, compare interest rates, manage assets, find DeFi projects, analyze risks, and enable users to perform token swaps on token exchange.

Image Credit: Debank

The simple and user-friendly interface also makes it easy to track whale wallets and their activities. With a click on the button, you can see a detailed breakdown of their portfolio and holdings.

Read More: Crypto Scams Took 14 Billion USD In 2021 – How To Prevent Your Funds From Getting Stolen

3. Nansen

Credit: Nansen

Nansen is a Singapore-based blockchain analytics platform that combines on-chain data with a massive database containing millions of wallet labels.

“Nansen is currently the best on-chain analytics tool available on the market. It is my go-to dataset when attempting to dissect on-chain movements and to the learned eye, contains plentiful bouts of alpha. Definitely a must-use for crypto professionals”

Wangarian – DeFiance Capital
Credit: Nansen

Nansen comes with an endless list of features and dashboards. Token God Mode, Smart Money and Hot Contracts are some of the most popular features of Nansen.

The on-chain data platform just acquired Ape Board, one of the top portfolio tracker platform, for over US$10 million. It plans to incorporated it into its upcoming all-in-one super app.

Nansen just released a new lite version for free. Read more about it here: Crypto Analytics For Free: How To Use Nansen’s New Lite Version Of Its Analytics Platform

4. Dune Analytics

Image Credit: Dune Analytics

Dune Analytics is by far one of my favourite on-chain analytic tools. It is a powerful tool for blockchain research. It offers on-chain analytics dashboard for both technical and non-technical investors.

Credit: Dune’s NFT Market Volume
Credit: Dune’s DeFi users overtime

Dune gives you all the tools to query, extract, and visualize vast amounts of data from the blockchain, unlocking the power of public blockchain data by making it accessible to everyone.

The beauty of Dune is the flexibility it offers. There are thousands of different dashboards made by the community and some of the dashboards offer great insight into the on-chain activities.

5. Excel

Image Credit: Excel

Bet you’re not expecting to see Excel on this list but Excel is actually able to help with wallet tracking.

Excel sheet downloaded from Etherscan to track largest holdings of token

Basic Excel functions like VLOOKUP will help to make your life easier when scanning through thousands and thousands of transactions.

Rather than manually filtering, there is an in-built filter button on Excel that is also able to filter out all the unwanted or erroneous data.

Here is a more detailed step by step guide by StrategicHash on how to use excel for wallet tracking:

How to track influencer wallet addresses – NO python, NO API calls, NO coding needed. Only prerequisite is excel

🧵👇

— StrategicHash🔥 🤏💃 (@StrategicHash) April 14, 2022

Closing thoughts

Mastering these 5 tools would definitely help you level up your game and give you an edge over the other crypto newbies.

And the best of all, all these tools are free! All you have to do is to set some time aside to master these tools and incorporate them into your due diligence process. If done correctly, you will be finding alphas before they are up on Twitter.

Image Credit: Chain Debrief

Anyway, we have a whole list of crypto tools on our website. You can check them out over here.

[Editor’s Note: This article does not represent financial advice. Please do your own research before investing.]

Featured Image Credit: Chain Debrief

Also Read: Your First Step Into The Crypto World: Top 10 Free Crypto Tools

  •  

Hot Vs. Cold Wallets: Key Differences, And Why It’s Important To Own A Cold Wallet

Keeping the crypto you just bought on centralised exchange (CEX) is the easiest way to hold your token. But is it truly safe?

In 2021 alone, there were been more than 20 hacks on centralised exchanges, where hackers walked away with at least US$10 million.

A recent, high-profile hack saw Singapore based Crypto.com losing over US$30 million in Bitcoin and Ethereum.

Though Crypto.com made moves to repay all the funds and beef up its privacy and safety protocols, not all centralised exchanges will bear the losses.

Thus, cryptocurrency wallets can provide more protection but it is a bit more complicated. Cryptocurrency wallets can be categorised into two main types — hot and cold wallets.

Hot wallets explained

A hot wallet is a form of software wallet that is connected to the Internet. It can come in many forms from web-based wallets to mobile wallets. The best thing of all is that hot wallets are free!

In the event that you want to venture out and explore what decentralised finance (DeFi) has to offer, the most convenient way to interact with decentralized applications (dApps) is via a hot wallet.

Image Credit: Coincu News

Funds on hot wallets are also easily accessible and there is no need to transition between offline and online to make a transaction.

Cold wallets, on the other hand, would require users to transfer the funds into a hot wallet before they are able to make a transaction.

Do note that because hot wallets are connected to the Internet, they are still vulnerable to digital attacks.

MetaMask

Metamask hot wallet
Image Credit: MetaMask

Without a doubt, MetaMask is the most popular digital wallet in the crypto space with over 21 million users worldwide. There is even a swap function that allows users to swap tokens with ease.

It doesn’t end on the Ethereum blockchain. MetaMask also allows users to tap onto the Binance Smart Chain network to store and transact using BEP-20 tokens. It also supports other layer 2 networks like Polygon and Fantom.

Phantom

Image Credit: Phantom

Phantom is the number one crypto wallet on the Solana blockchain. Similar to MetaMask, it is a non-custodial digital wallet and is installed like a regular plugin.

There is an inbuilt gallery where users can see their NFT straight from the wallet. Phantom also just released an IOS version so iPhone users can easily access Phantom from their mobile devices.

Cold wallets explained

Image Credit: Forbes

Cold wallets or cold storage is a physical device that is able to store cryptocurrencies completely offline. Many come in the form of a USB stick and can range from US$30 to over US$200.

Because the device is able to store crypto offline, it can protect the investment from online hacks and digital attacks.

Image Credit: Forbes

There is a trade-off between accessibility and security as cold wallets are less convenient because the device must be connected to the Internet before any transaction can be made.

Most established CEXs will use a combination of hot and cold wallets. They will store majority of their fund in a cold wallet and only just enough liquidity in a hot wallet to service withdrawal transactions. This will ensure that majority of the fund are kept safe and sound.

Only buy cold wallet from an authorised dealer as second-hand device might be tampered with.

Ledger

Image Credit: Ledger

Ledger is by far one of the most popular cold wallets in the world. Its most popular product — the Ledger Nano S has sold over one million units worldwide. The wallets are equipped with industry-leading security to help keep crypto assets secure at all times.

It is also ready to launch their very own crypto debit card called the Crypto Life card. It is scheduled to launch in UK, France and Germany in Q1 of 2022 and would start to roll out in the US in Q2 of 2022.

Trezor

Image Credit: Easy Crypto

Trezor was the world’s first hardware wallet ever created. It prides itself on its open-source software and hardware that can be viewed publicly on GitHub.

It is almost impossible to hack as there is no username and password for the account. The credential is the Trezor device itself. This is why it is one of the safest ways to store cryptocurrency.

Wrapping up

Image Credit: Chain Debrief

In a nutshell, both hot and cold wallets are generally more secure than storing crypto on the CEX. While hot wallet is more user friendly and simpler to use, it is not advisable to hold large amount of crypto on a hot wallet.

It is by far more secure to keep crypto in a cold wallet instead. Even though it is more cumbersome to use. It is a small price to pay for peace of mind.

[Editor’s Note: This article does not represent financial advice. Please do your own research before investing.]

Featured Image Credit: Chain Debrief

Also Read: How To Use MetaMask To Take The First Step Into The World Of Decentralized Finance

  •  
❌